for the Budget? Dharshini David, Deputy economics editor at the BBC Jennifer McKeown, Chief Global Economist at Capital Economics James Smith, Chief Economist at the Resolution Foundation Chair: Ruth Curtice, Chief Executive of the Resolution Foundation Wifi 2QAG_Guest Welcome_Guests @resfoundation #HittingBuffers October 26
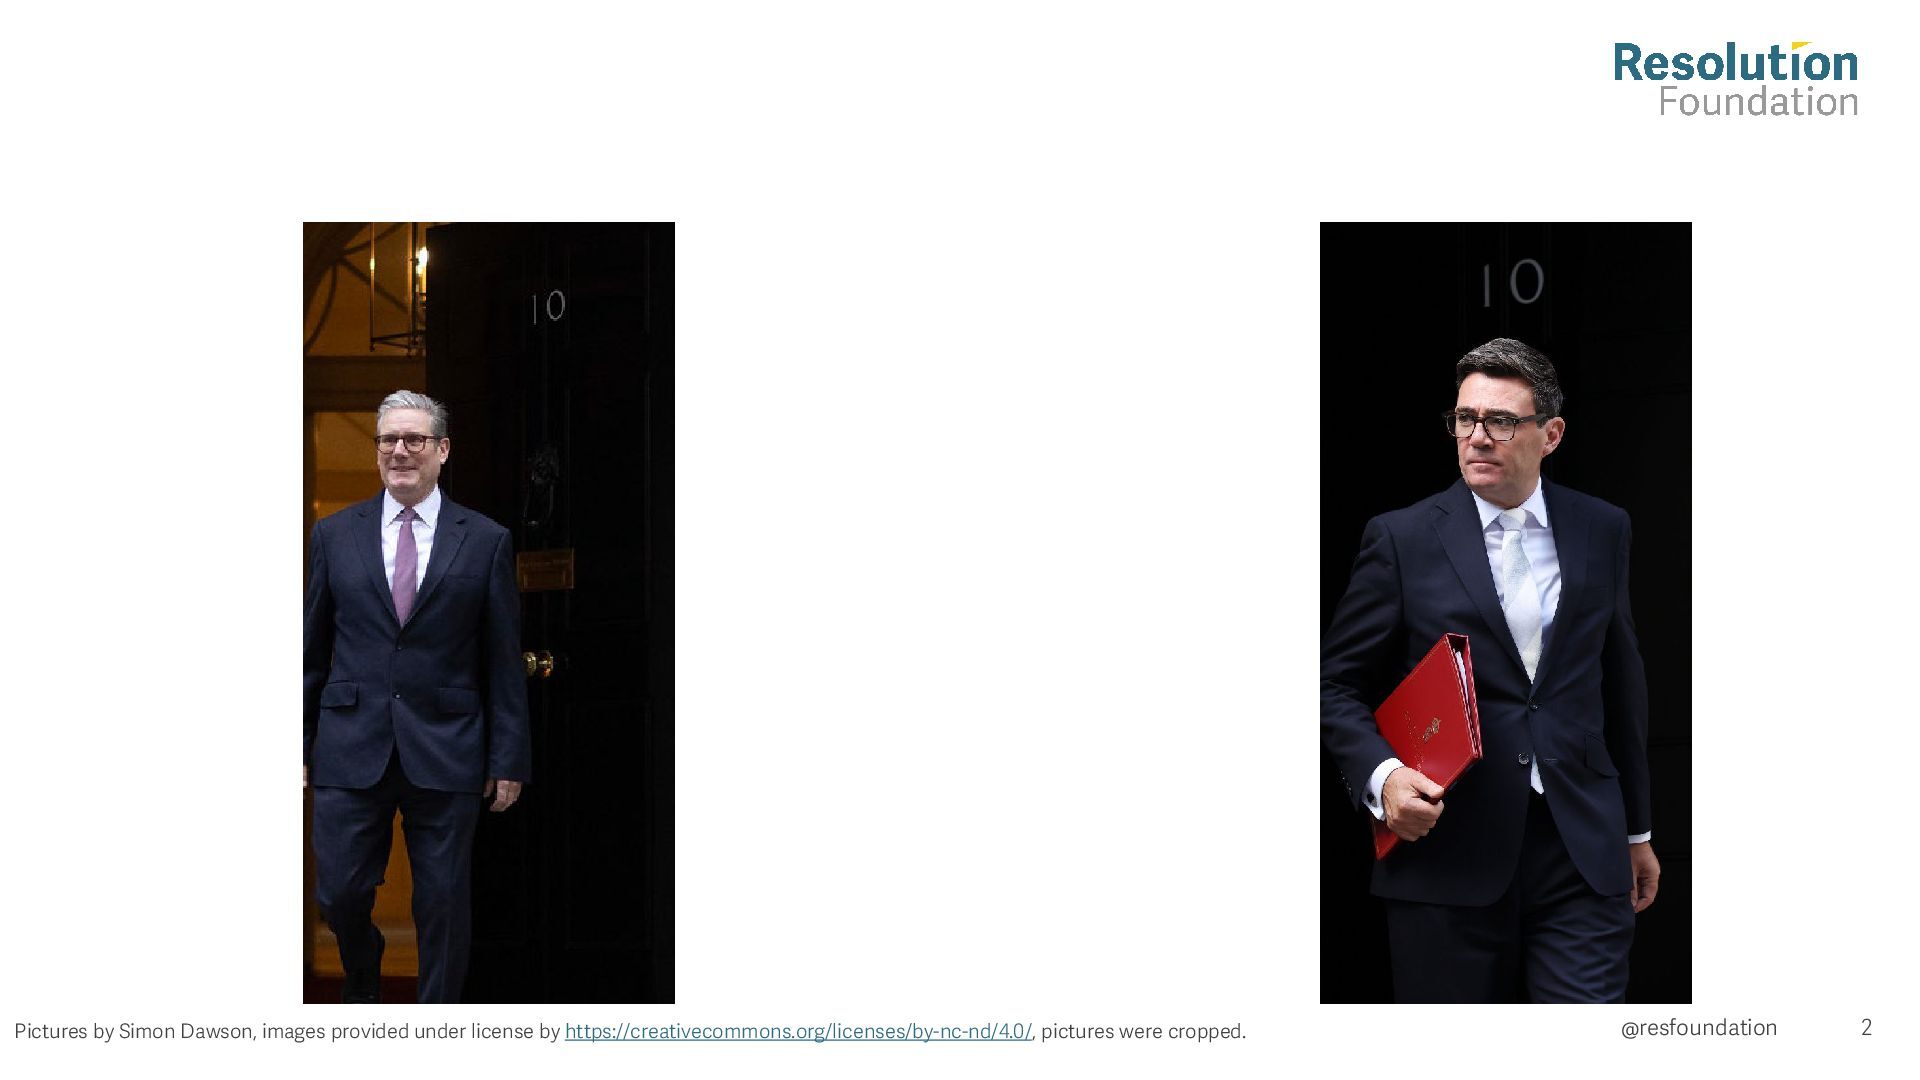
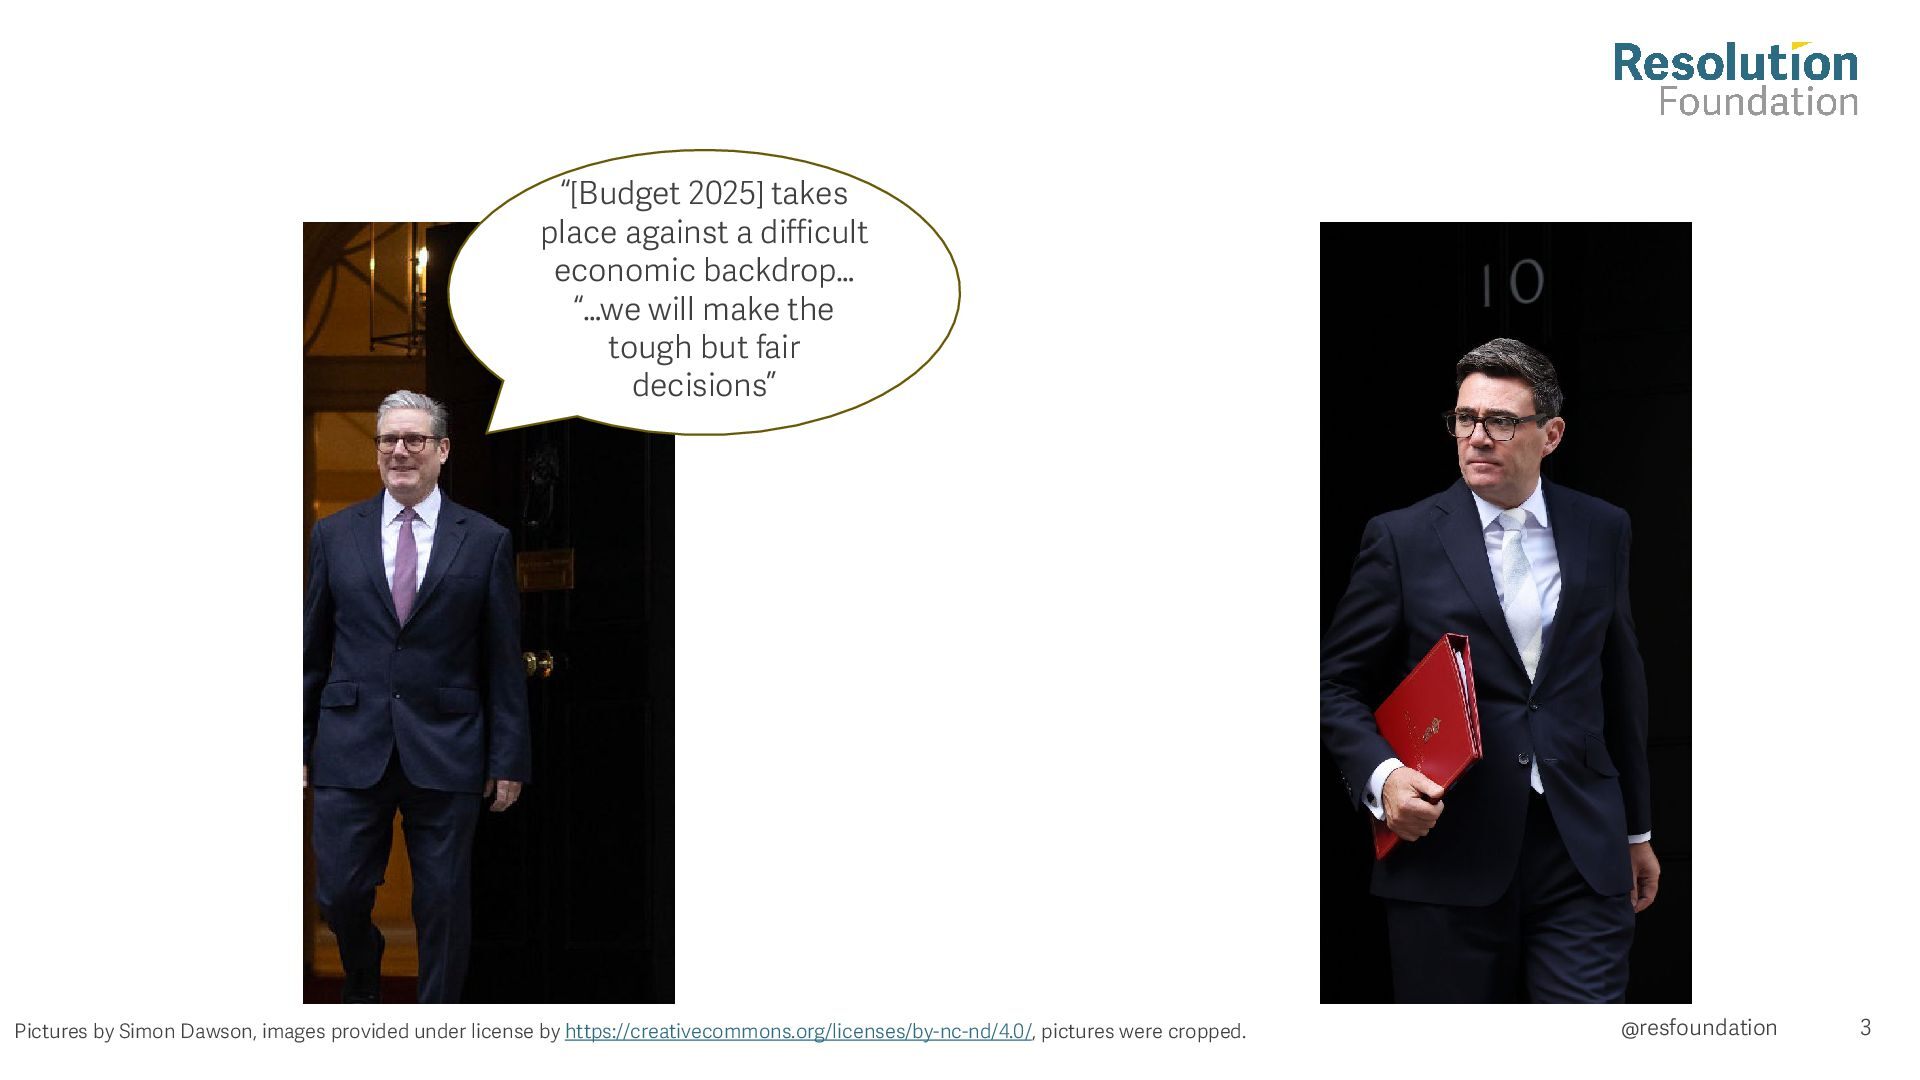
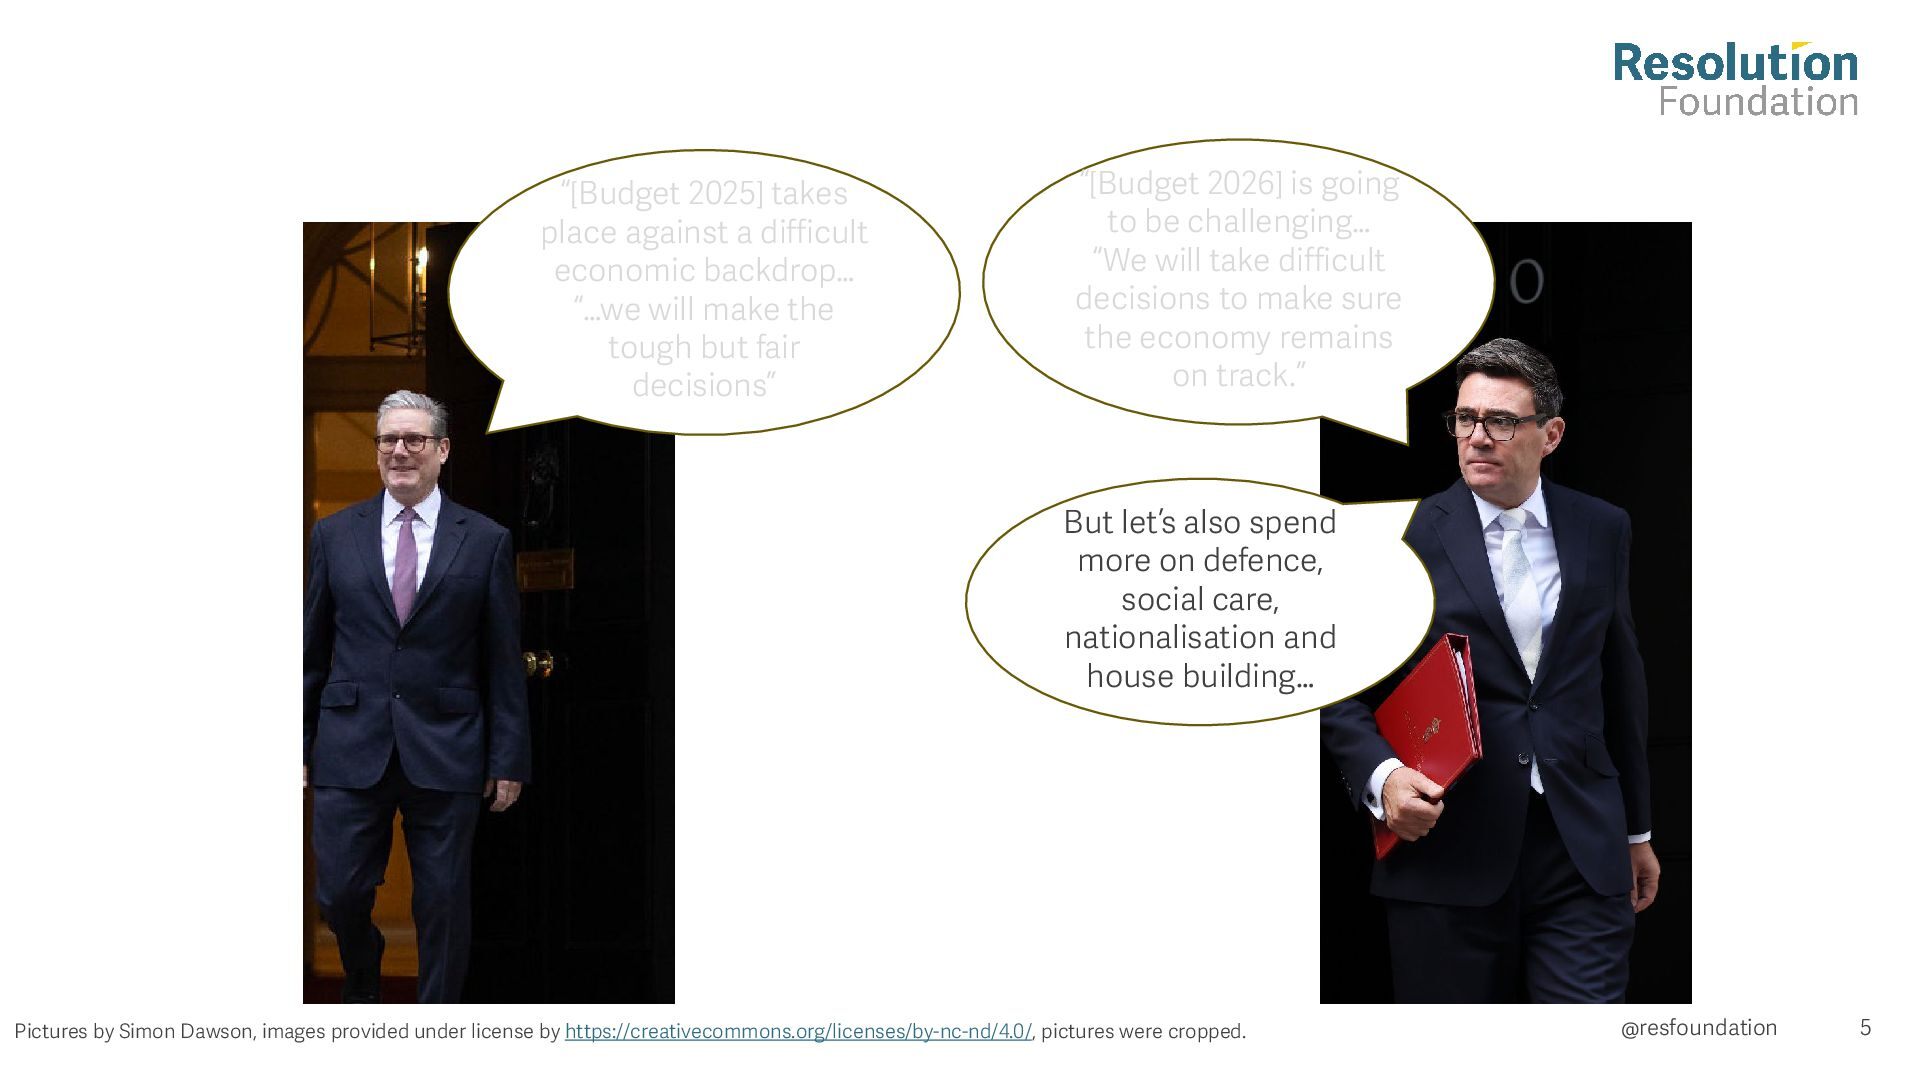
will make the tough but fair decisions” Pictures by Simon Dawson, images provided under license by https://creativecommons.org/licenses/by-nc-nd/4.0/, pictures were cropped. @resfoundation 3
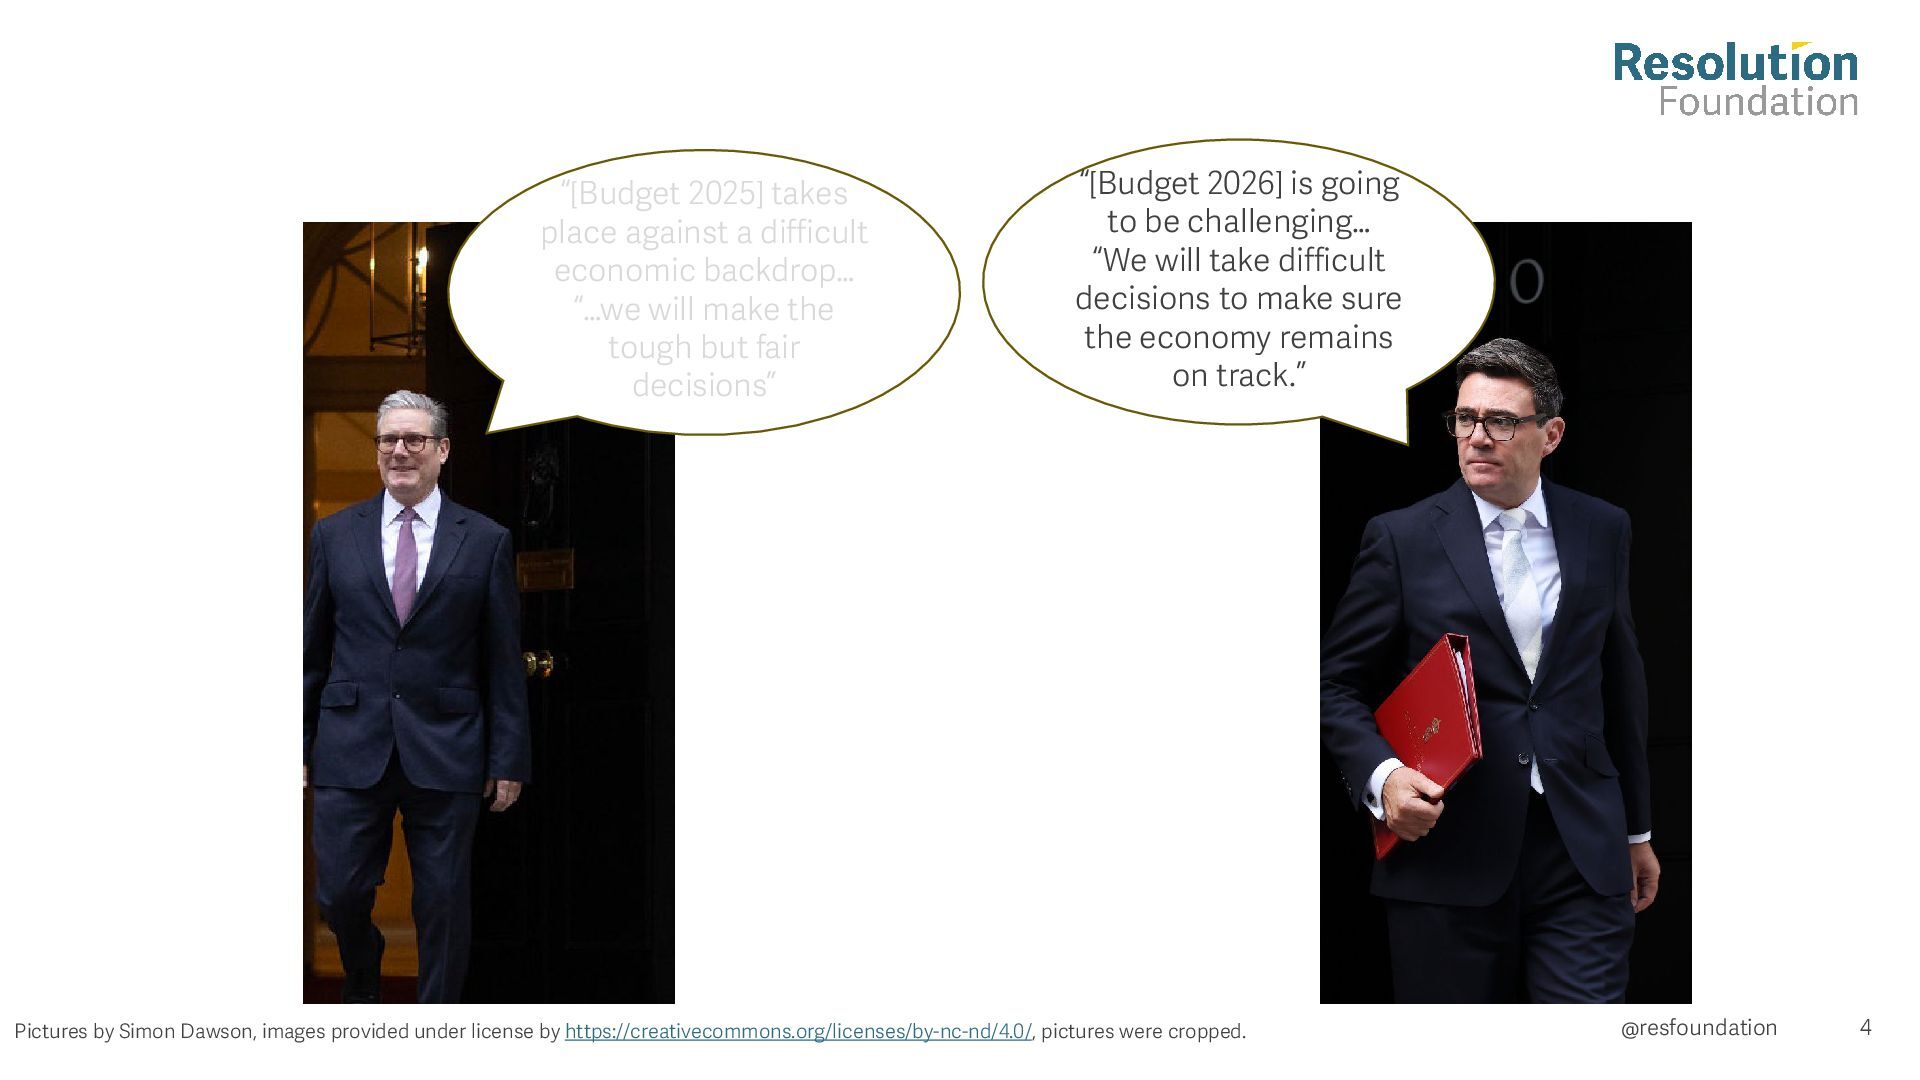
will make the tough but fair decisions” “[Budget 2026] is going to be challenging… “We will take difficult decisions to make sure the economy remains on track.” Pictures by Simon Dawson, images provided under license by https://creativecommons.org/licenses/by-nc-nd/4.0/, pictures were cropped. @resfoundation 4
will make the tough but fair decisions” “[Budget 2026] is going to be challenging… “We will take difficult decisions to make sure the economy remains on track.” But let’s also spend more on defence, social care, nationalisation and house building… Pictures by Simon Dawson, images provided under license by https://creativecommons.org/licenses/by-nc-nd/4.0/, pictures were cropped. @resfoundation 5
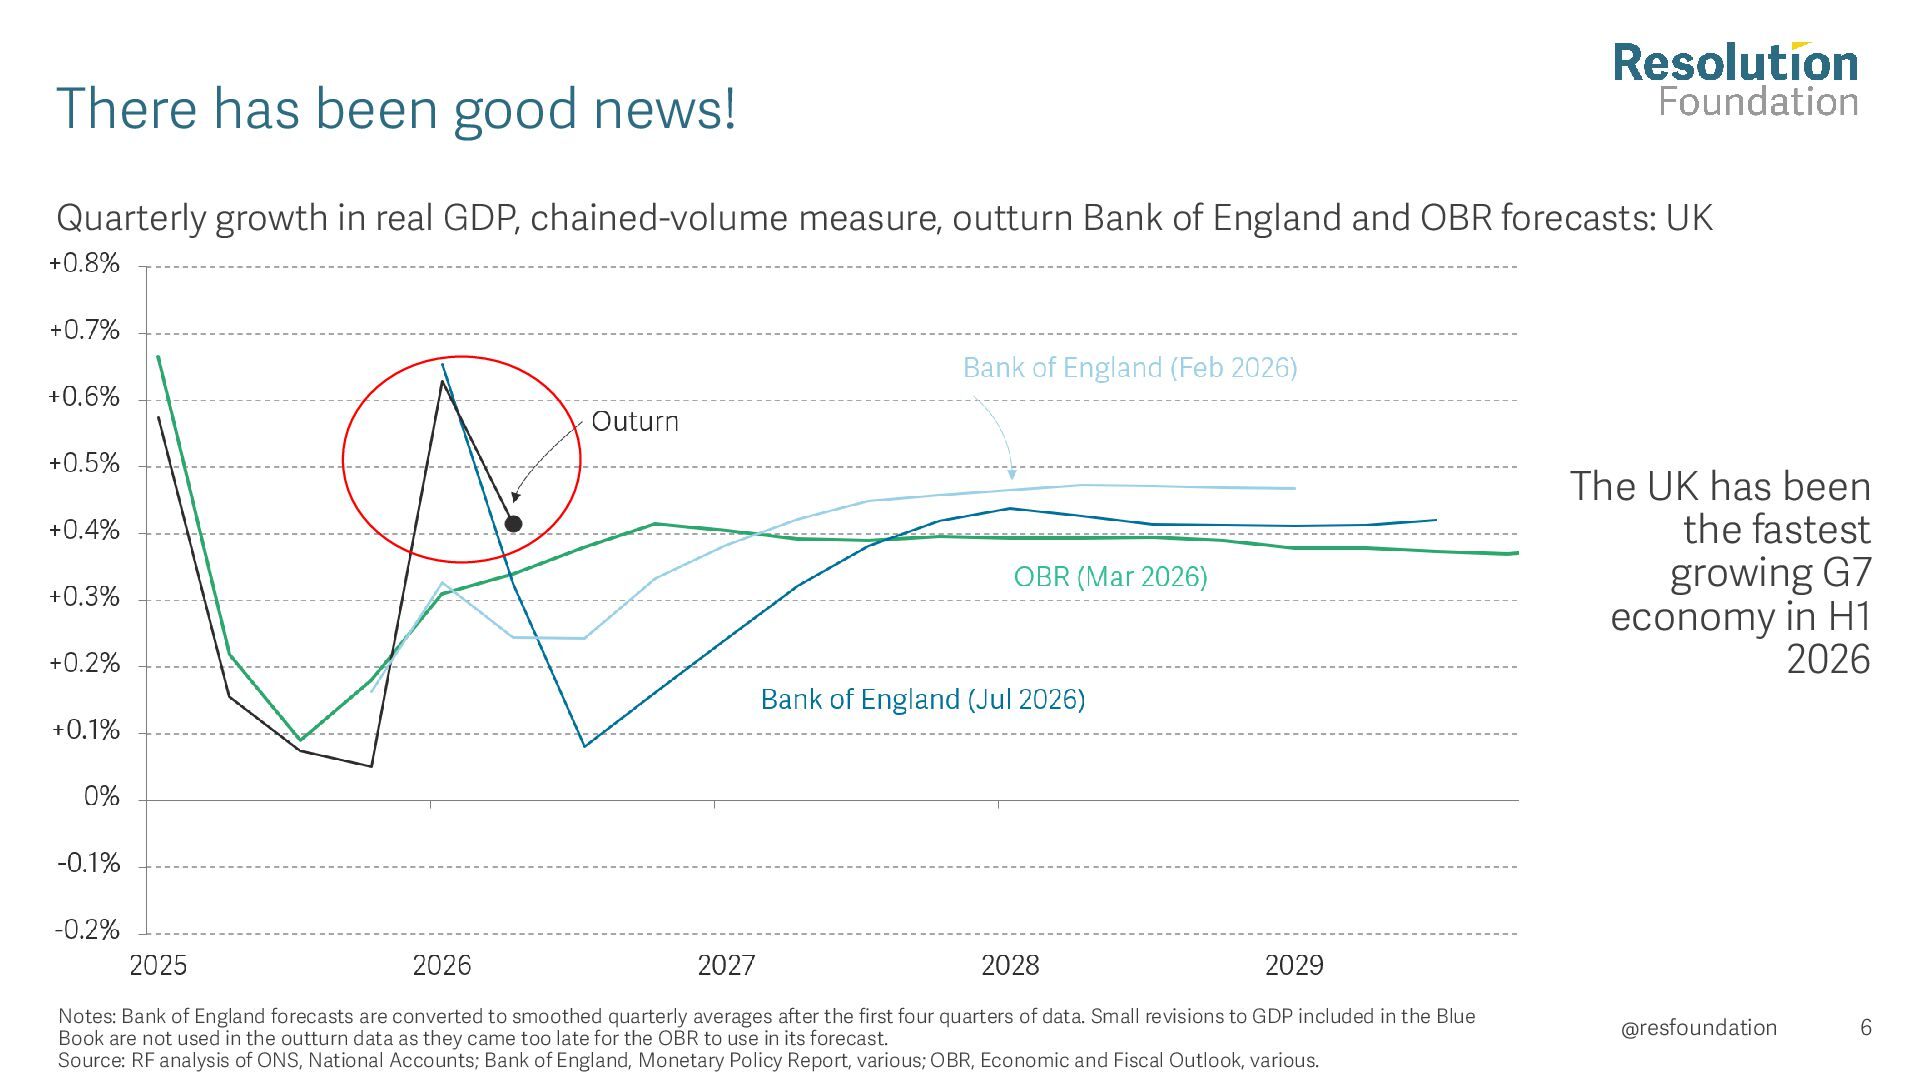
chained-volume measure, outturn Bank of England and OBR forecasts: UK The UK has been the fastest growing G7 economy in H1 2026 Notes: Bank of England forecasts are converted to smoothed quarterly averages after the first four quarters of data. Small revisions to GDP included in the Blue Book are not used in the outturn data as they came too late for the OBR to use in its forecast. Source: RF analysis of ONS, National Accounts; Bank of England, Monetary Policy Report, various; OBR, Economic and Fiscal Outlook, various. @resfoundation 6
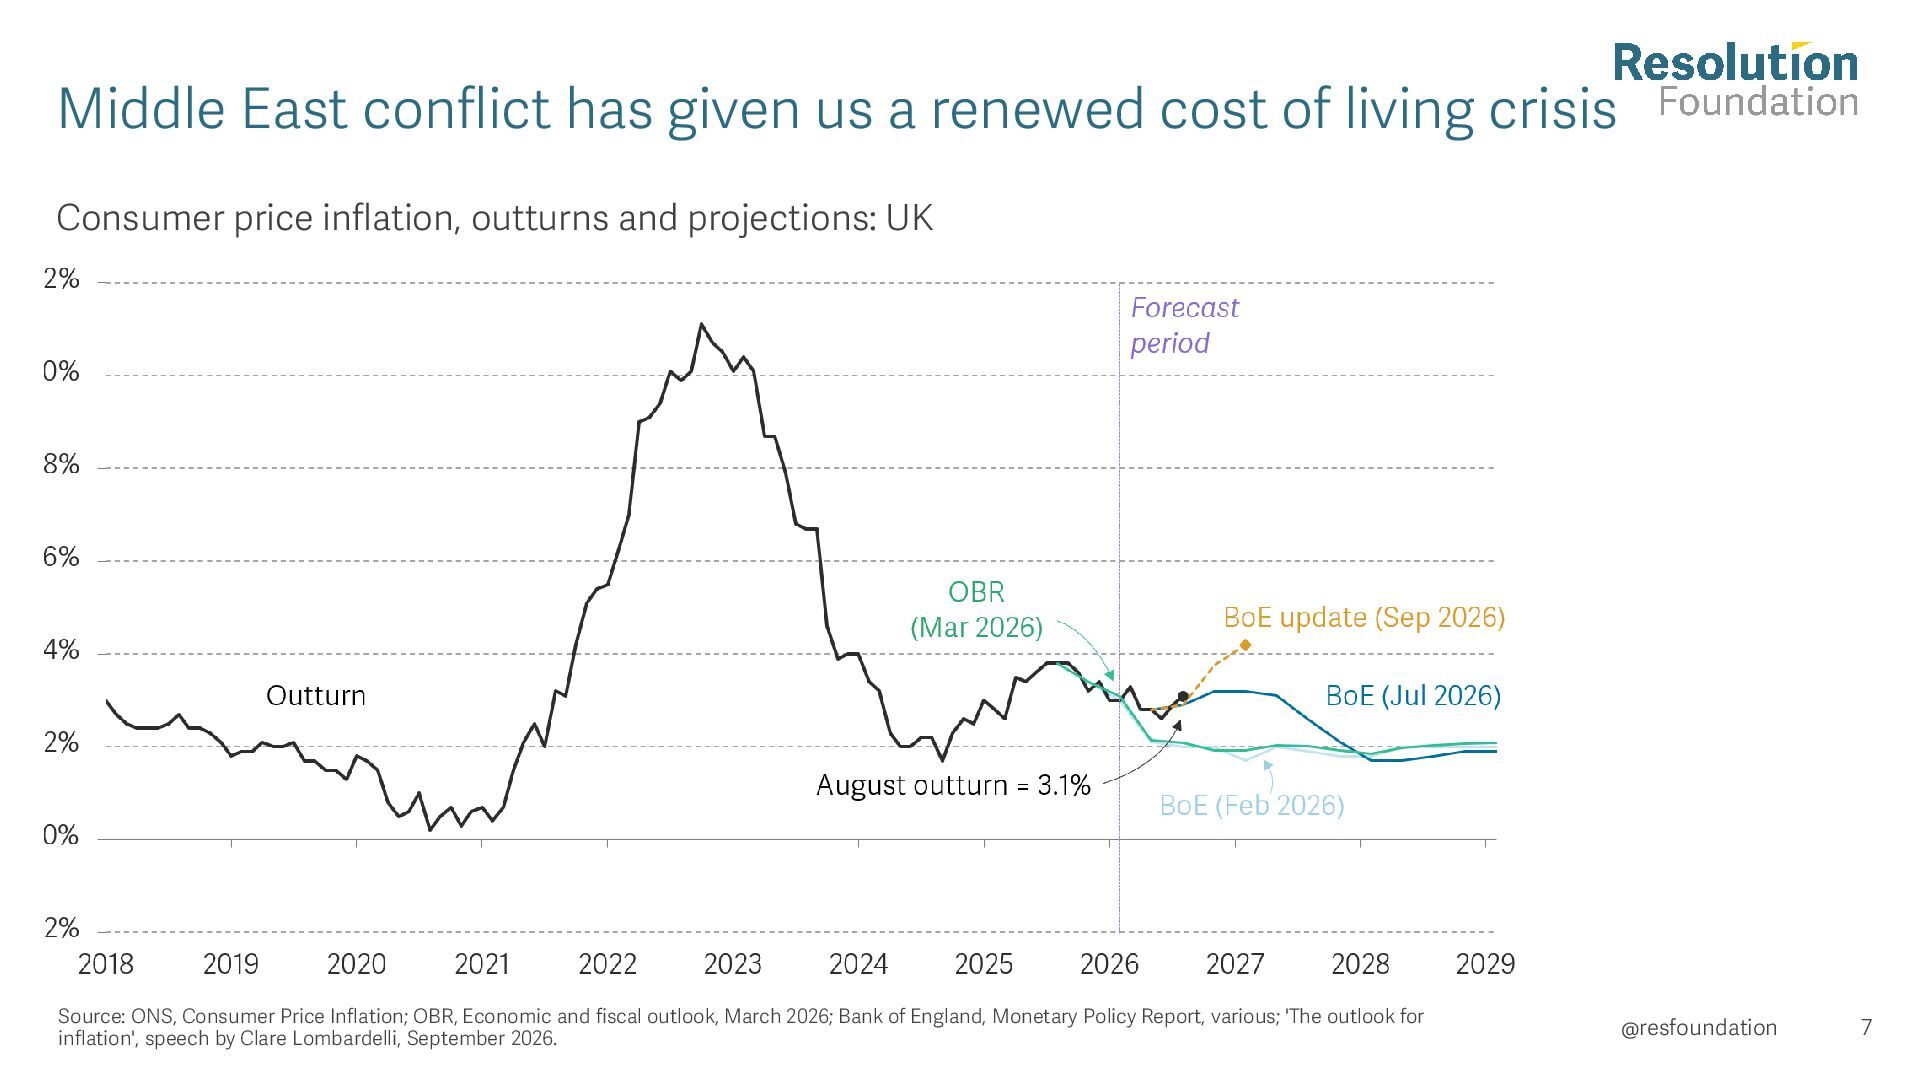
living crisis Consumer price inflation, outturns and projections: UK Source: ONS, Consumer Price Inflation; OBR, Economic and fiscal outlook, March 2026; Bank of England, Monetary Policy Report, various; 'The outlook for inflation', speech by Clare Lombardelli, September 2026. @resfoundation 7
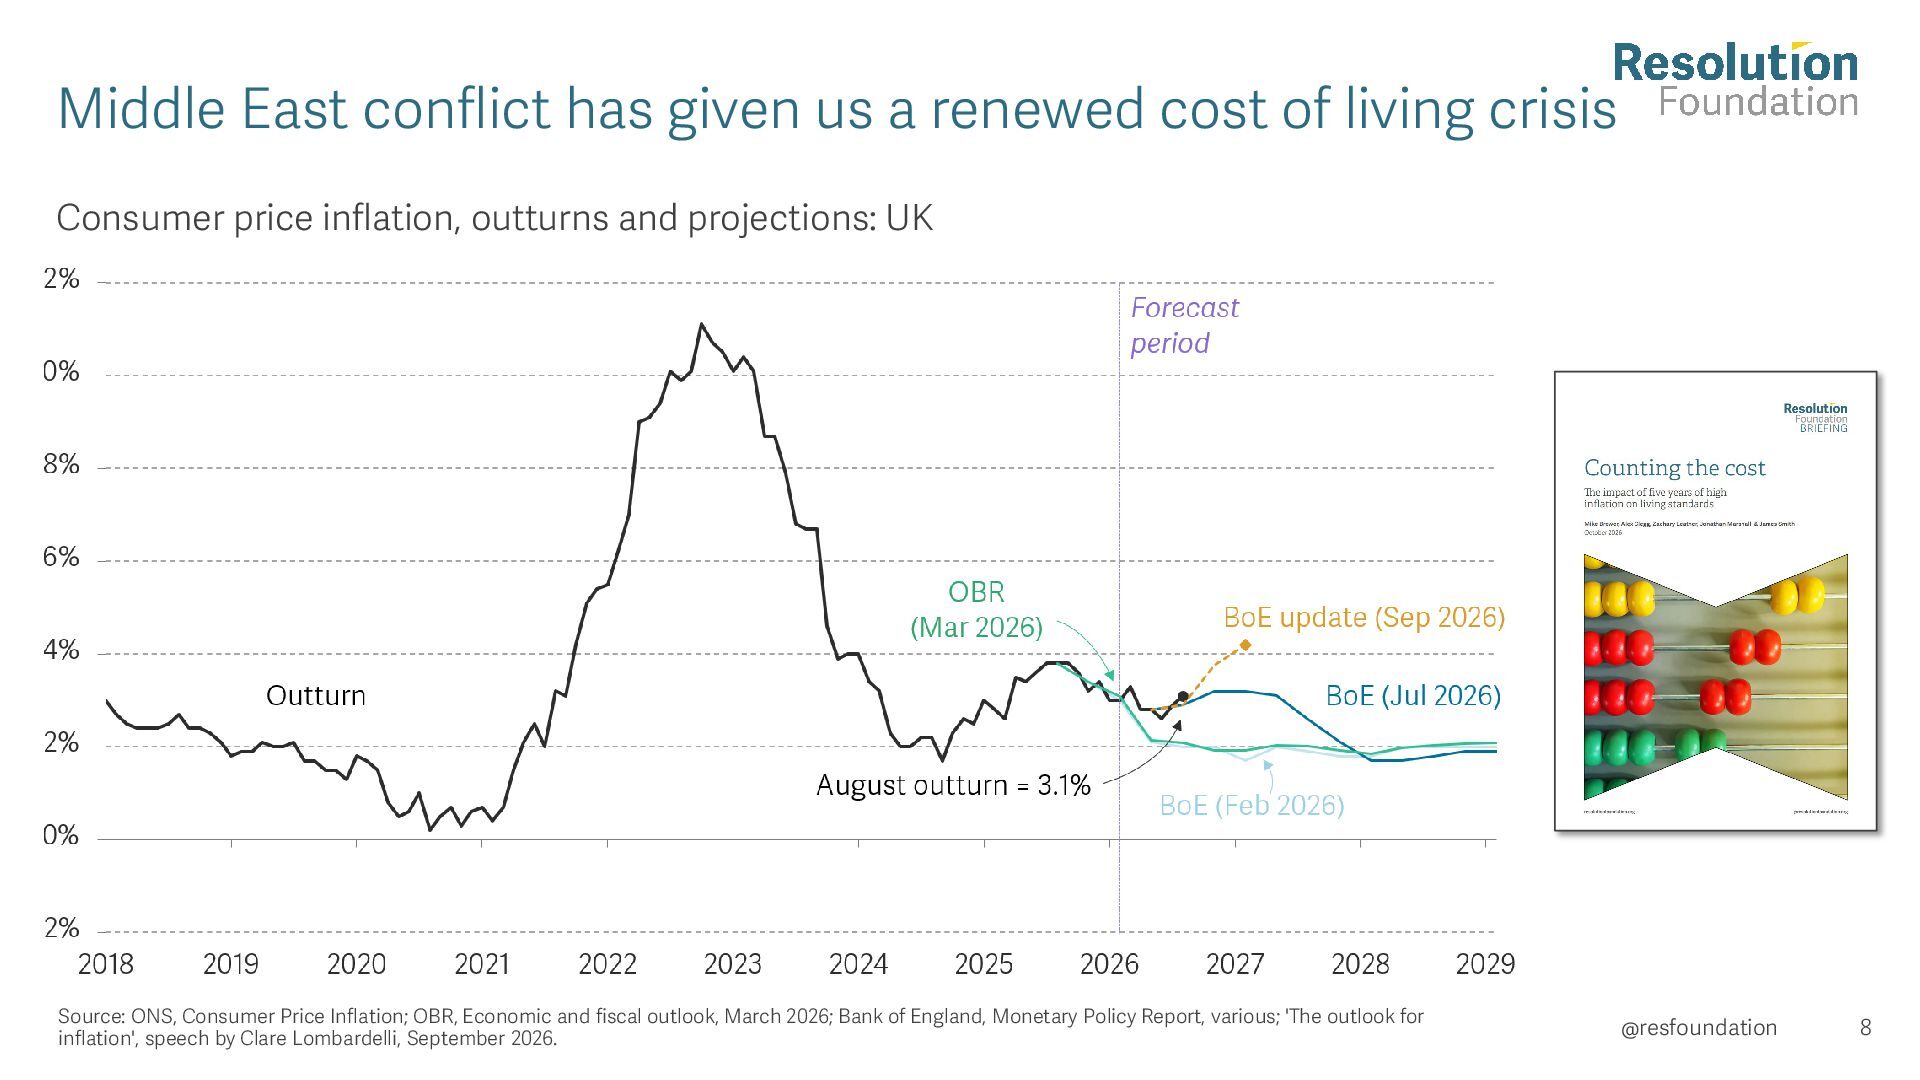
living crisis Consumer price inflation, outturns and projections: UK Source: ONS, Consumer Price Inflation; OBR, Economic and fiscal outlook, March 2026; Bank of England, Monetary Policy Report, various; 'The outlook for inflation', speech by Clare Lombardelli, September 2026. @resfoundation 8
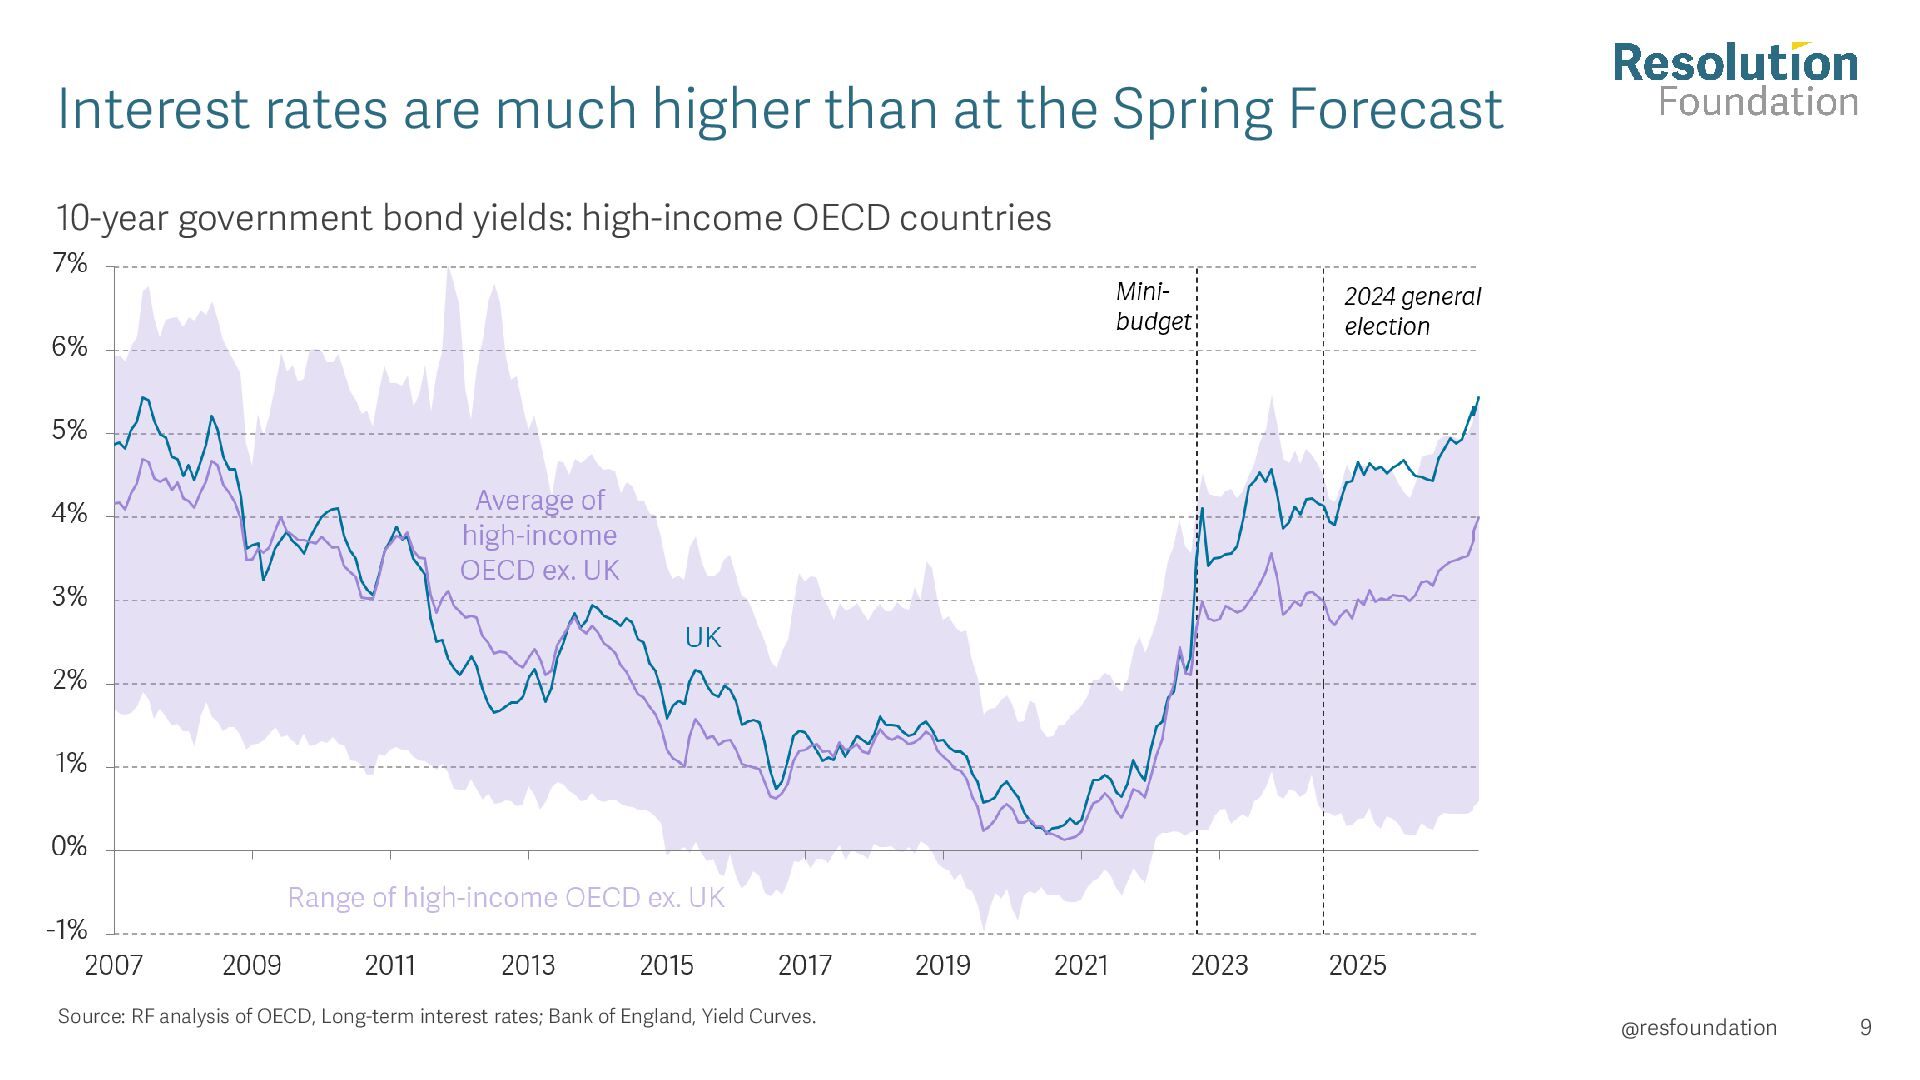
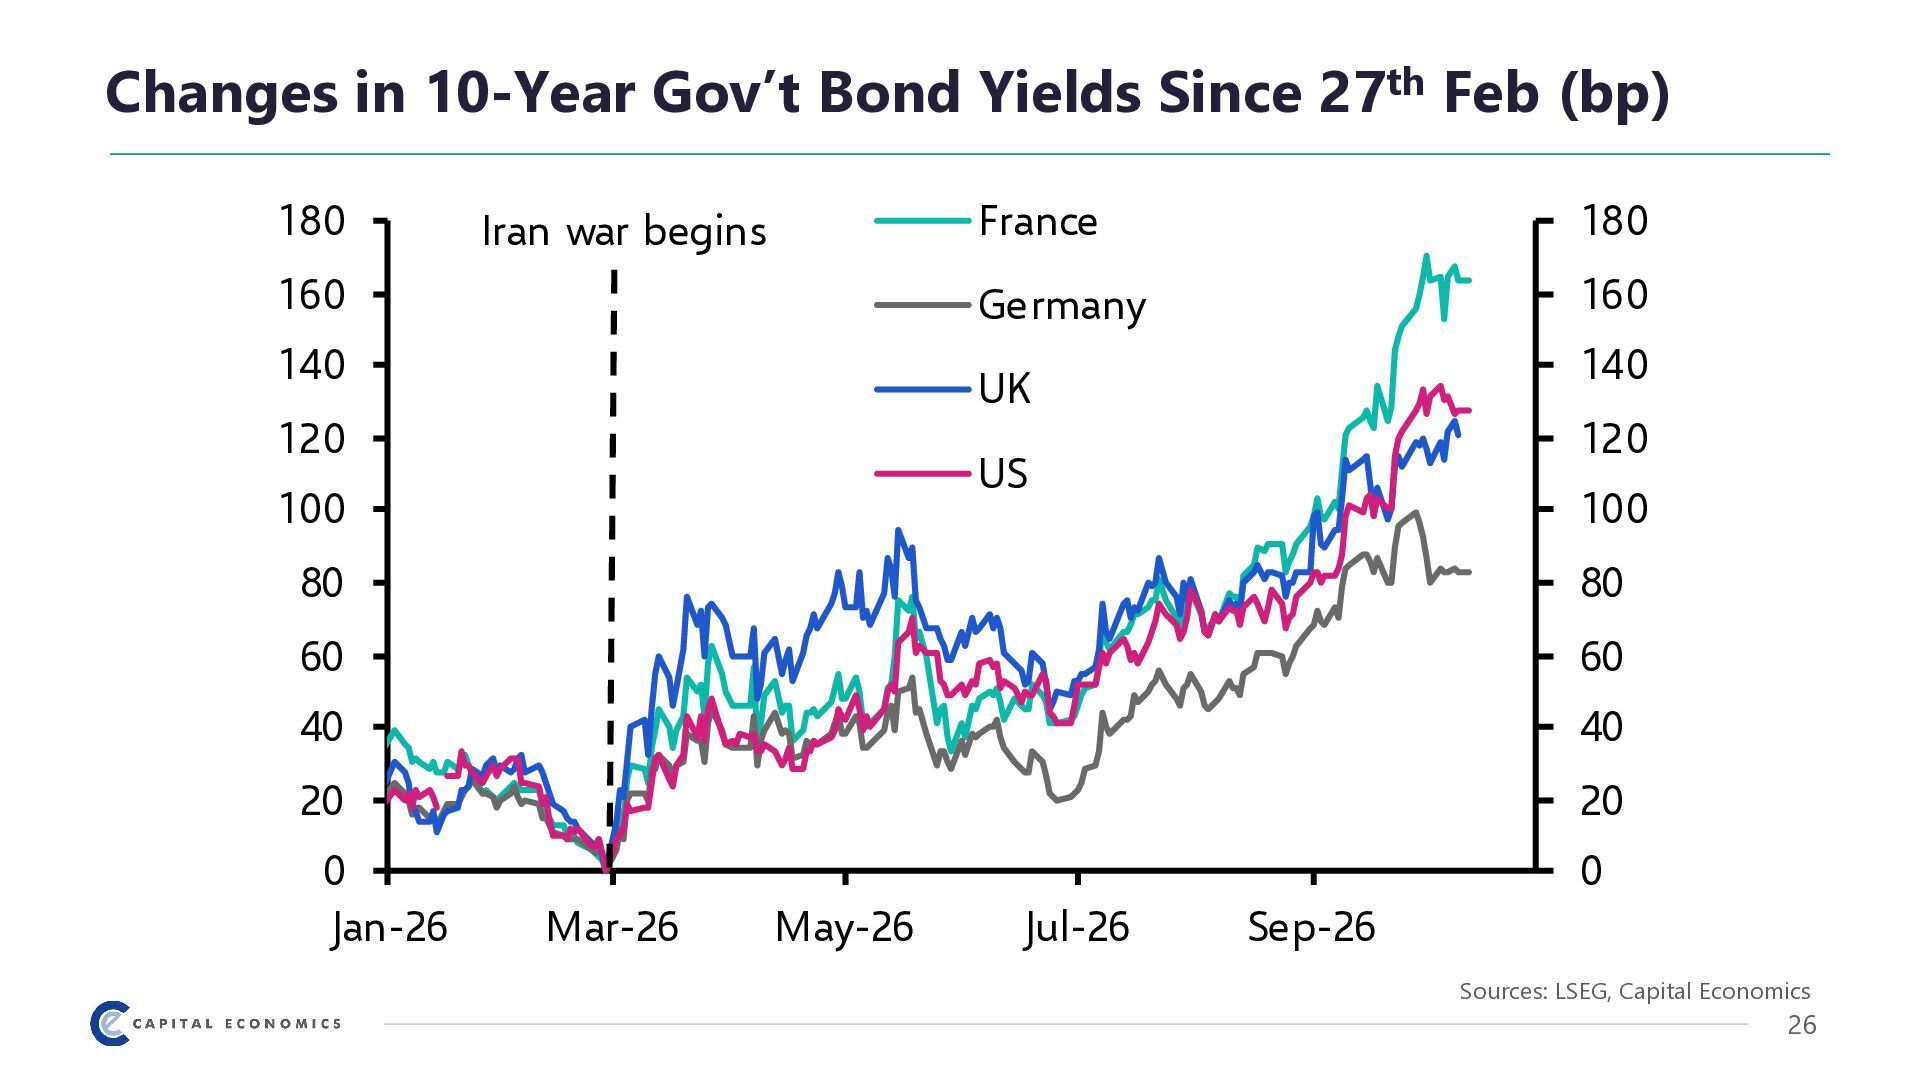
10-year government bond yields: high-income OECD countries Source: RF analysis of OECD, Long-term interest rates; Bank of England, Yield Curves. @resfoundation 9
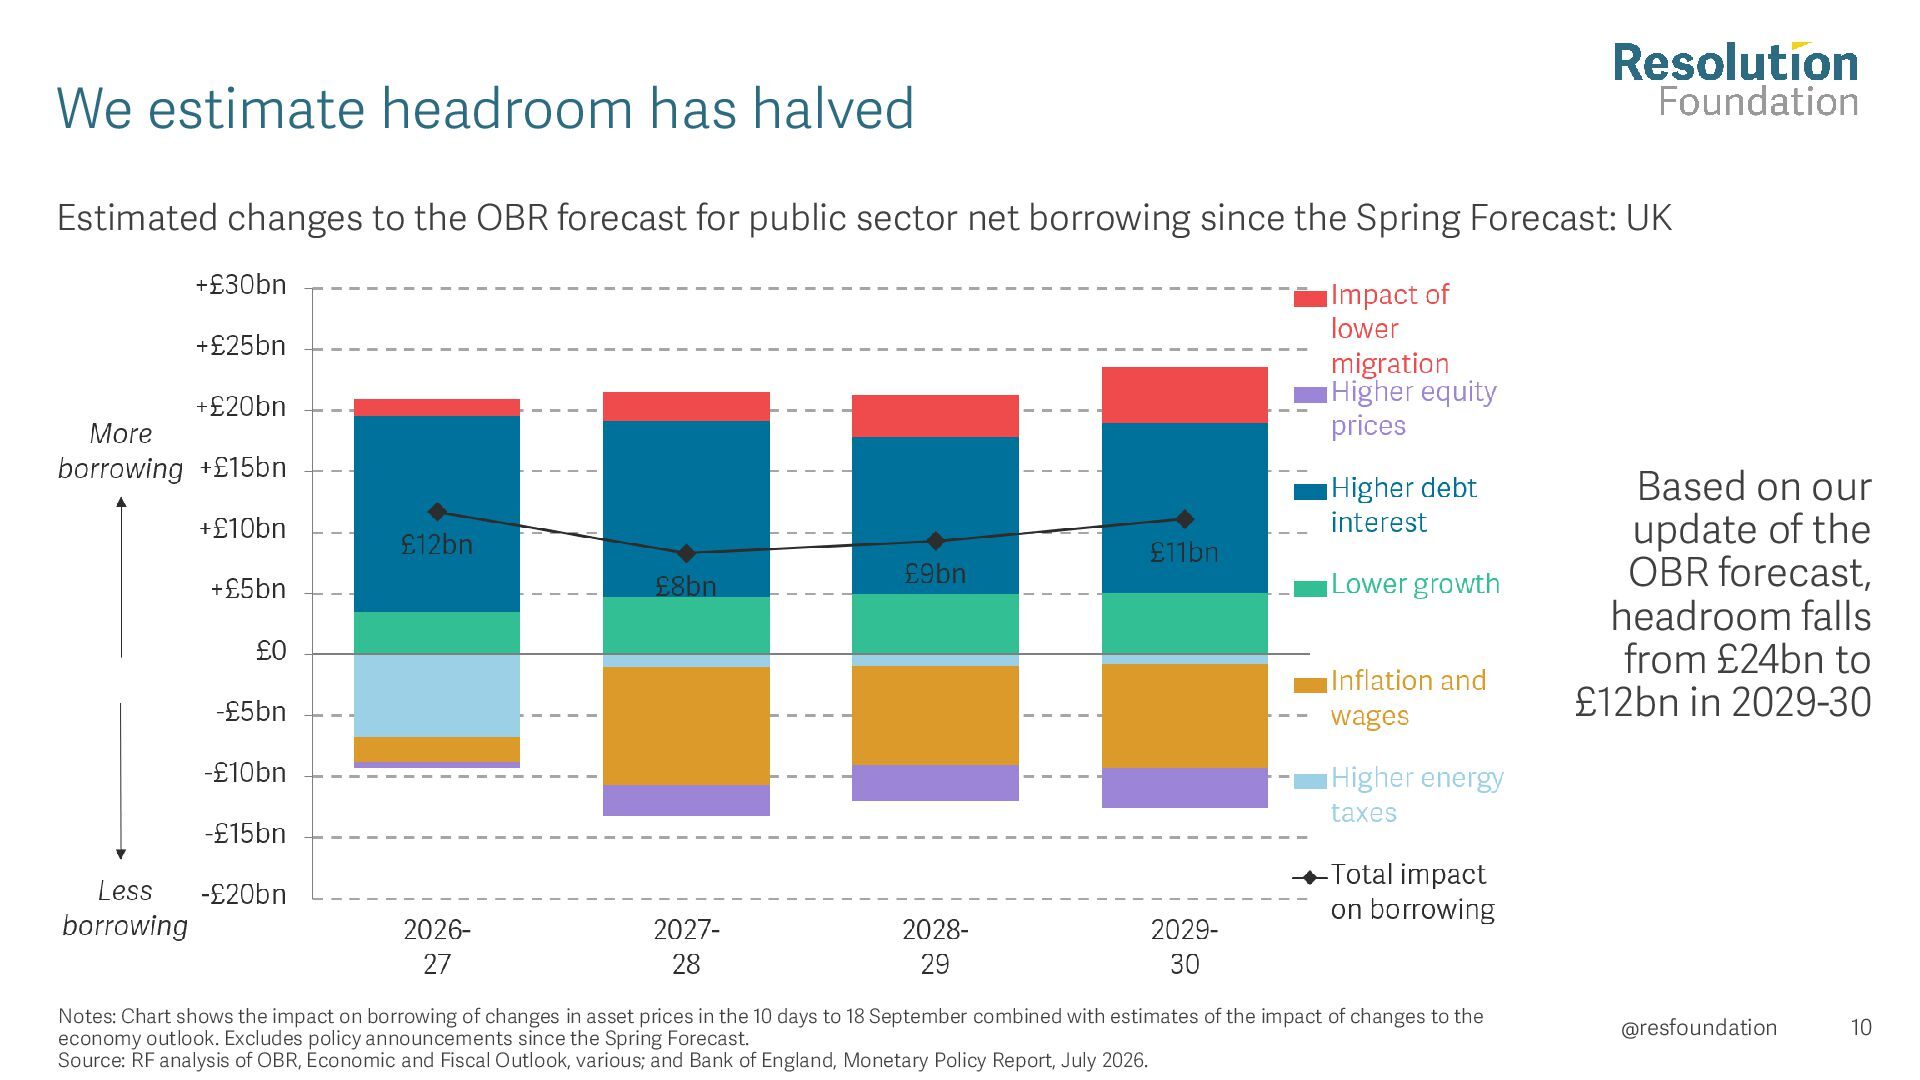
forecast for public sector net borrowing since the Spring Forecast: UK Based on our update of the OBR forecast, headroom falls from £24bn to £12bn in 2029-30 Notes: Chart shows the impact on borrowing of changes in asset prices in the 10 days to 18 September combined with estimates of the impact of changes to the economy outlook. Excludes policy announcements since the Spring Forecast. Source: RF analysis of OBR, Economic and Fiscal Outlook, various; and Bank of England, Monetary Policy Report, July 2026. @resfoundation 10
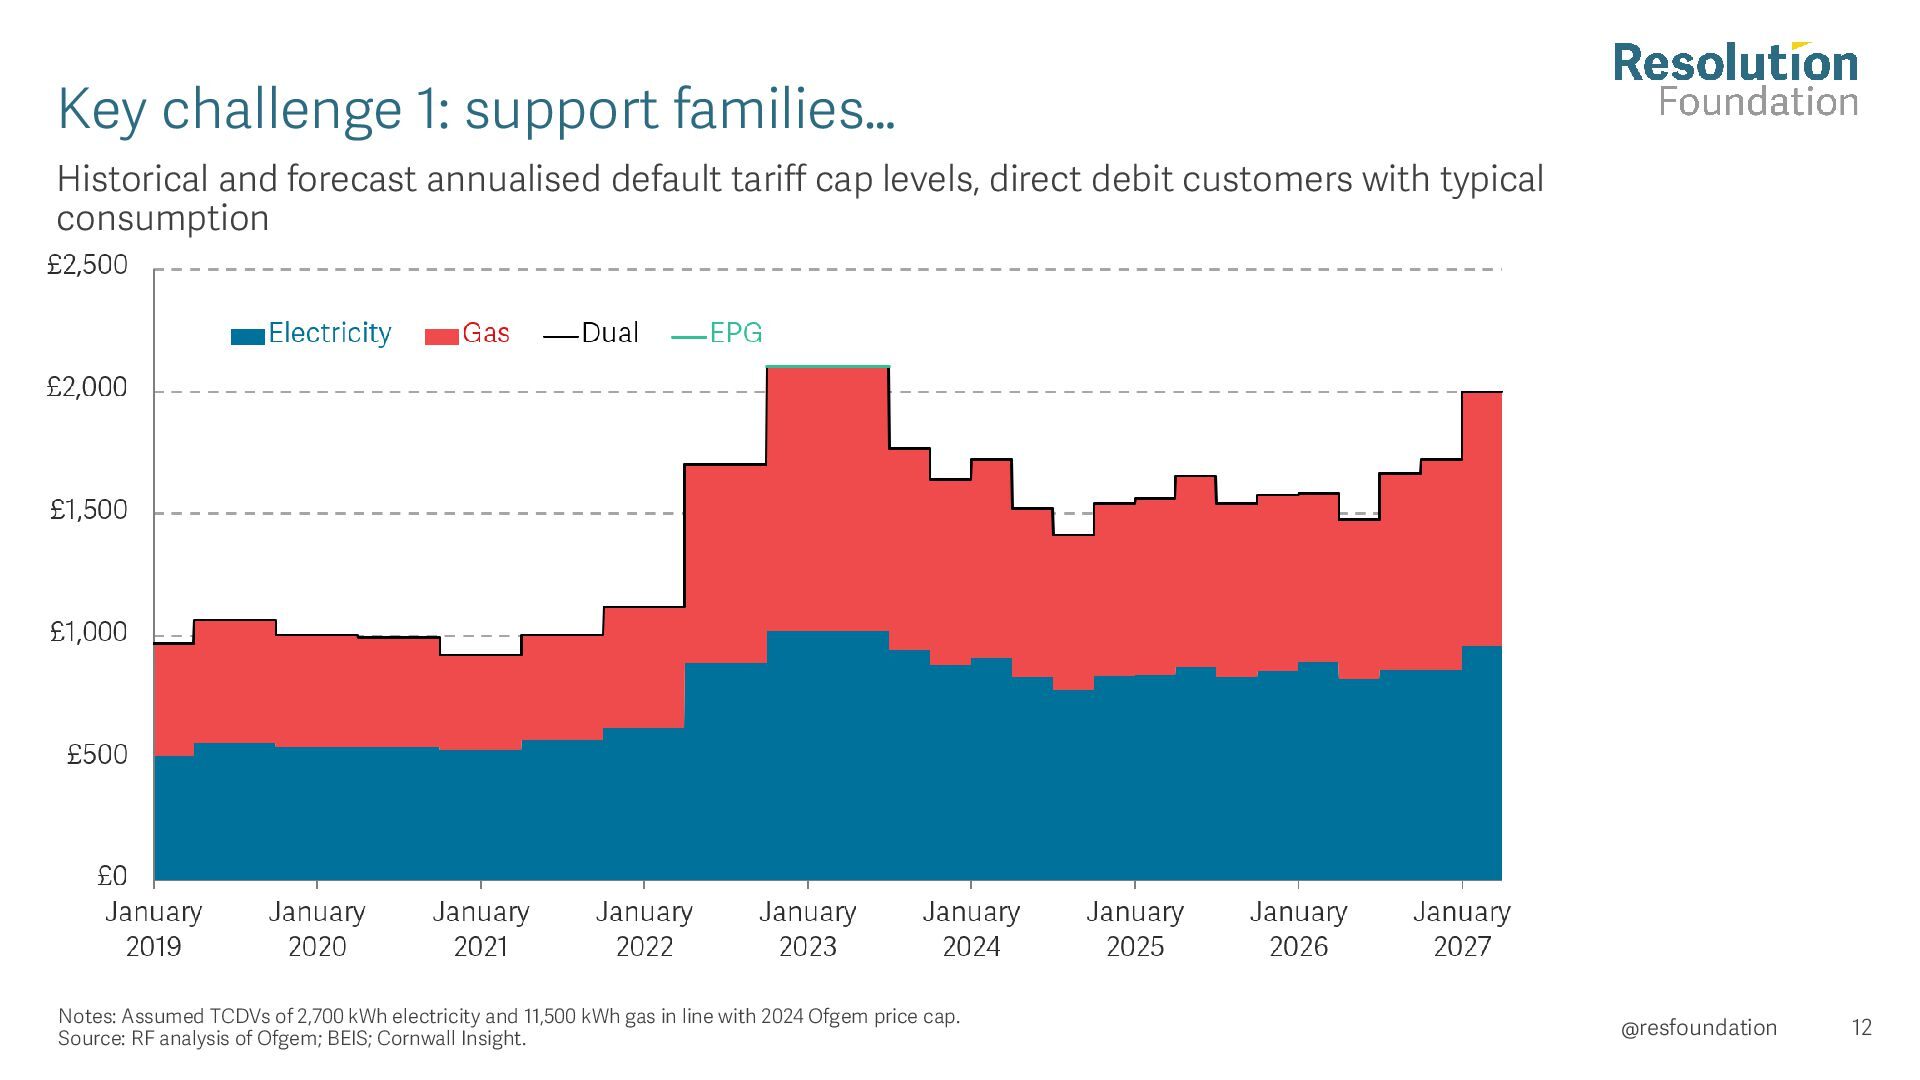
tariff cap levels, direct debit customers with typical consumption Notes: Assumed TCDVs of 2,700 kWh electricity and 11,500 kWh gas in line with 2024 Ofgem price cap. Source: RF analysis of Ofgem; BEIS; Cornwall Insight. @resfoundation 12
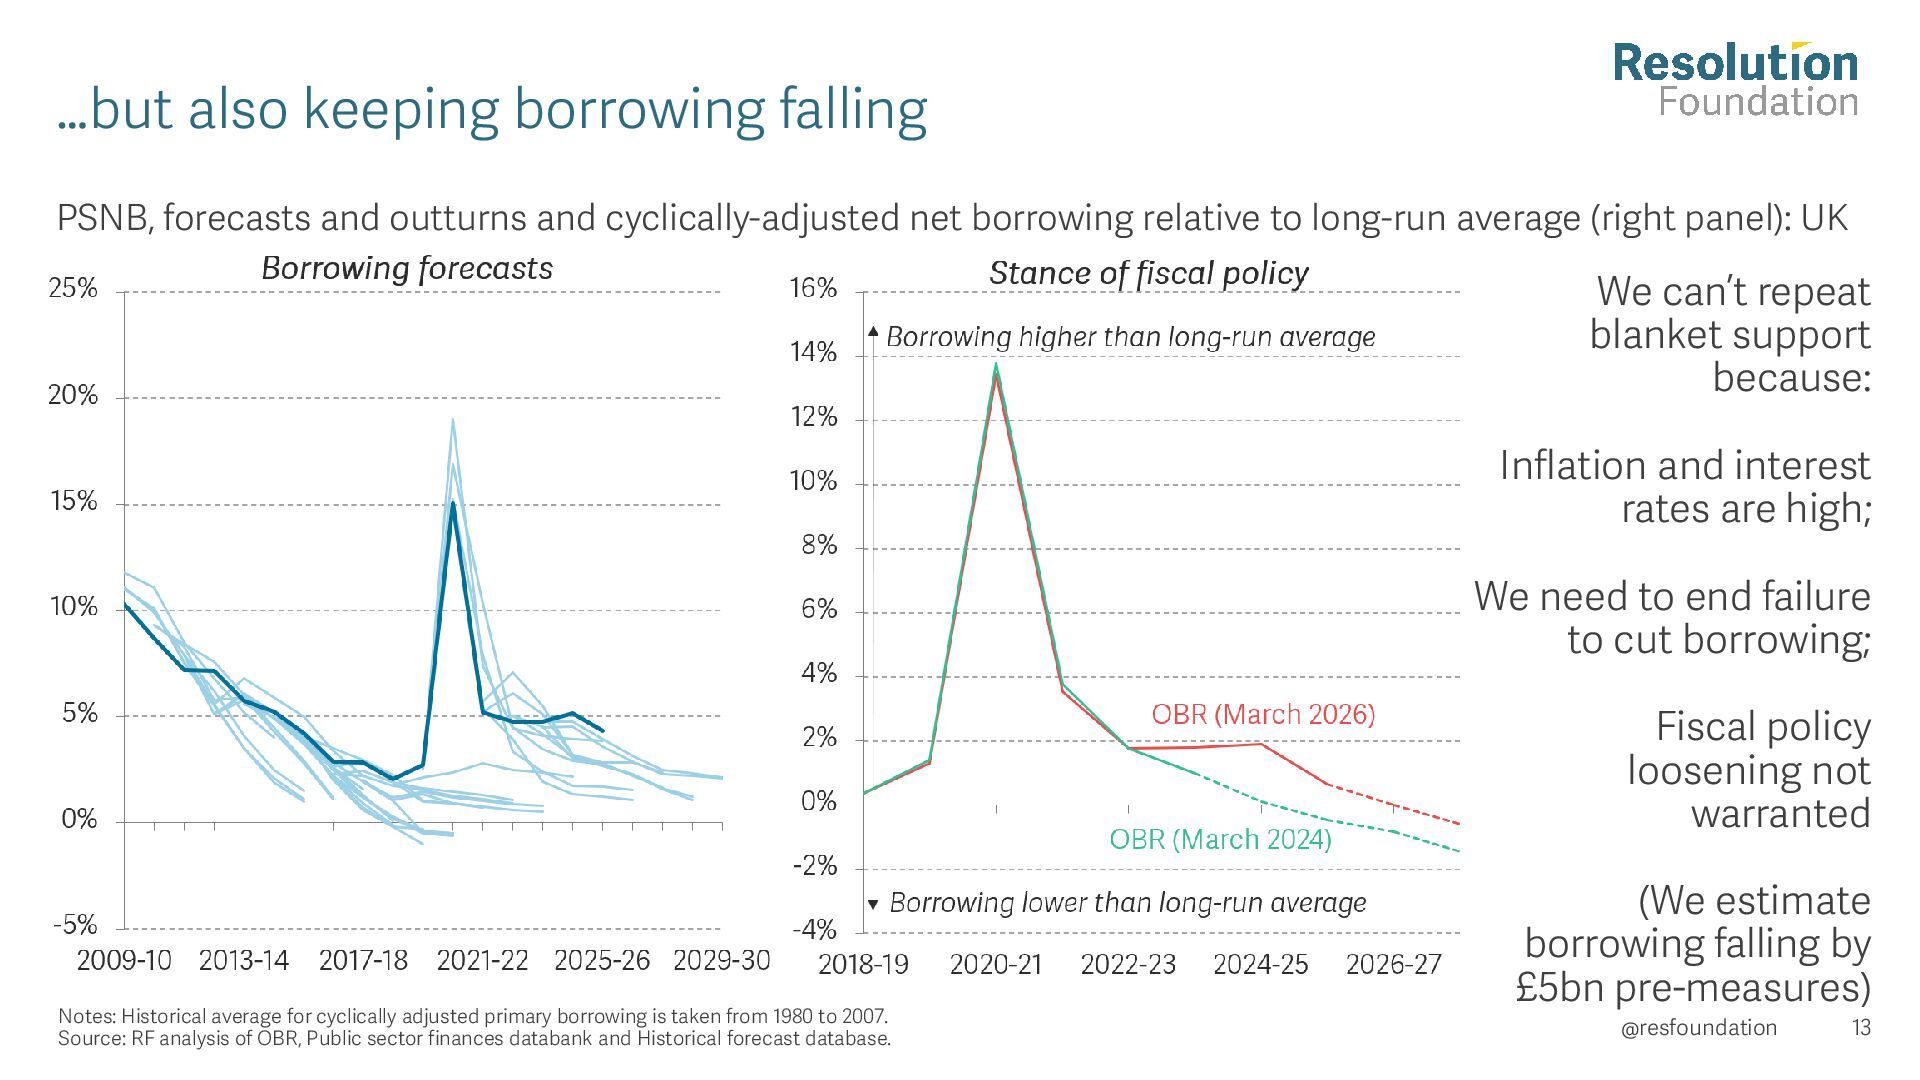
cyclically-adjusted net borrowing relative to long-run average (right panel): UK We can’t repeat blanket support because: Inflation and interest rates are high; We need to end failure to cut borrowing; Fiscal policy loosening not warranted Notes: Historical average for cyclically adjusted primary borrowing is taken from 1980 to 2007. Source: RF analysis of OBR, Public sector finances databank and Historical forecast database. (We estimate borrowing falling by £5bn pre-measures) @resfoundation 13
temporary scheme targeting HHs where no one has an income >£24k • Would extend beyond benefit recipients, save eligible households £175 on average, and cost £2 billion overall • Extending Warm Homes Discount is a second best @resfoundation 14
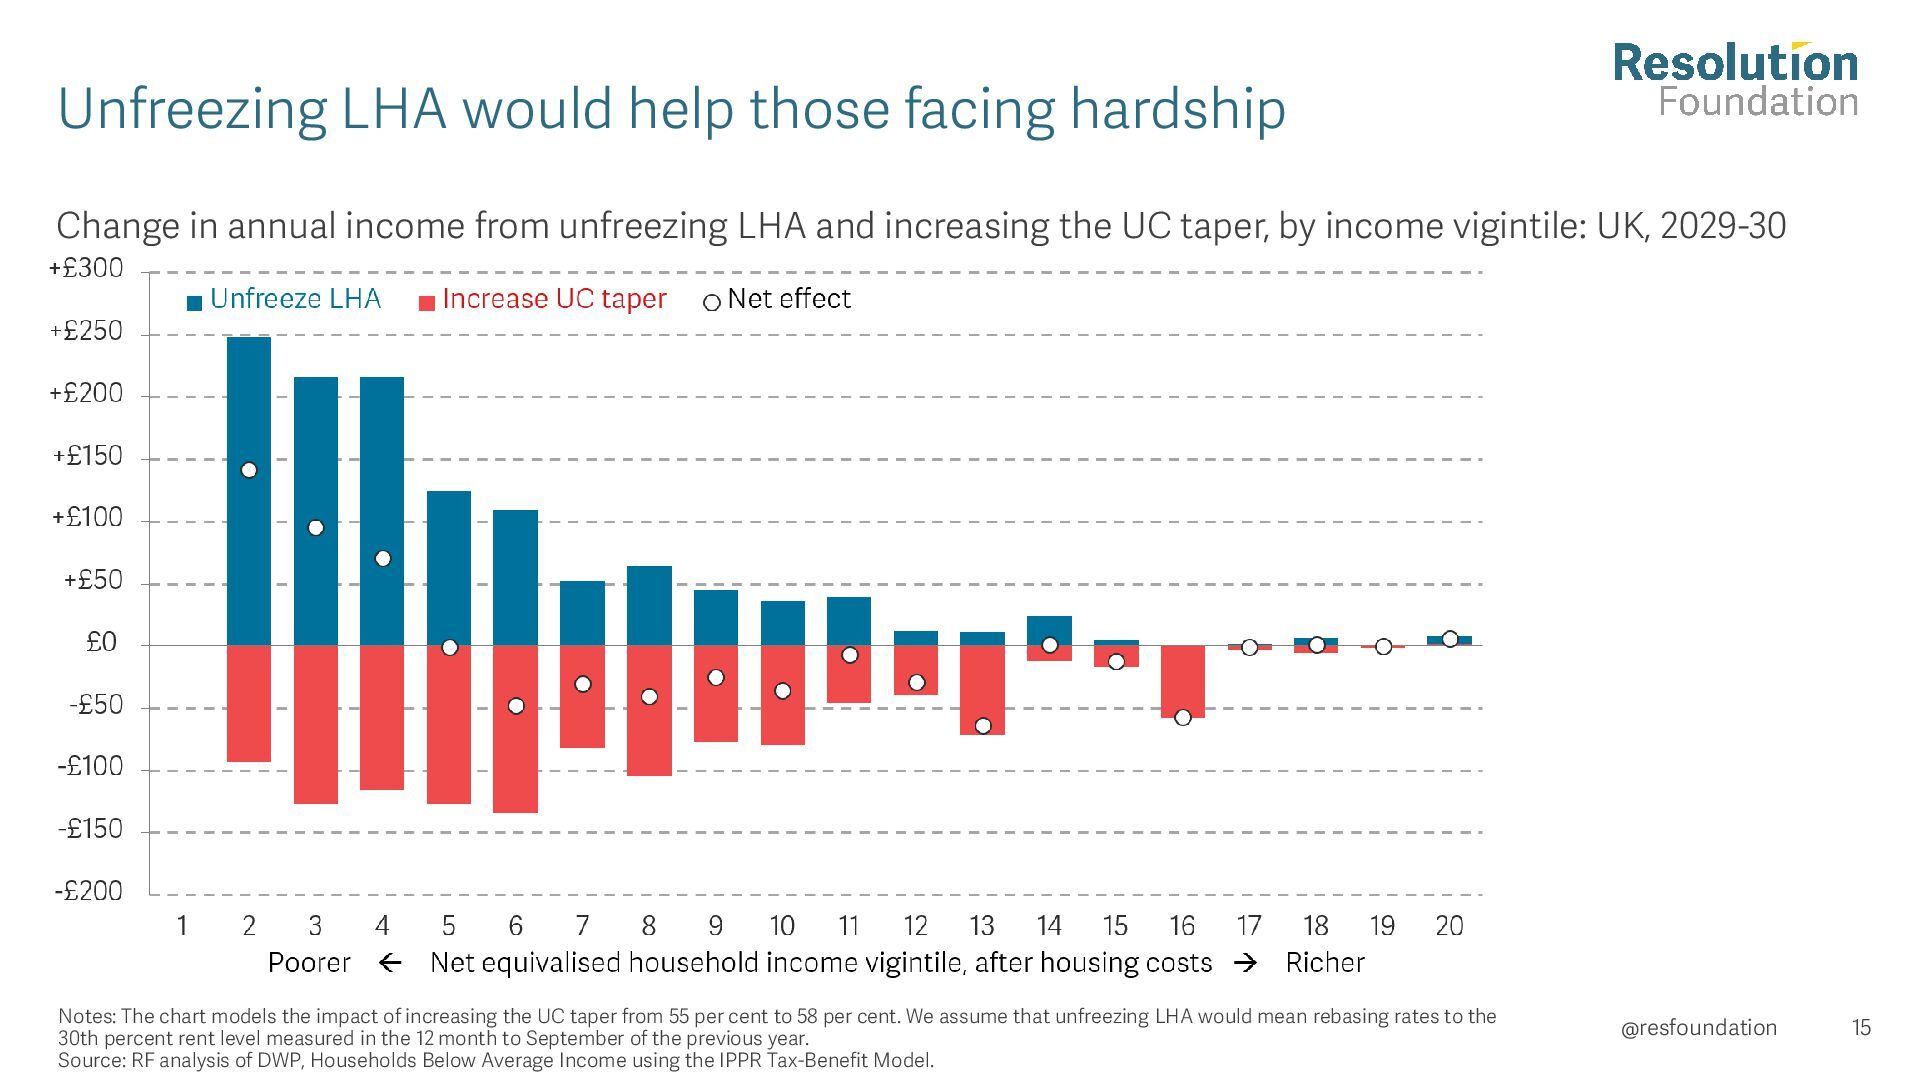
income from unfreezing LHA and increasing the UC taper, by income vigintile: UK, 2029-30 Notes: The chart models the impact of increasing the UC taper from 55 per cent to 58 per cent. We assume that unfreezing LHA would mean rebasing rates to the 30th percent rent level measured in the 12 month to September of the previous year. Source: RF analysis of DWP, Households Below Average Income using the IPPR Tax-Benefit Model. @resfoundation 15
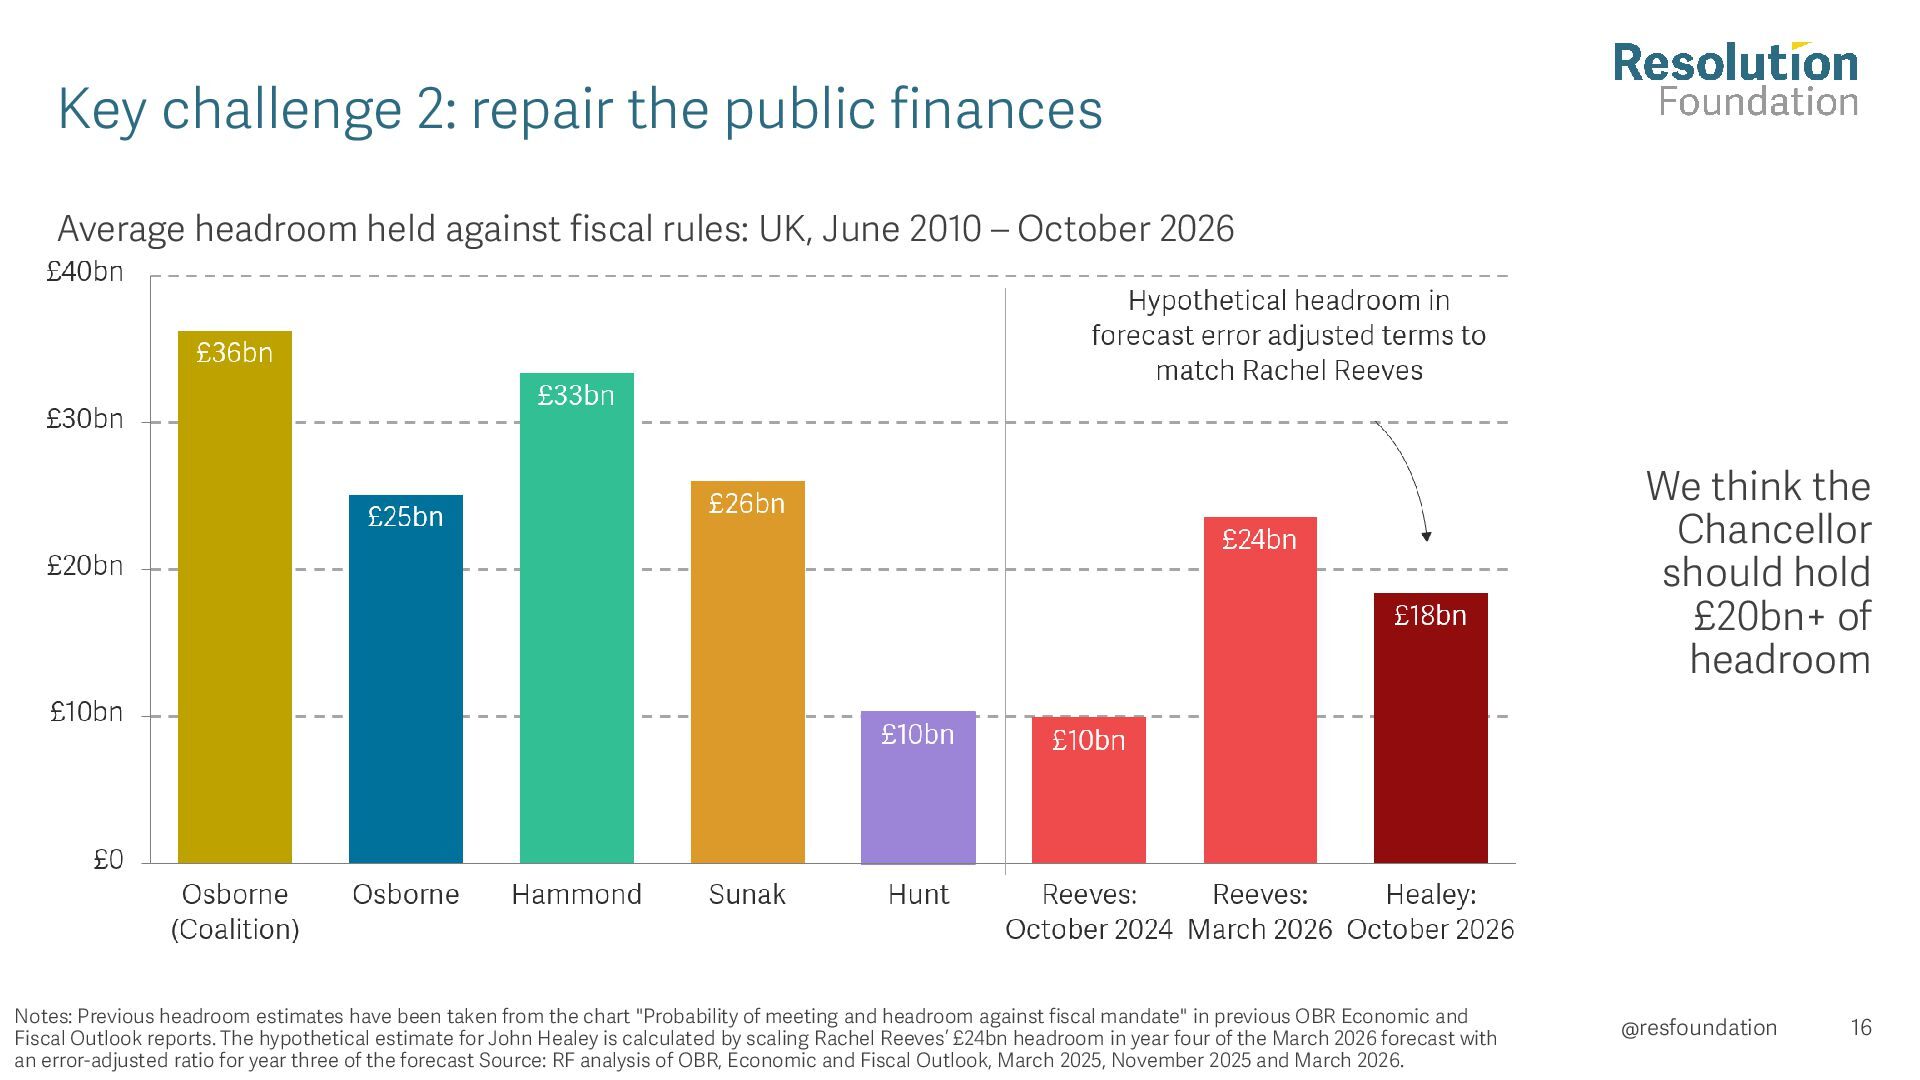
against fiscal rules: UK, June 2010 – October 2026 We think the Chancellor should hold £20bn+ of headroom Notes: Previous headroom estimates have been taken from the chart "Probability of meeting and headroom against fiscal mandate" in previous OBR Economic and Fiscal Outlook reports. The hypothetical estimate for John Healey is calculated by scaling Rachel Reeves’ £24bn headroom in year four of the March 2026 forecast with an error-adjusted ratio for year three of the forecast Source: RF analysis of OBR, Economic and Fiscal Outlook, March 2025, November 2025 and March 2026. @resfoundation 16
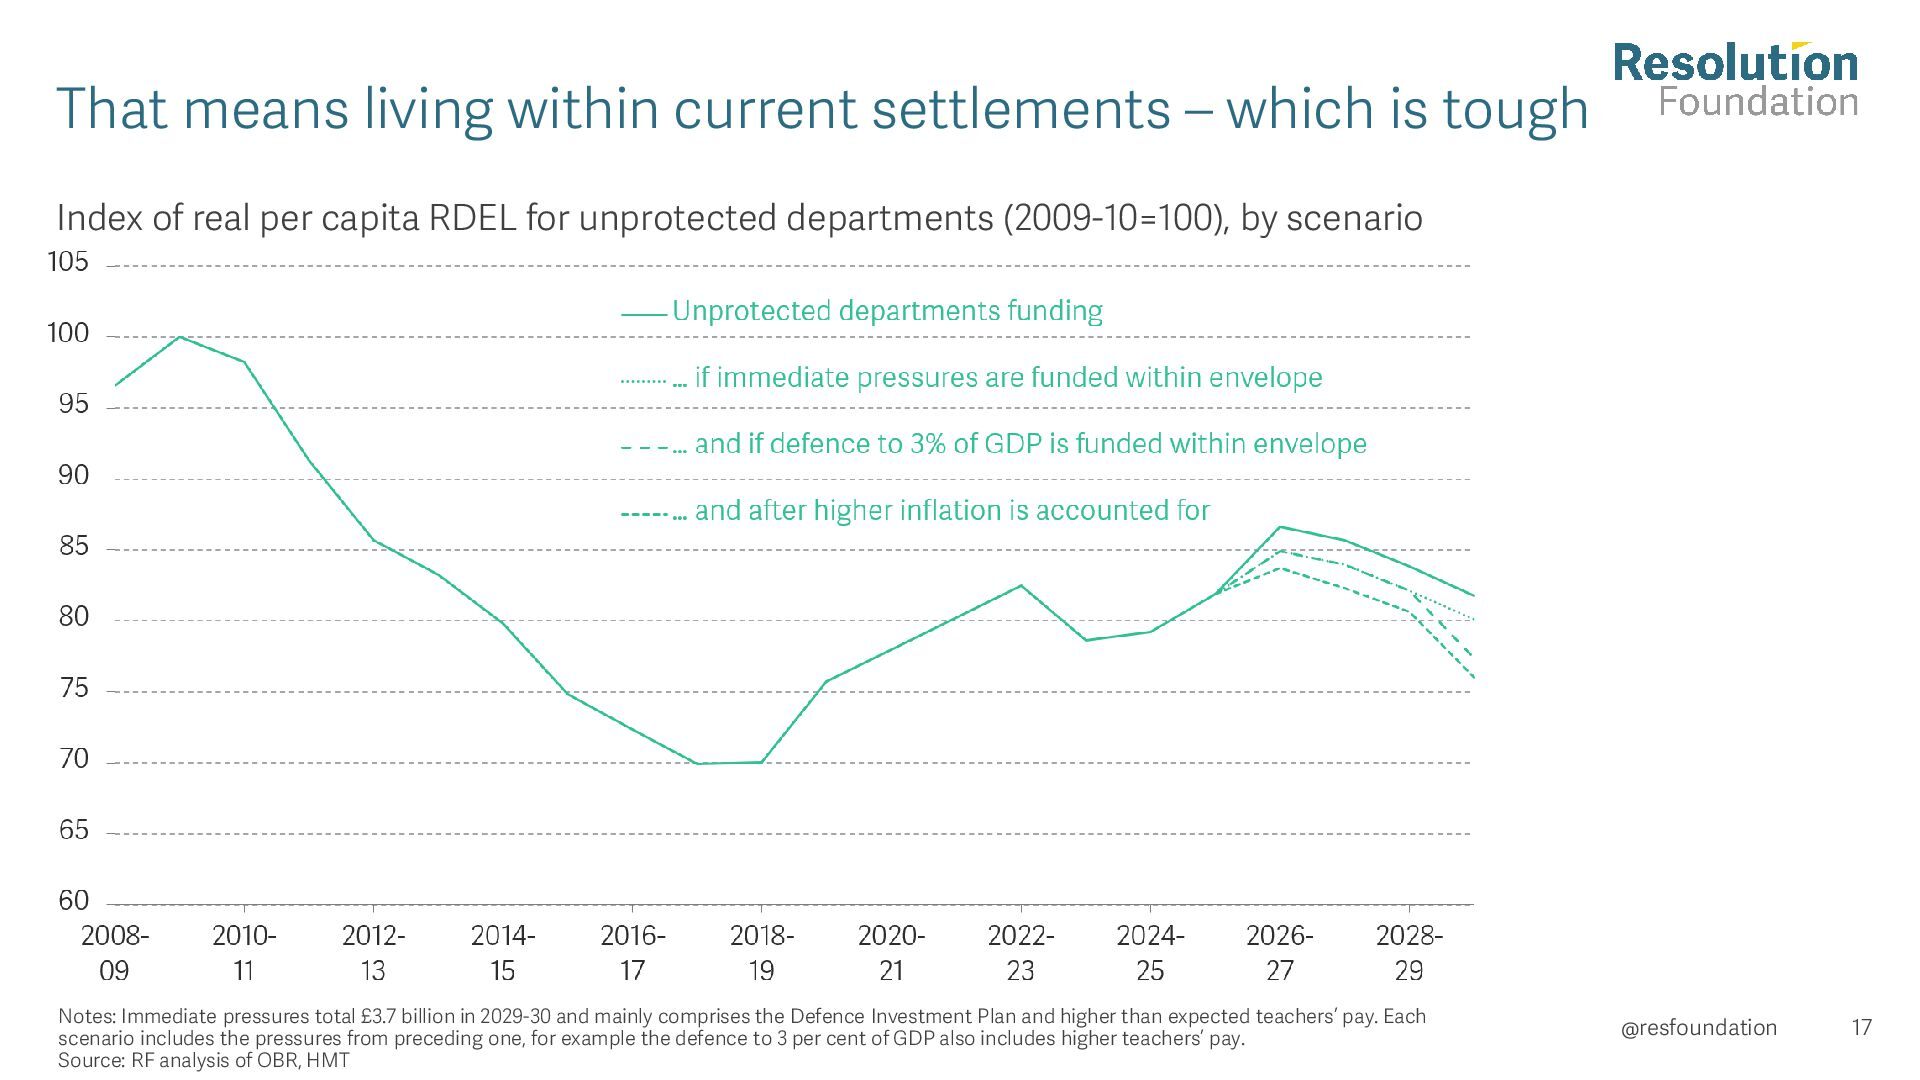
Index of real per capita RDEL for unprotected departments (2009-10=100), by scenario Notes: Immediate pressures total £3.7 billion in 2029-30 and mainly comprises the Defence Investment Plan and higher than expected teachers’ pay. Each scenario includes the pressures from preceding one, for example the defence to 3 per cent of GDP also includes higher teachers’ pay. Source: RF analysis of OBR, HMT @resfoundation 17
in mansion tax has been rumoured… • ….but we would: close CGT loopholes, apply NI to partnership income, reduce VAT threshold, and increase dividend tax, raising over £9bn • Tax ‘switch’ could help raise money to fund defence spending @resfoundation 18
our problems, rather than ducking them • Two challenges: providing cost of living support and repairing the public finances • Met with a three-part strategy: • Providing targeted support to the families facing hardship (while also keeping borrowing falling) • Setting out tax rises which repair the public finances and improve the system • Keeping a tight grip on spending (and, ideally, set out SR envelope) 19
for the Budget? Dharshini David, Deputy economics editor at the BBC Jennifer McKeown, Chief Global Economist at Capital Economics James Smith, Chief Economist at the Resolution Foundation Chair: Ruth Curtice, Chief Executive of the Resolution Foundation Wifi 2QAG_Guest Welcome_Guests @resfoundation #HittingBuffers October 26
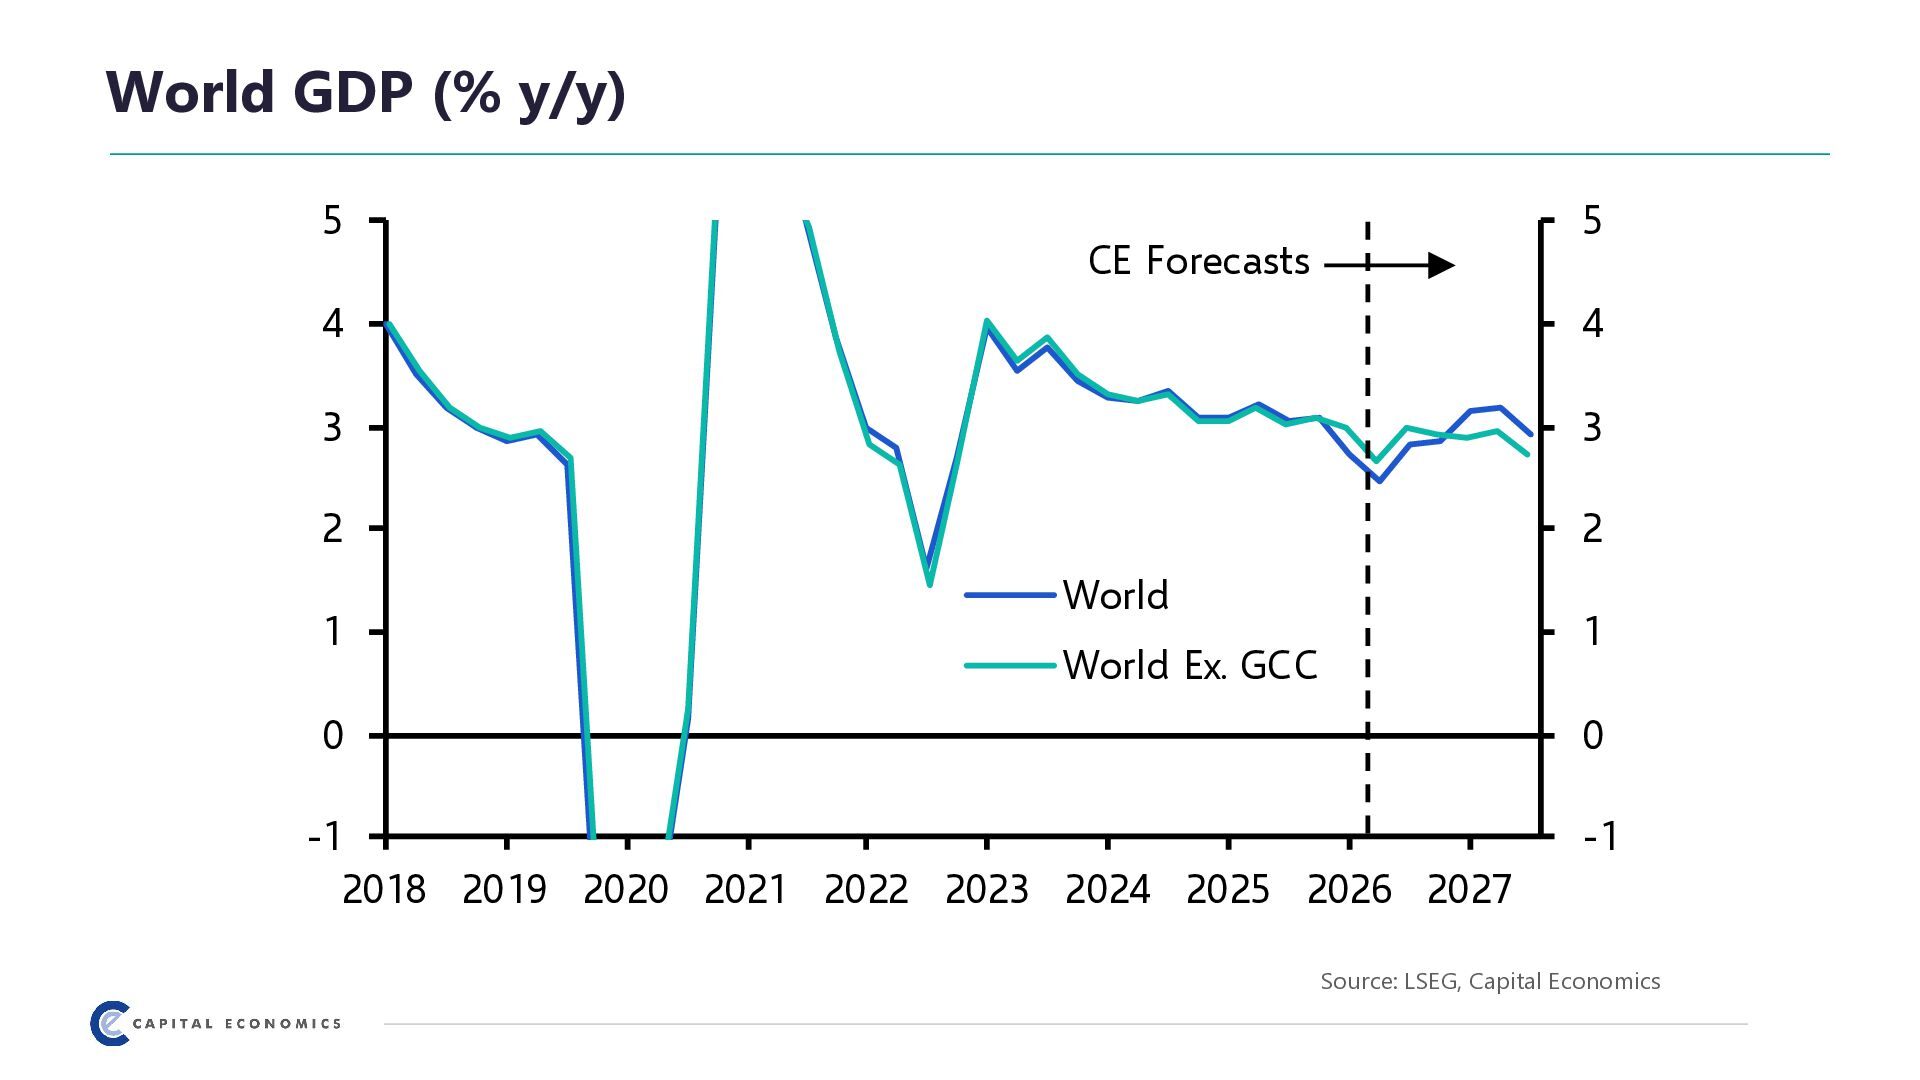
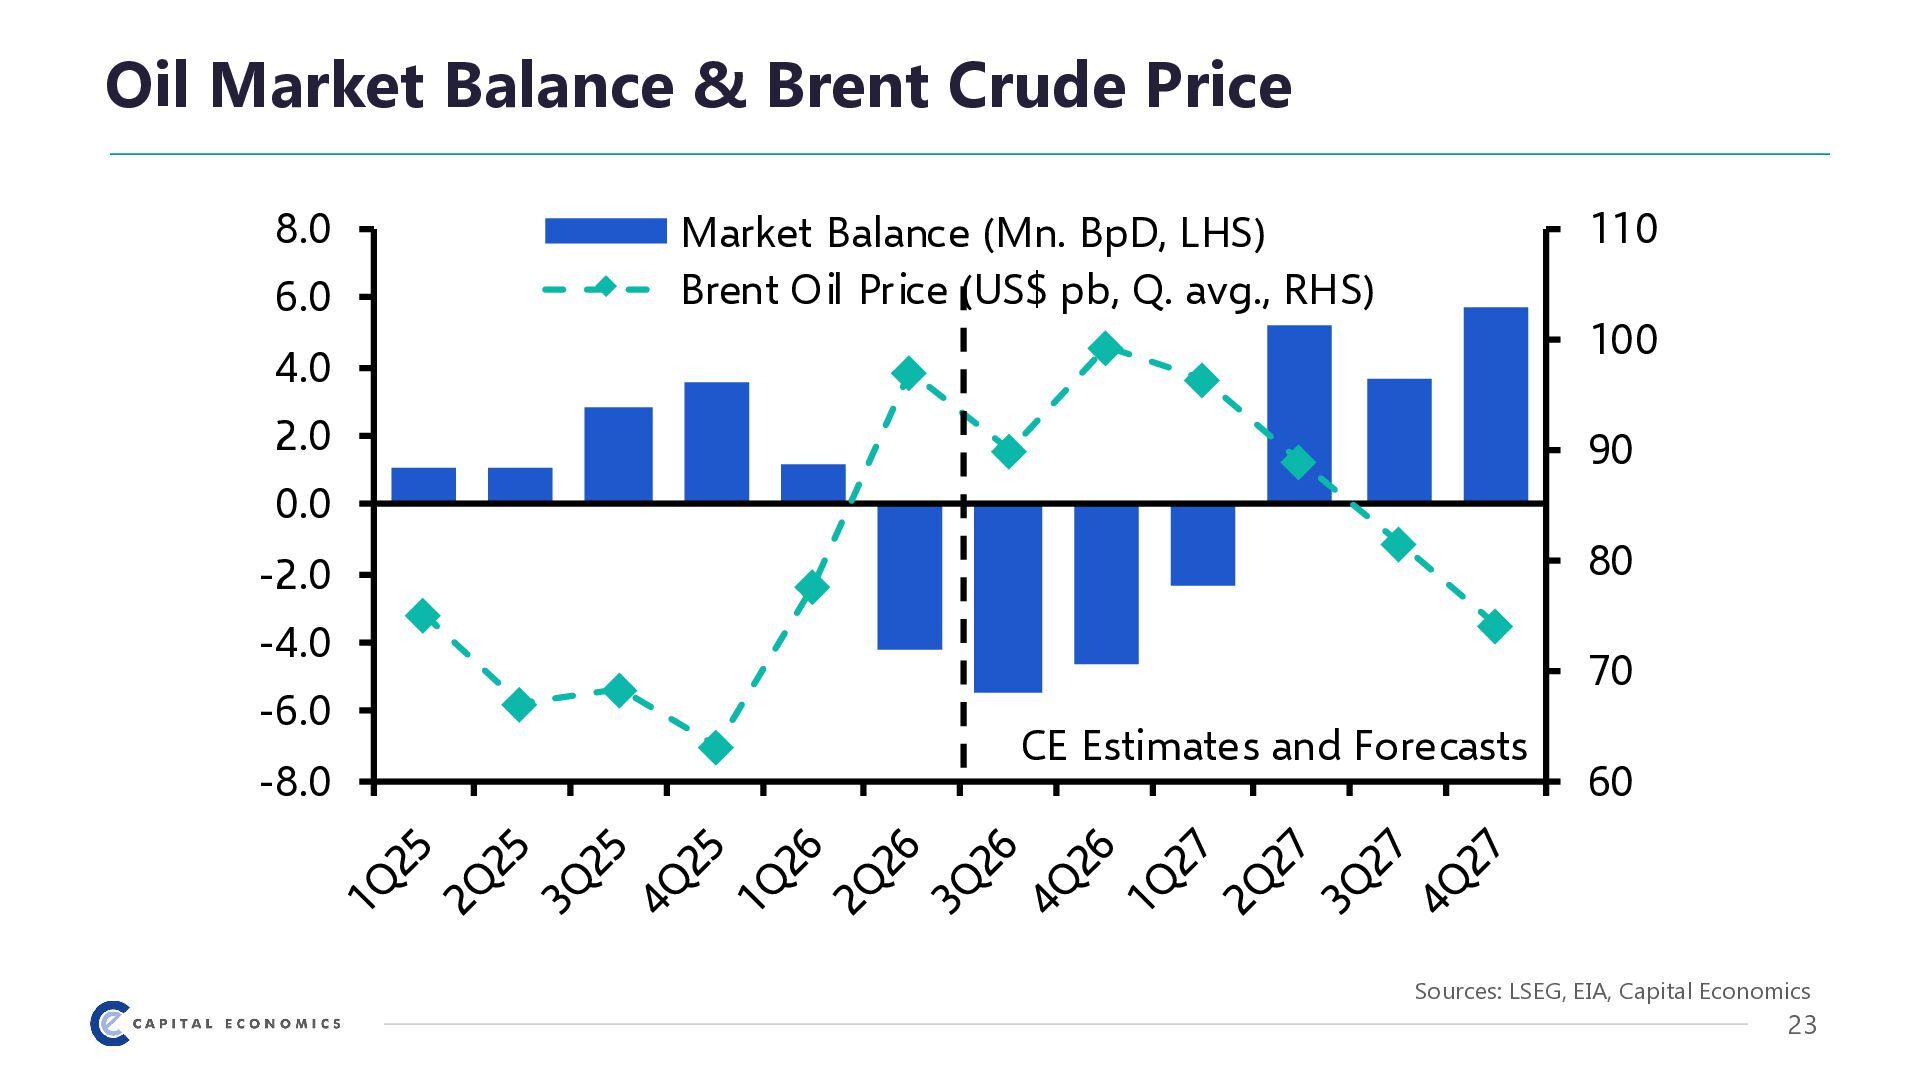
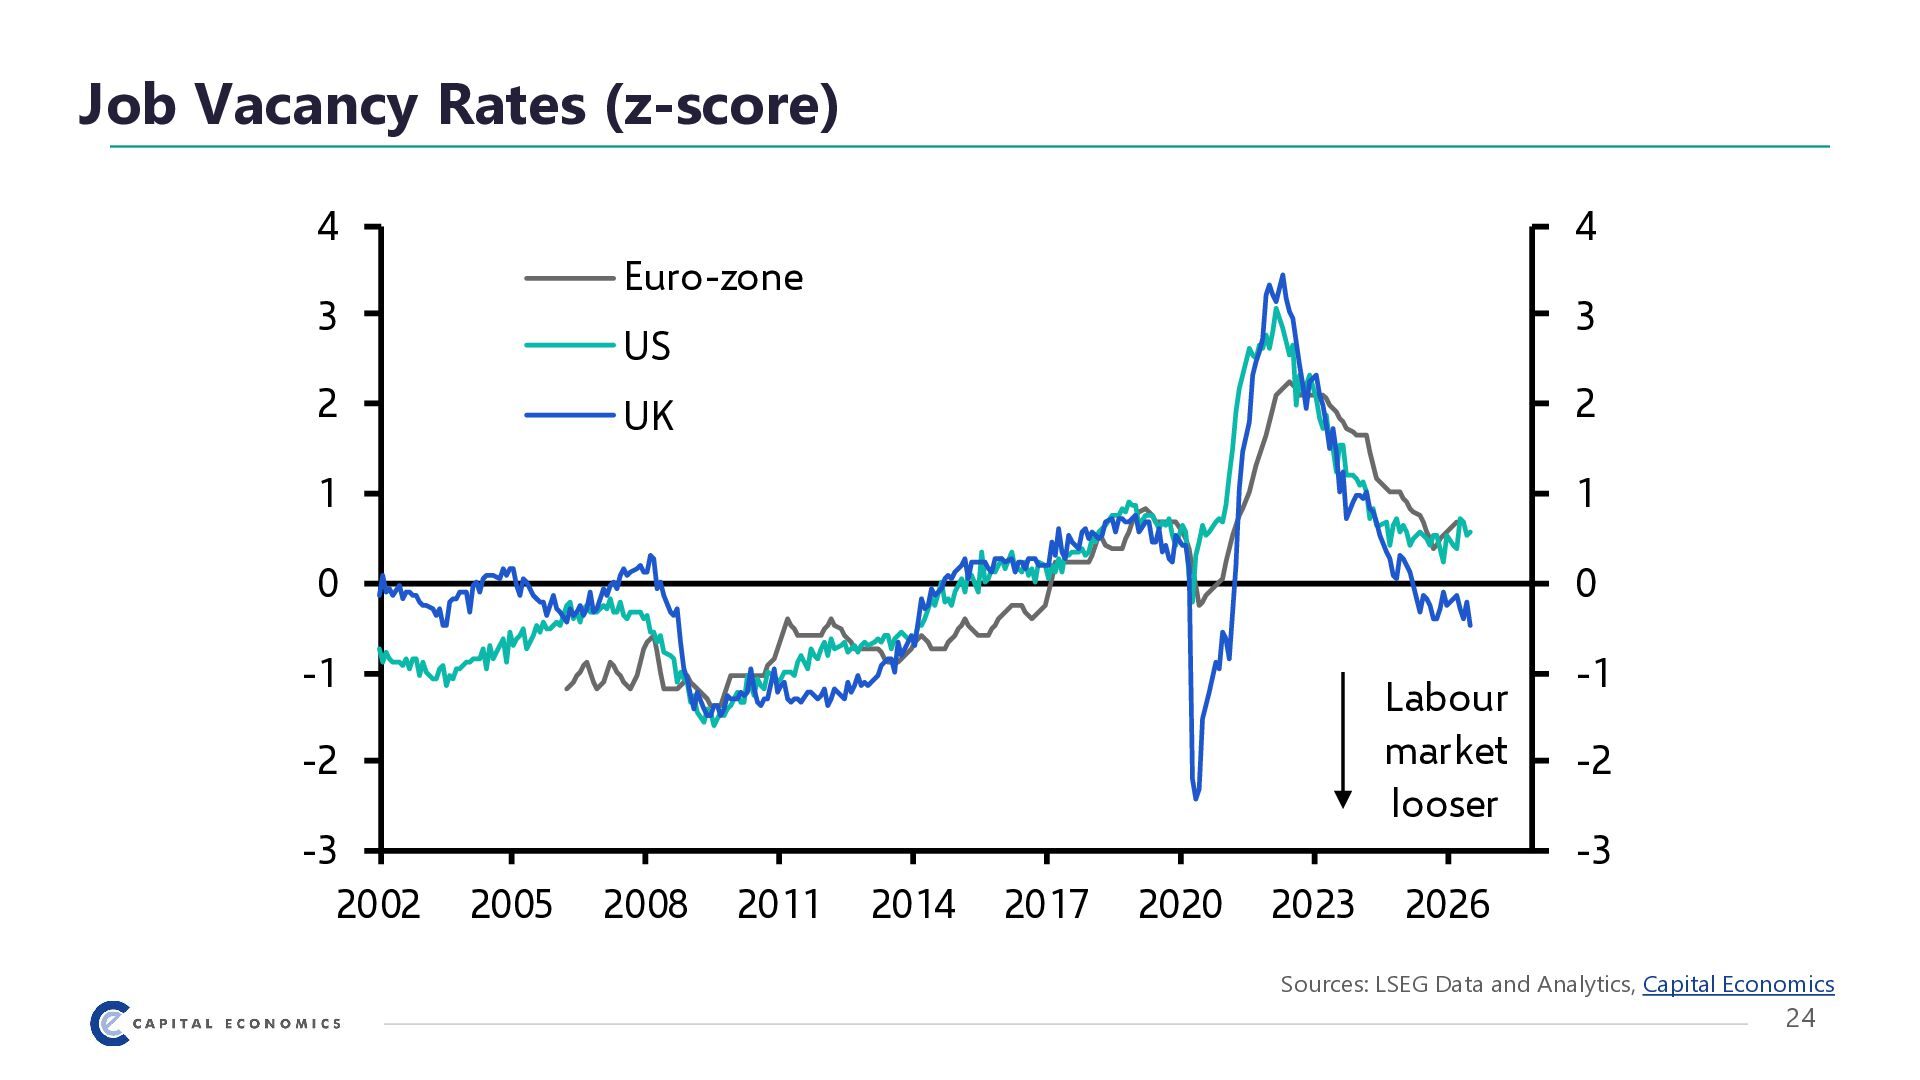
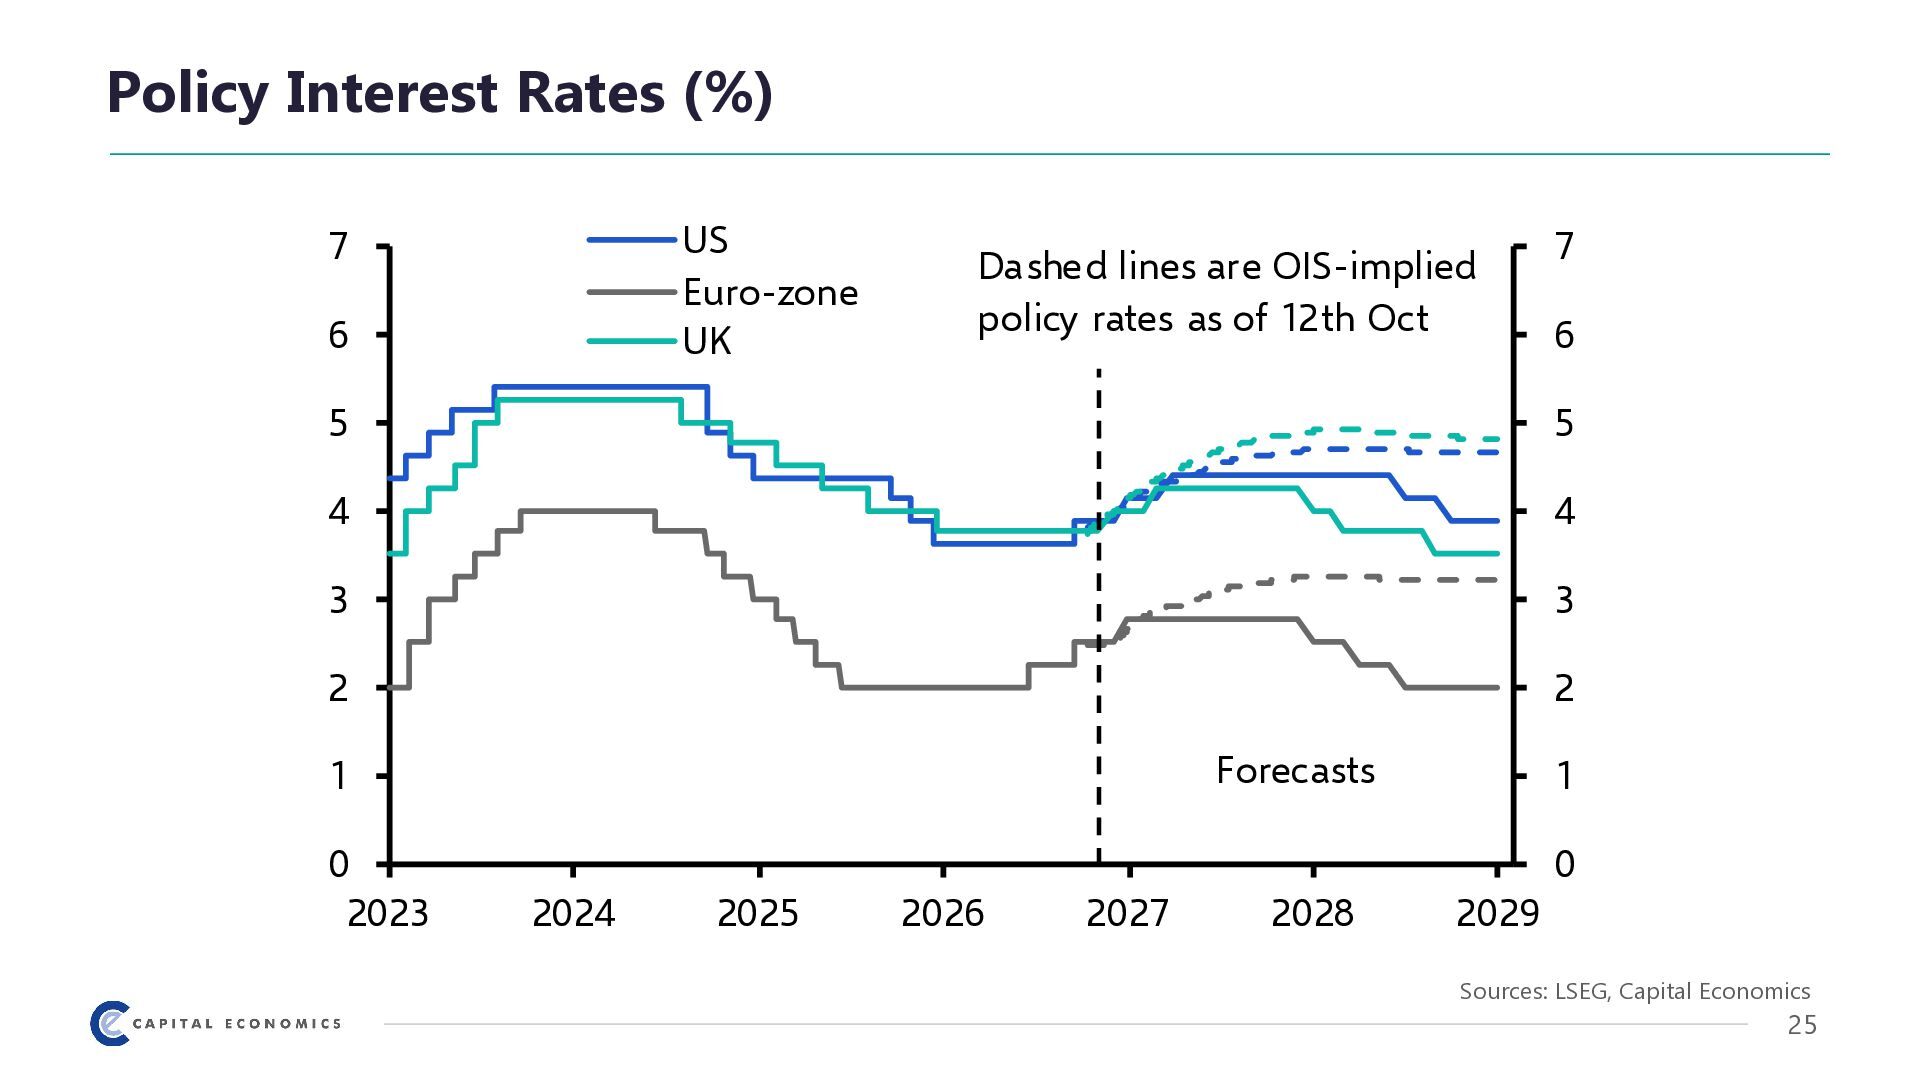
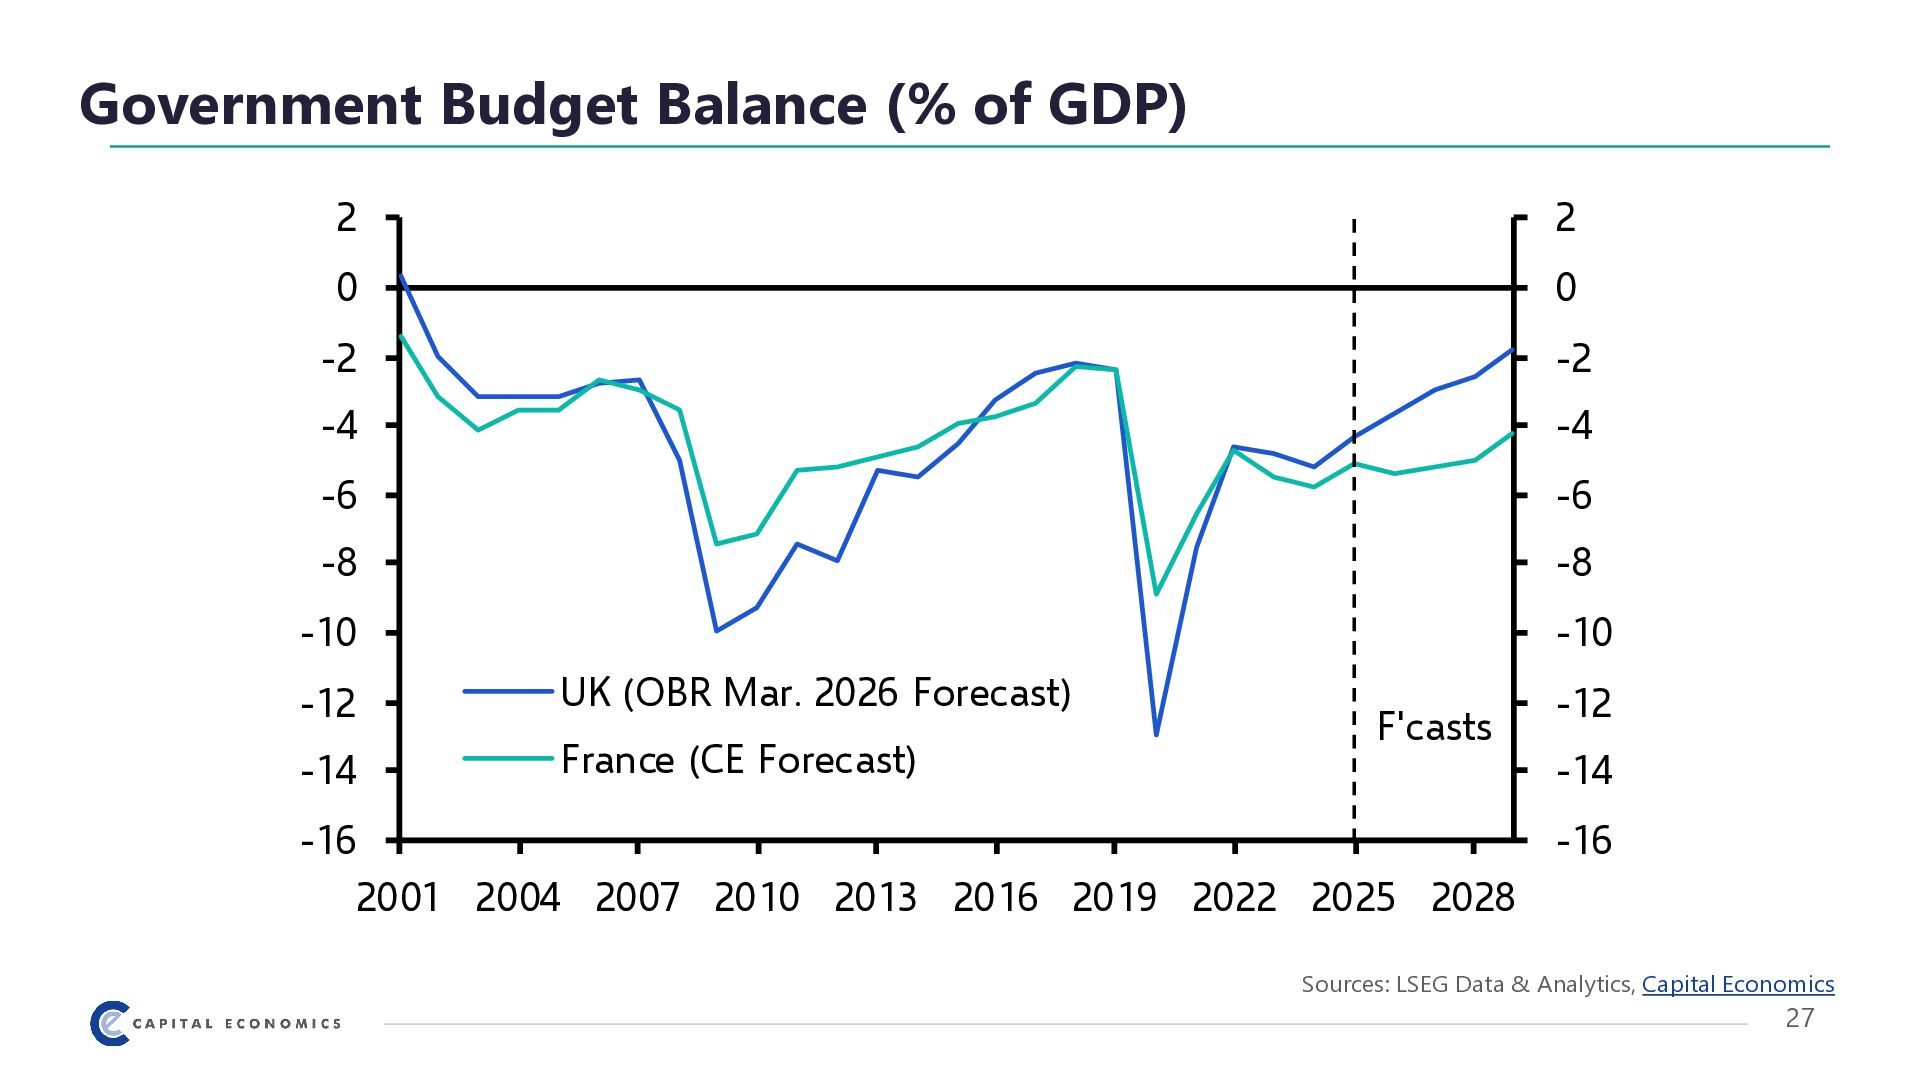
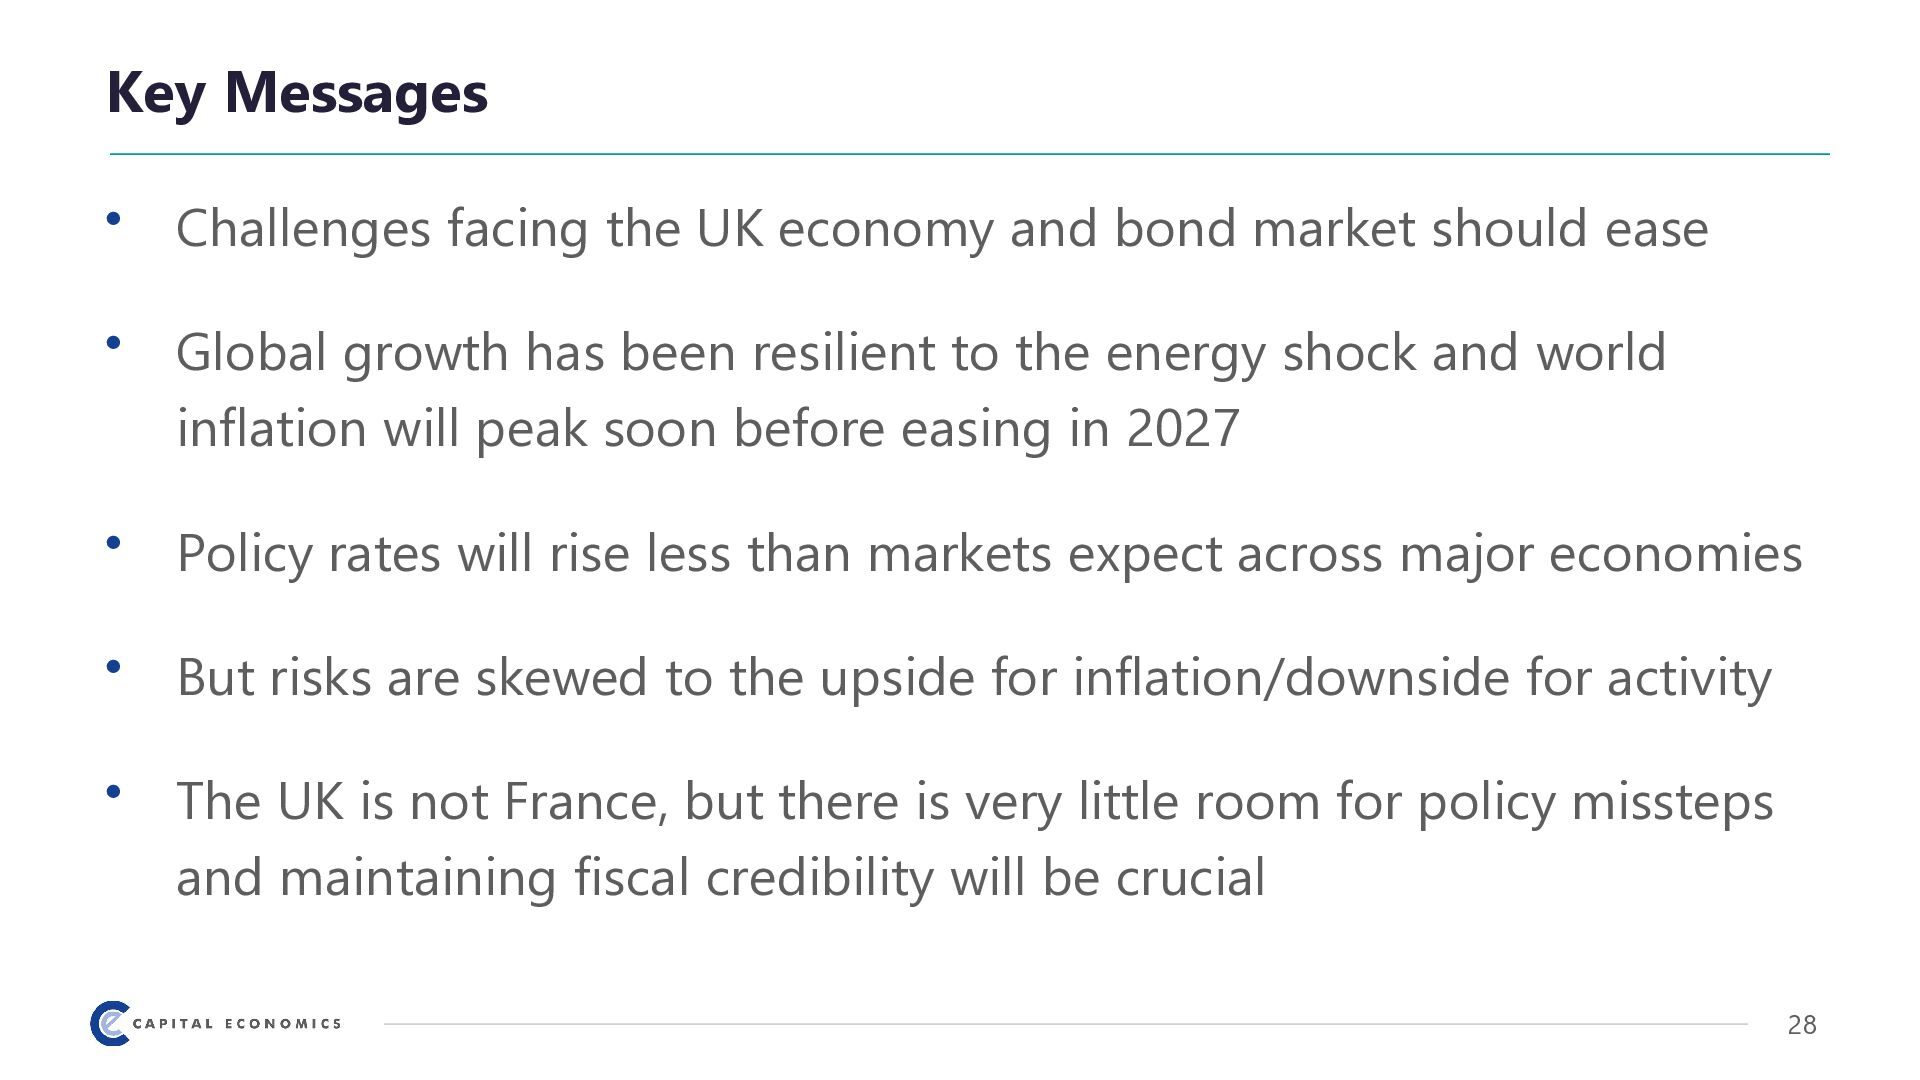
market should ease • Global growth has been resilient to the energy shock and world inflation will peak soon before easing in 2027 • Policy rates will rise less than markets expect across major economies • But risks are skewed to the upside for inflation/downside for activity • The UK is not France, but there is very little room for policy missteps and maintaining fiscal credibility will be crucial 28
5th Floor, 100 Victoria Street Cardinal Place London SW1E 5JL Capital Economics (N.A.) Ltd Suite 600, 77 Bloor Street West Toronto, ON M5S 1M2 Telephone: +1 416 413 0428 Telephone: +44 (0)20 7823 5000 Capital Economics Ltd. is registered in England, Registration No. 2484735. VAT No. GB 198 2919 50. The North American office is a branch of Capital Economics (N.A.) Ltd, a wholly-owned subsidiary of Capital Economics Ltd. Registered in England, Registration No. 6190831. Registered in Canada, Registration No. BN 851886358. ASIA – SINGAPORE Capital Economics (Asia) Pte. Ltd 05-01/02, CapitaGreen 138 Market Street Singapore, 048946 Telephone: +65 6595 5190 The Asian office, Capital Economics (Asia) Pte. Ltd, is a wholly-owned subsidiary of Capital Economics Ltd. Registered in Singapore, Registration No. 200909395K. Subscription enquiries: [email protected] • Consultancy: [email protected] Recruitment enquiries: [email protected] • General enquiries: [email protected] Disclaimer: While every effort has been made to ensure that the data quoted and used for the research behind this document is reliable, there is no guarantee that it is correct, and Capital Economics Limited and its subsidiaries can accept no liability whatsoever in respect of any errors or omissions. This document is a piece of economic research and is not intended to constitute investment advice, nor to solicit dealing in securities or investments.
for the Budget? Dharshini David, Deputy economics editor at the BBC Jennifer McKeown, Chief Global Economist at Capital Economics James Smith, Chief Economist at the Resolution Foundation Chair: Ruth Curtice, Chief Executive of the Resolution Foundation Wifi 2QAG_Guest Welcome_Guests @resfoundation #HittingBuffers October 26


 beale
 ept
 yukako_nakano
 ayaniwa
 wataruuuuu
 takehaya
 youten622
 hariby
 monochromegane
 shunk031
 satai
 murakawatakuya
 ryomasumura
 marcelosomers
 swwweet
 morganepeng
 bcantrill
 inesmontani
 akosma
 jct
 frankvandijk
 holman
 katiecoart
 gurzu