Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Book-keeping

Avatar for Dr. Bharath V Dr. Bharath V
September 11, 2026

 Book-keeping

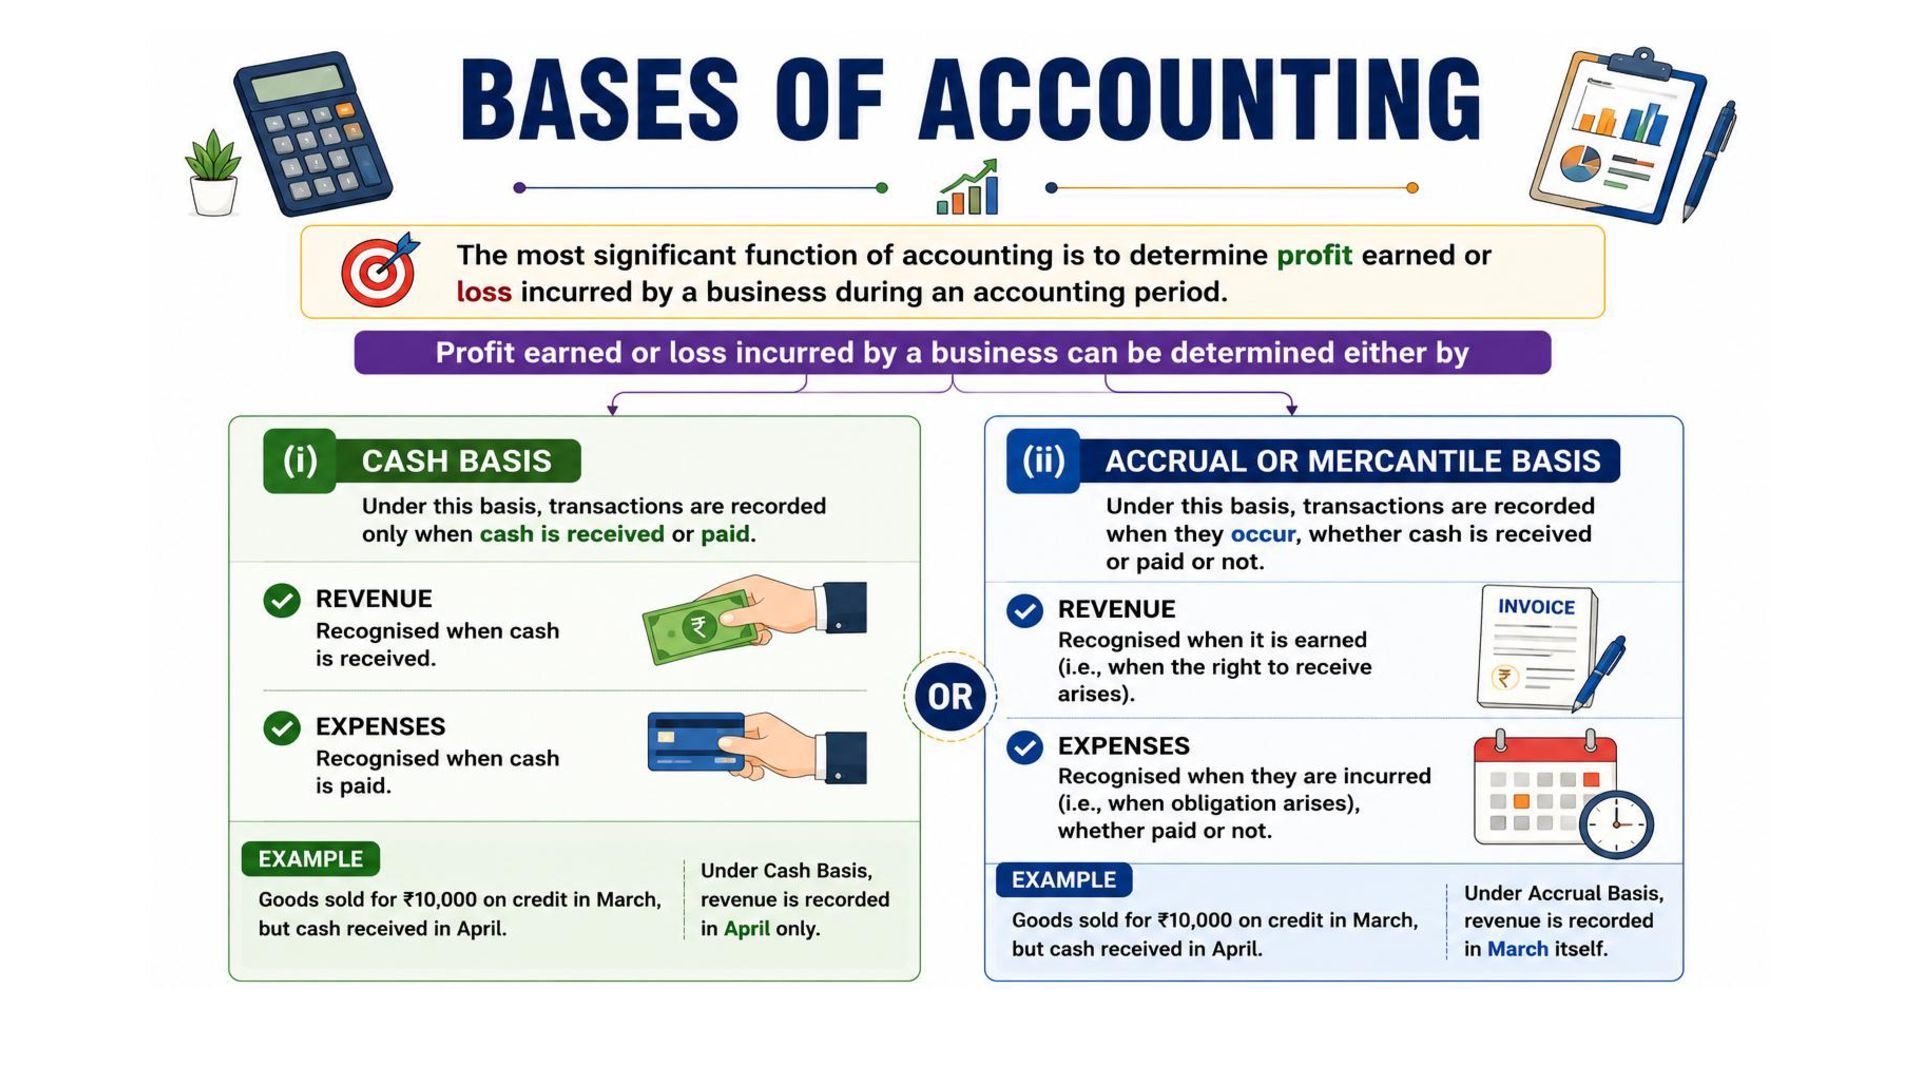
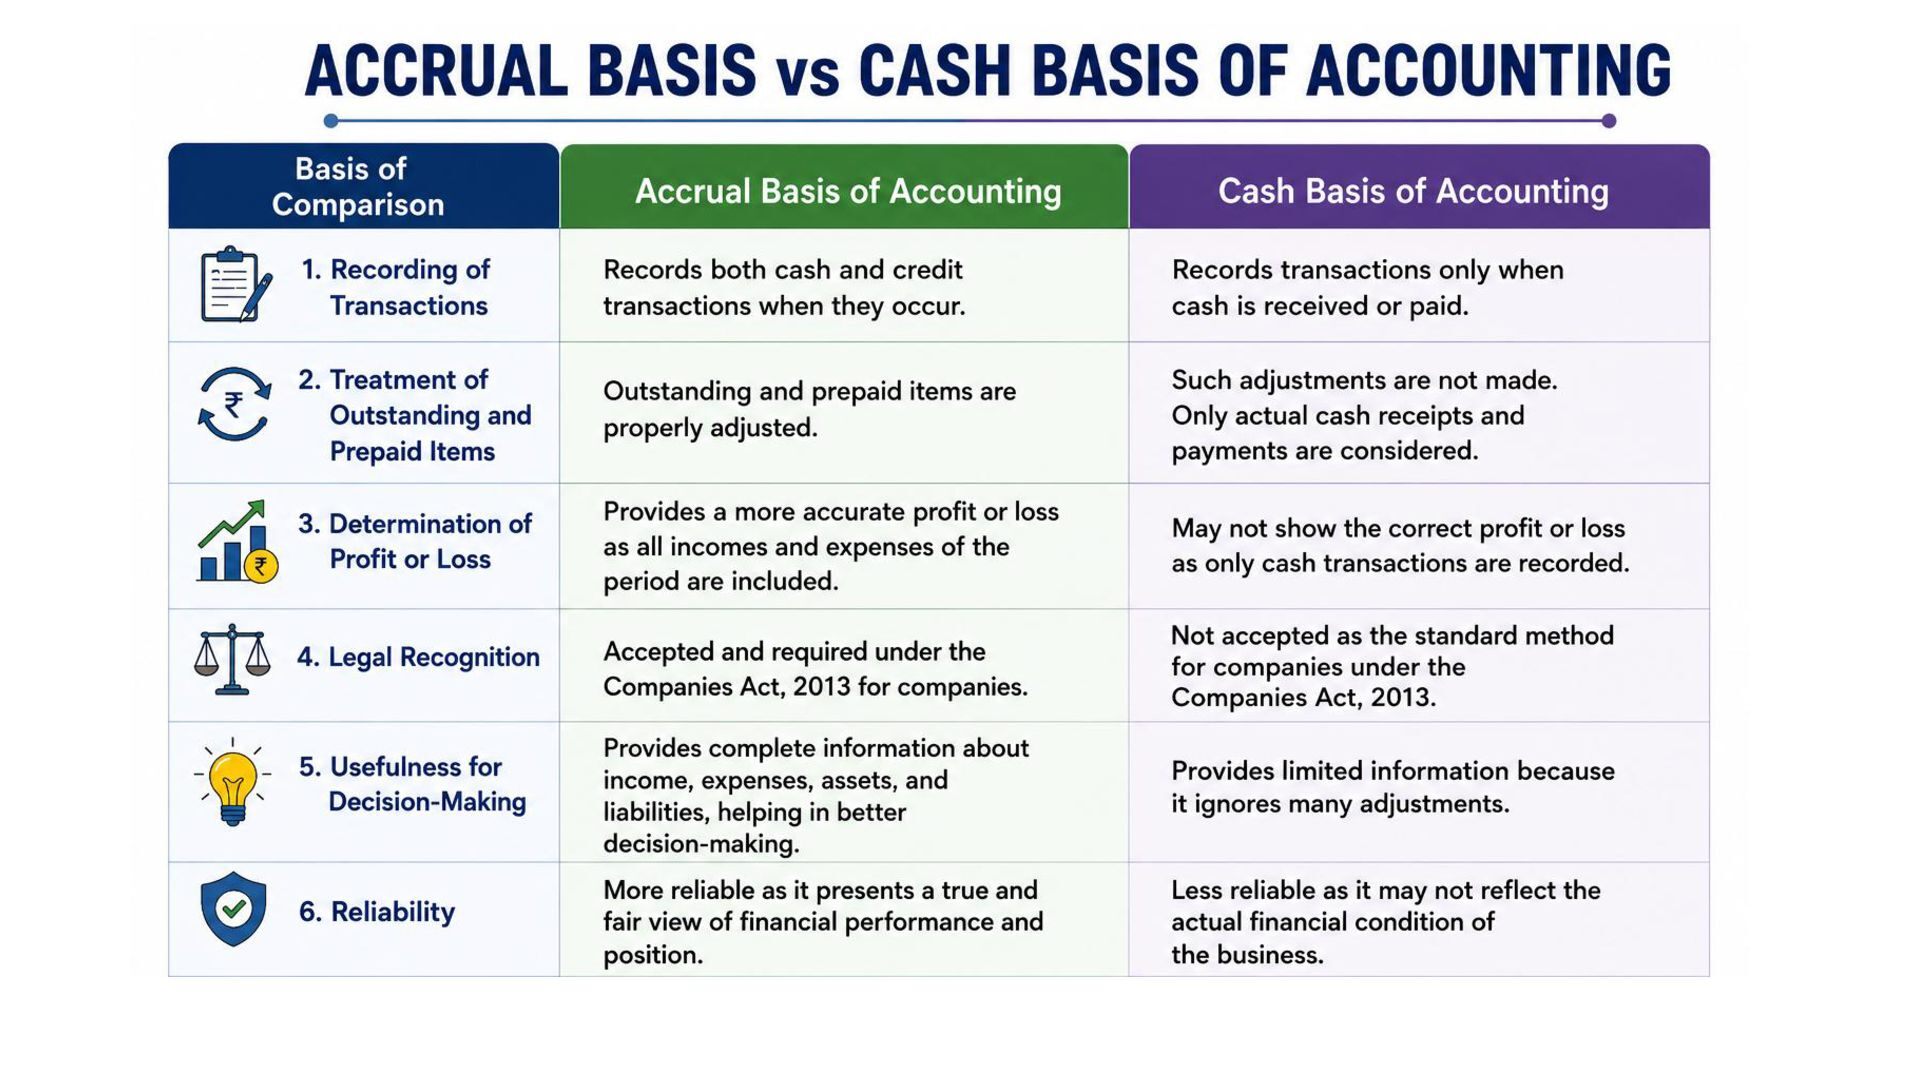
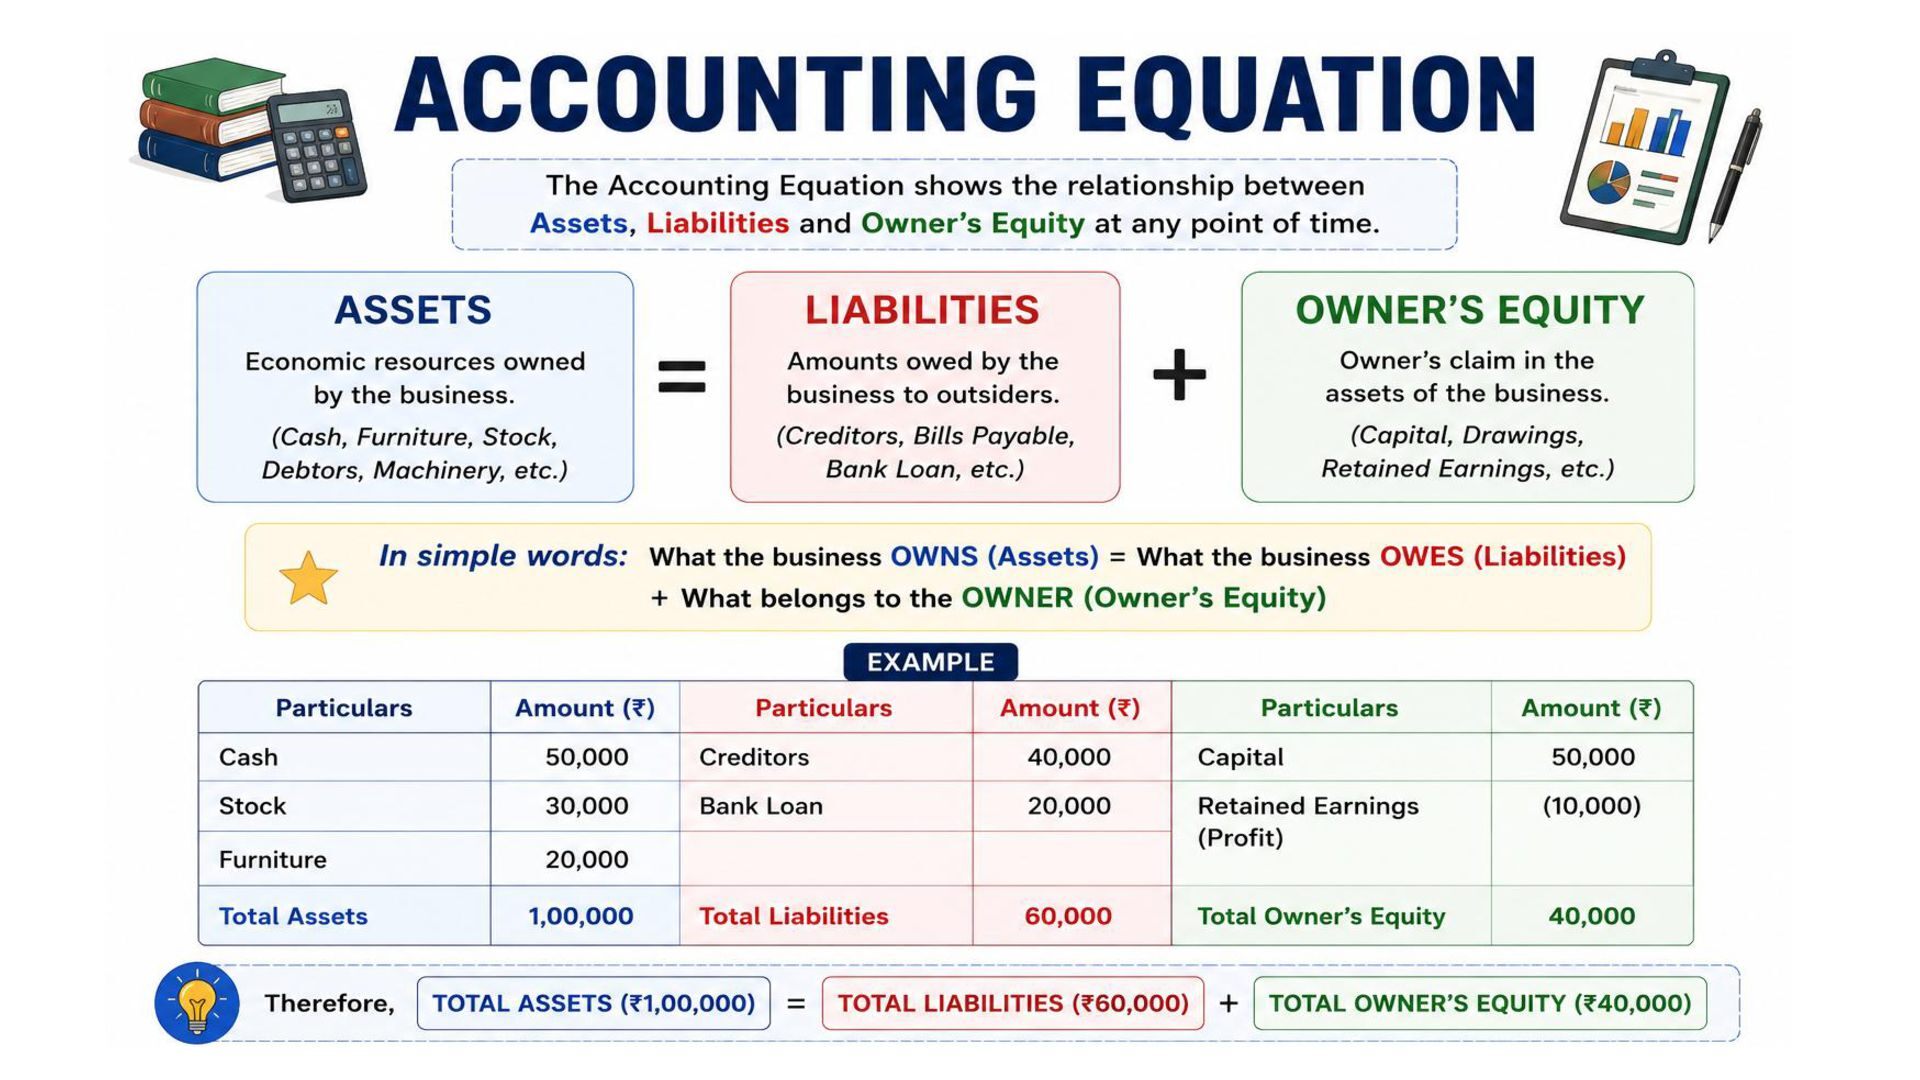
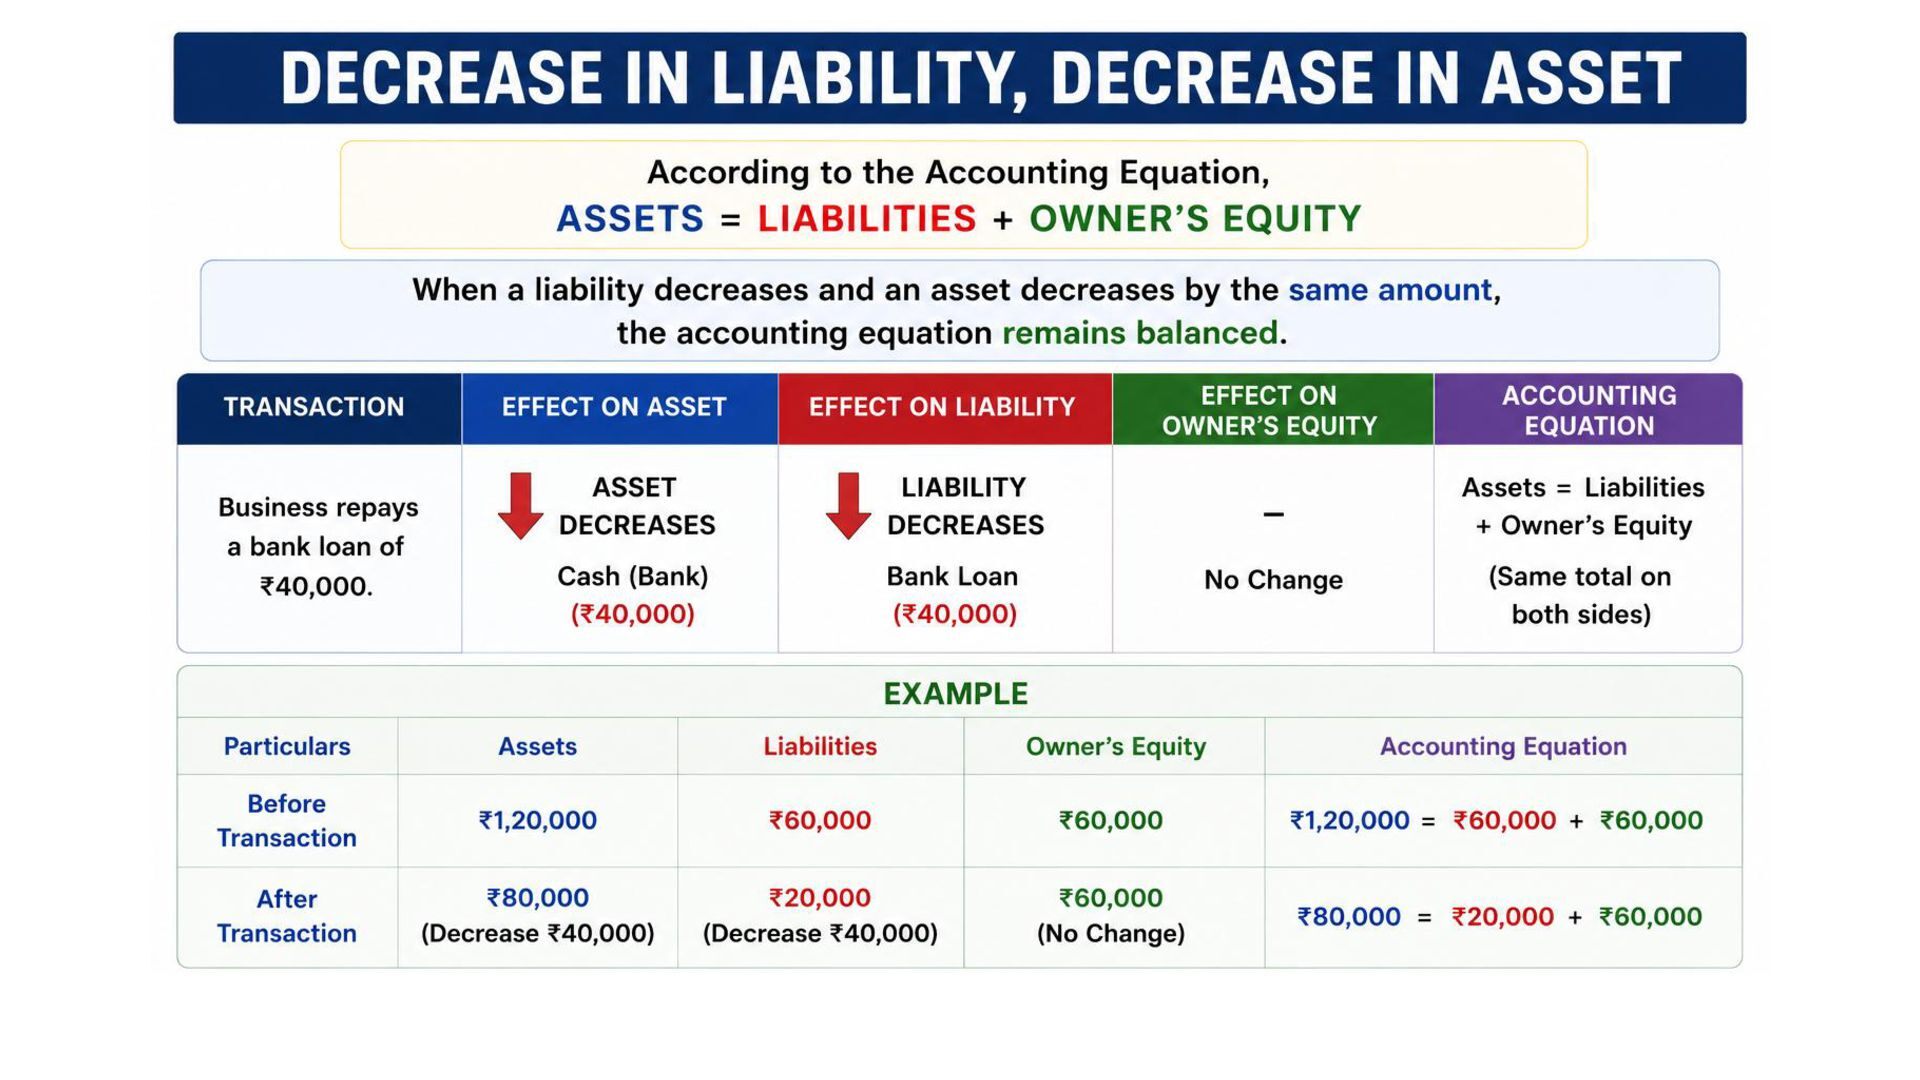
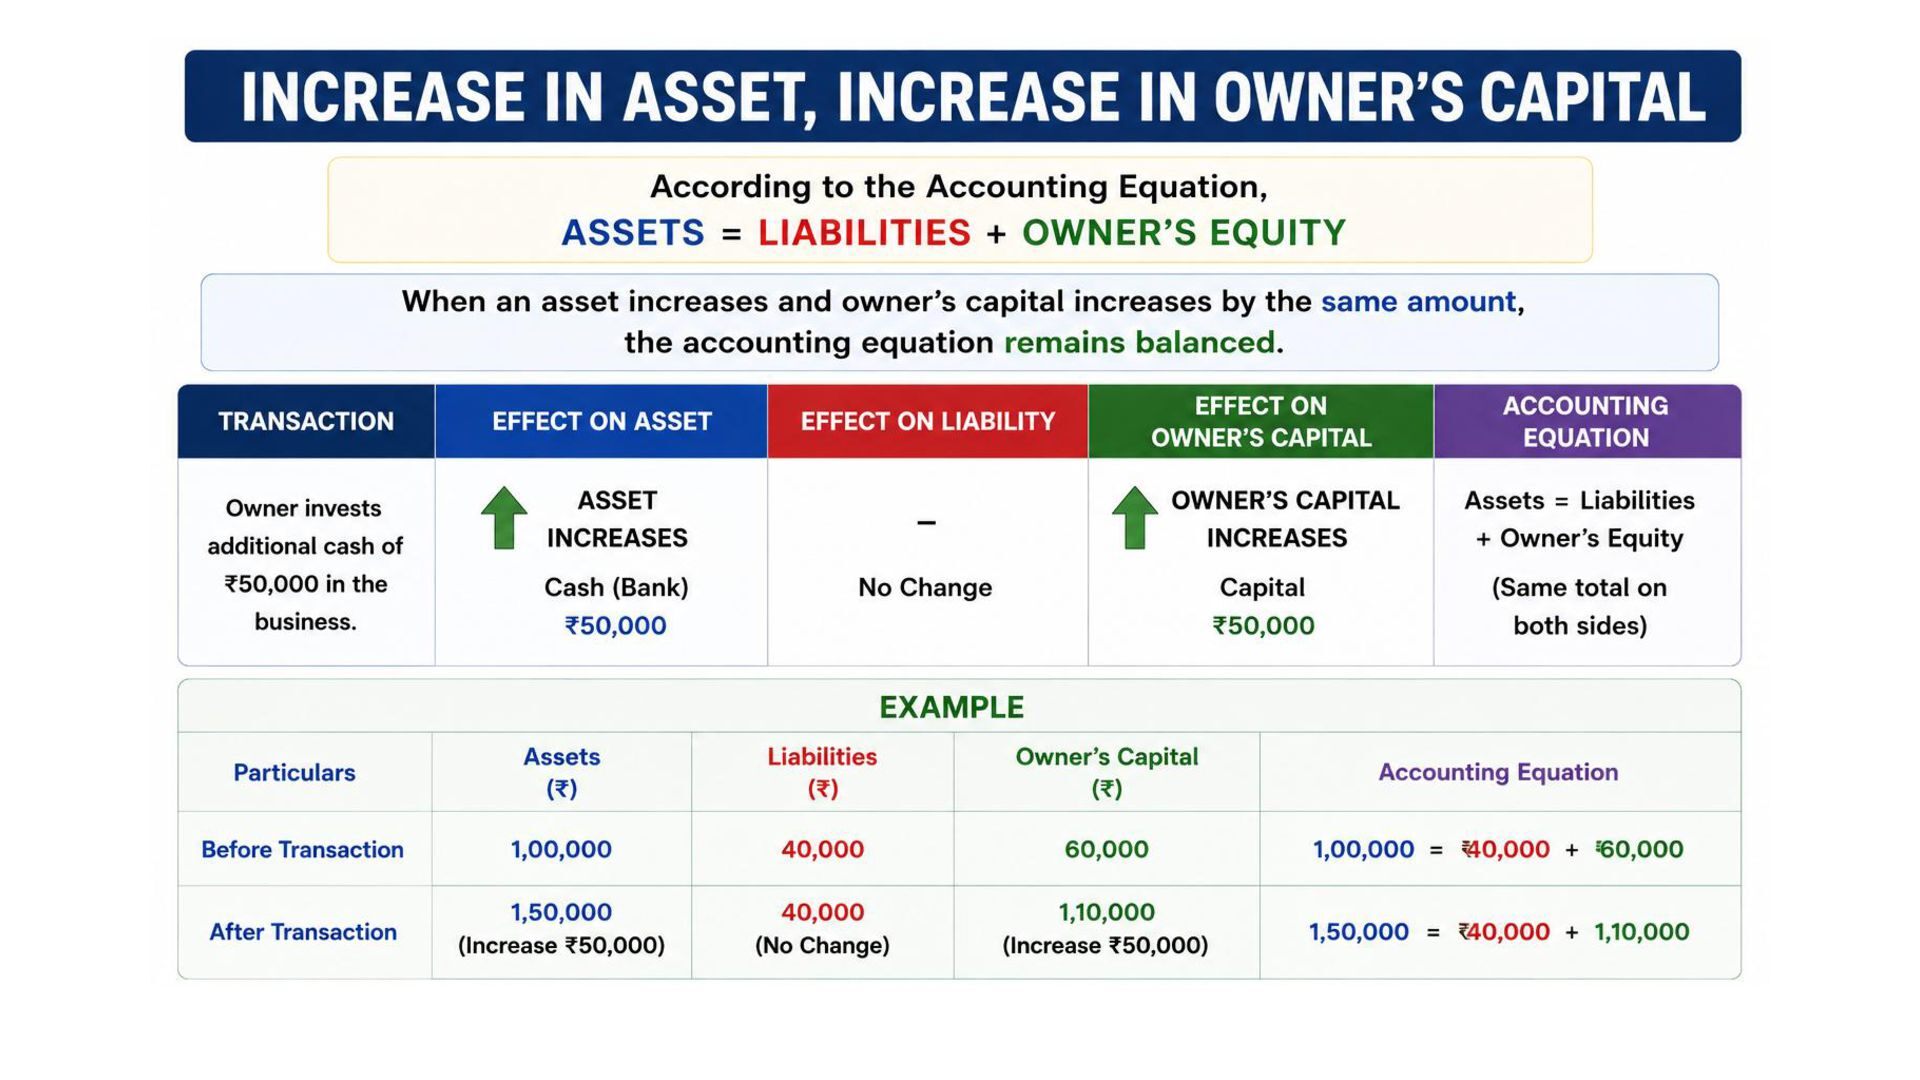
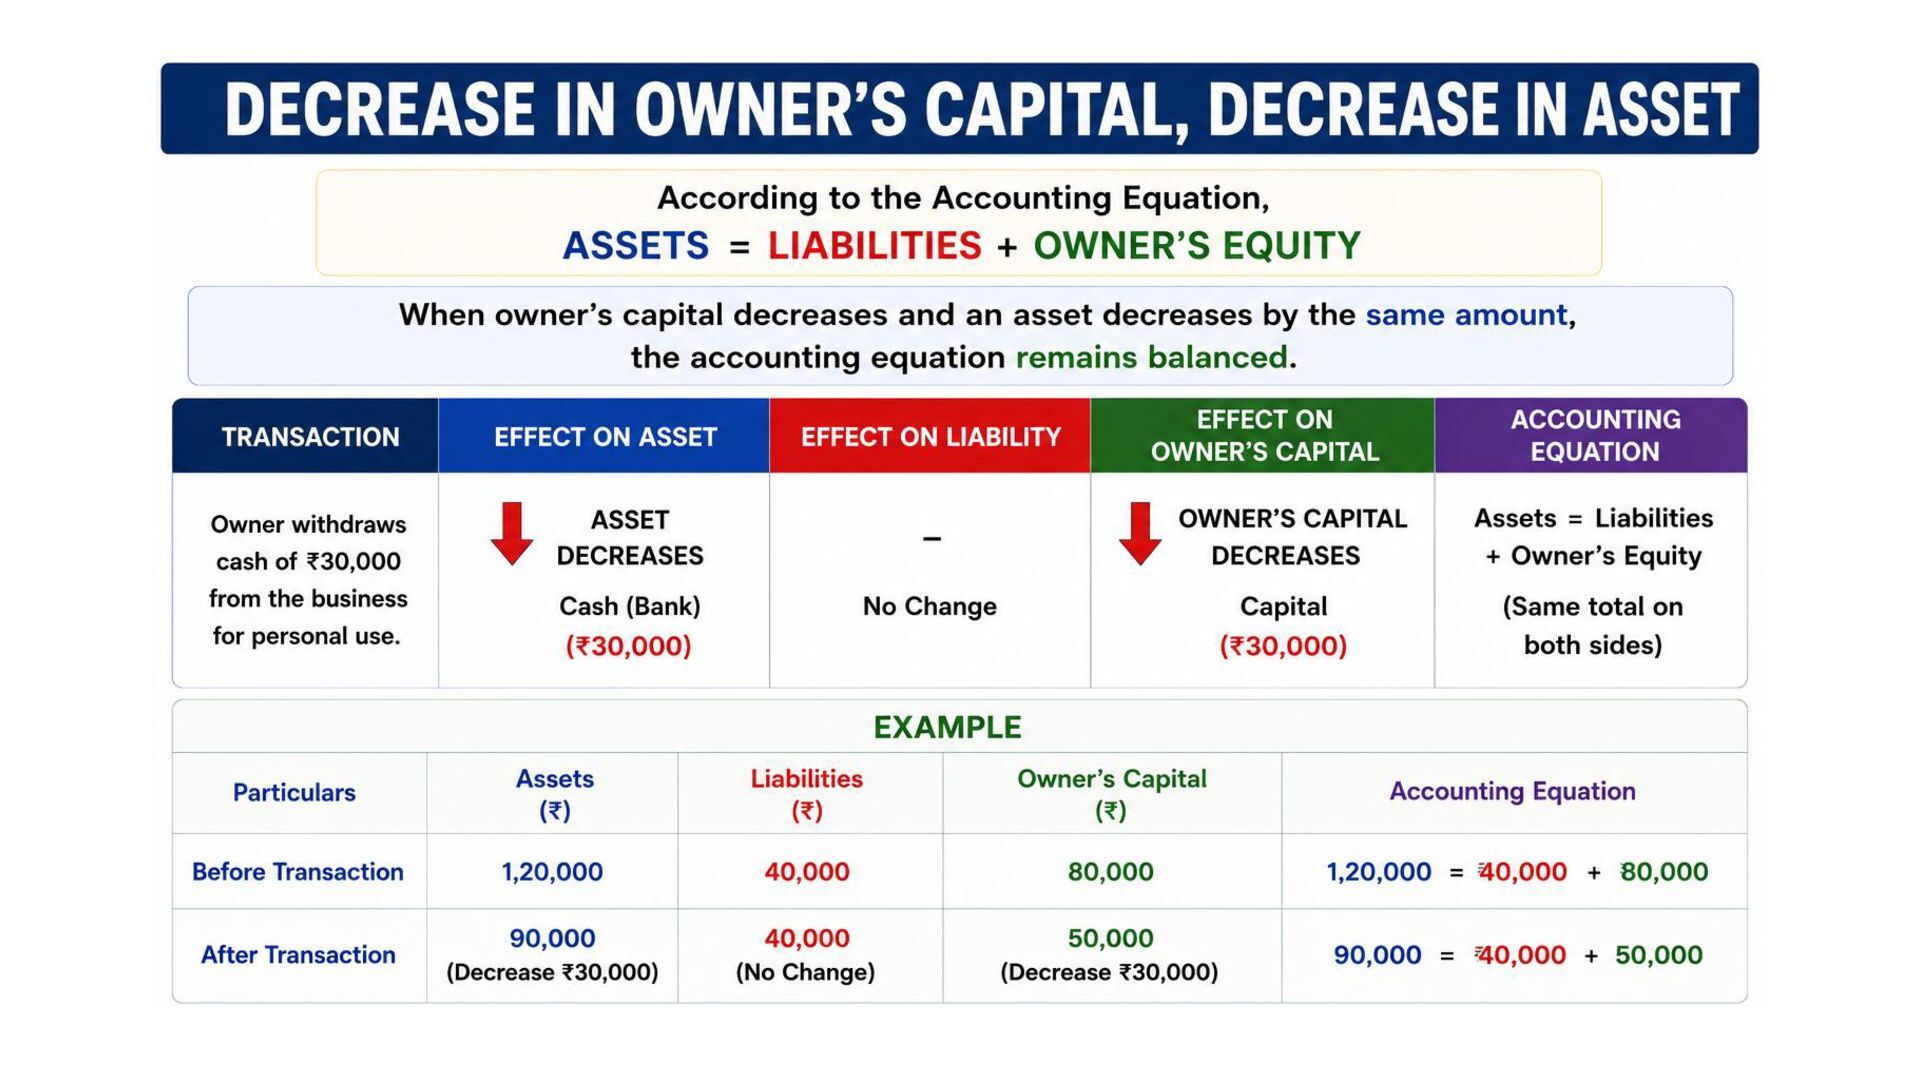
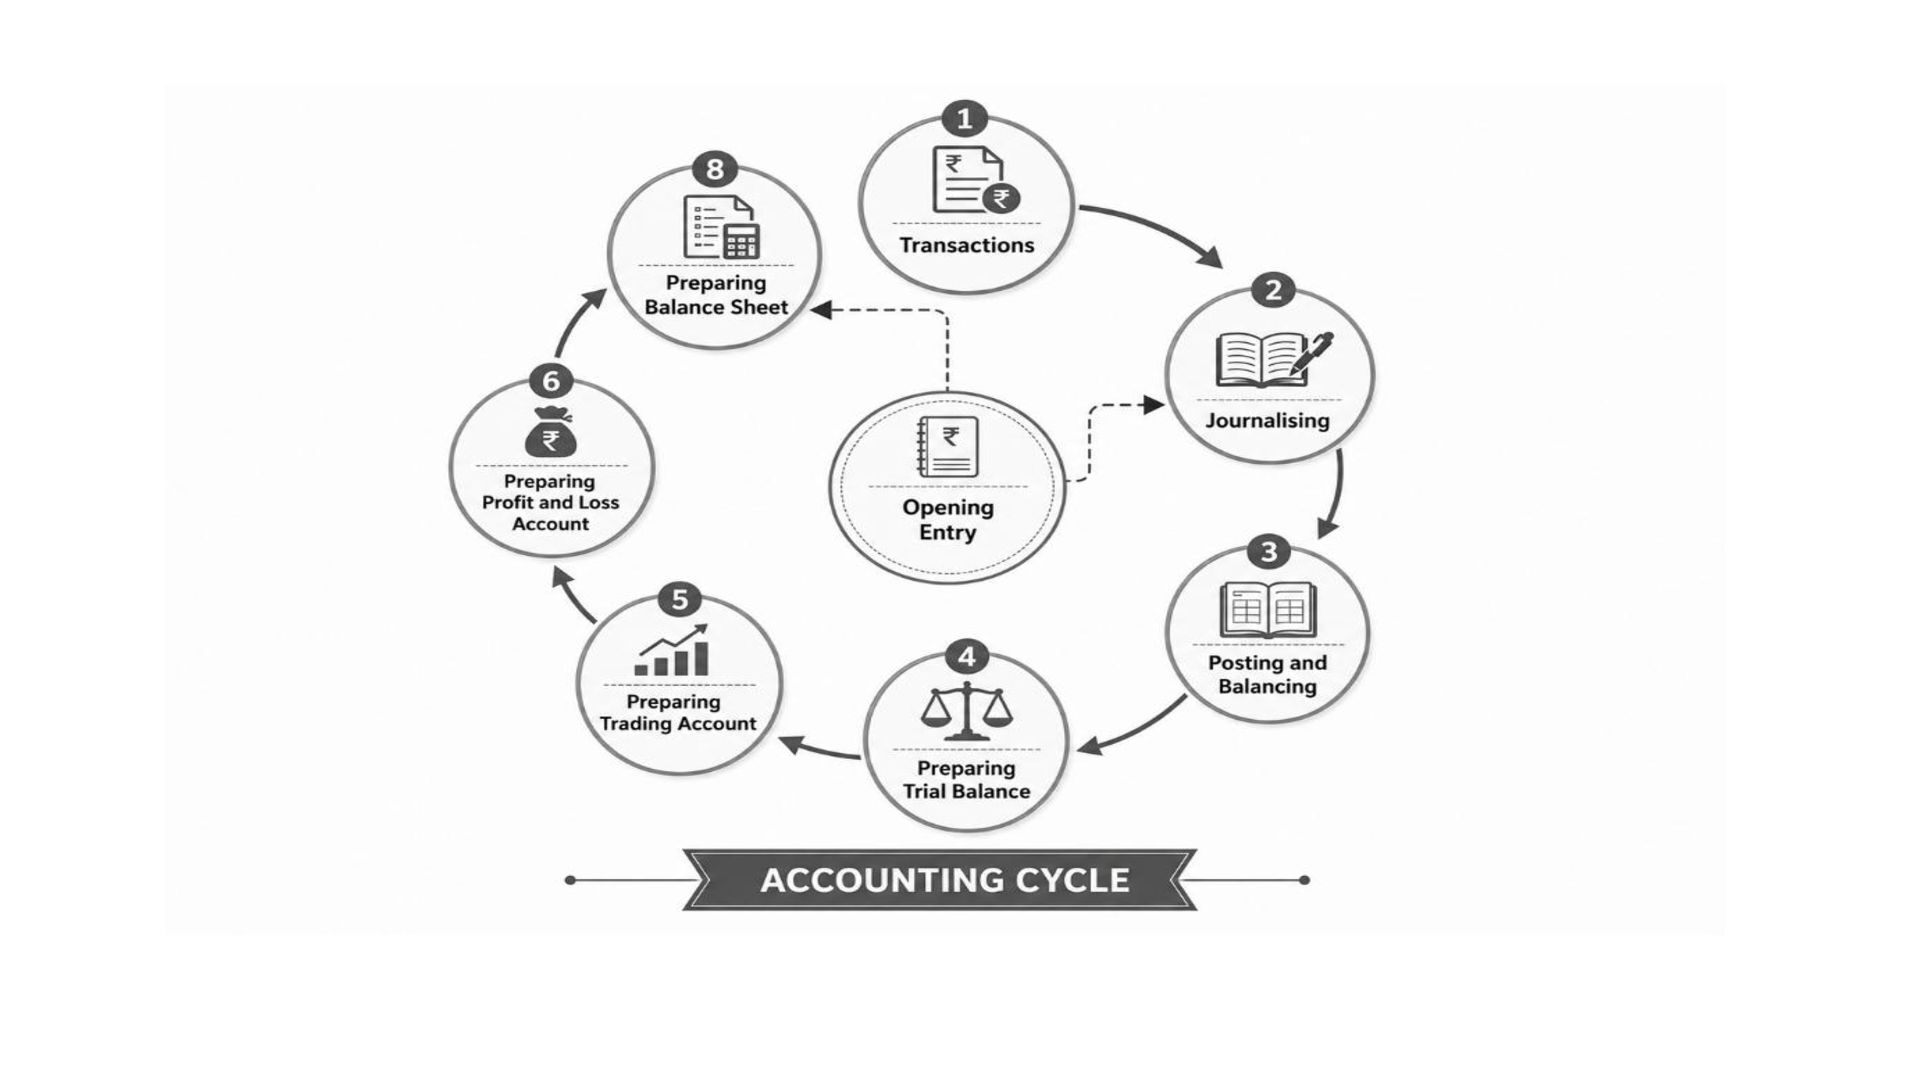
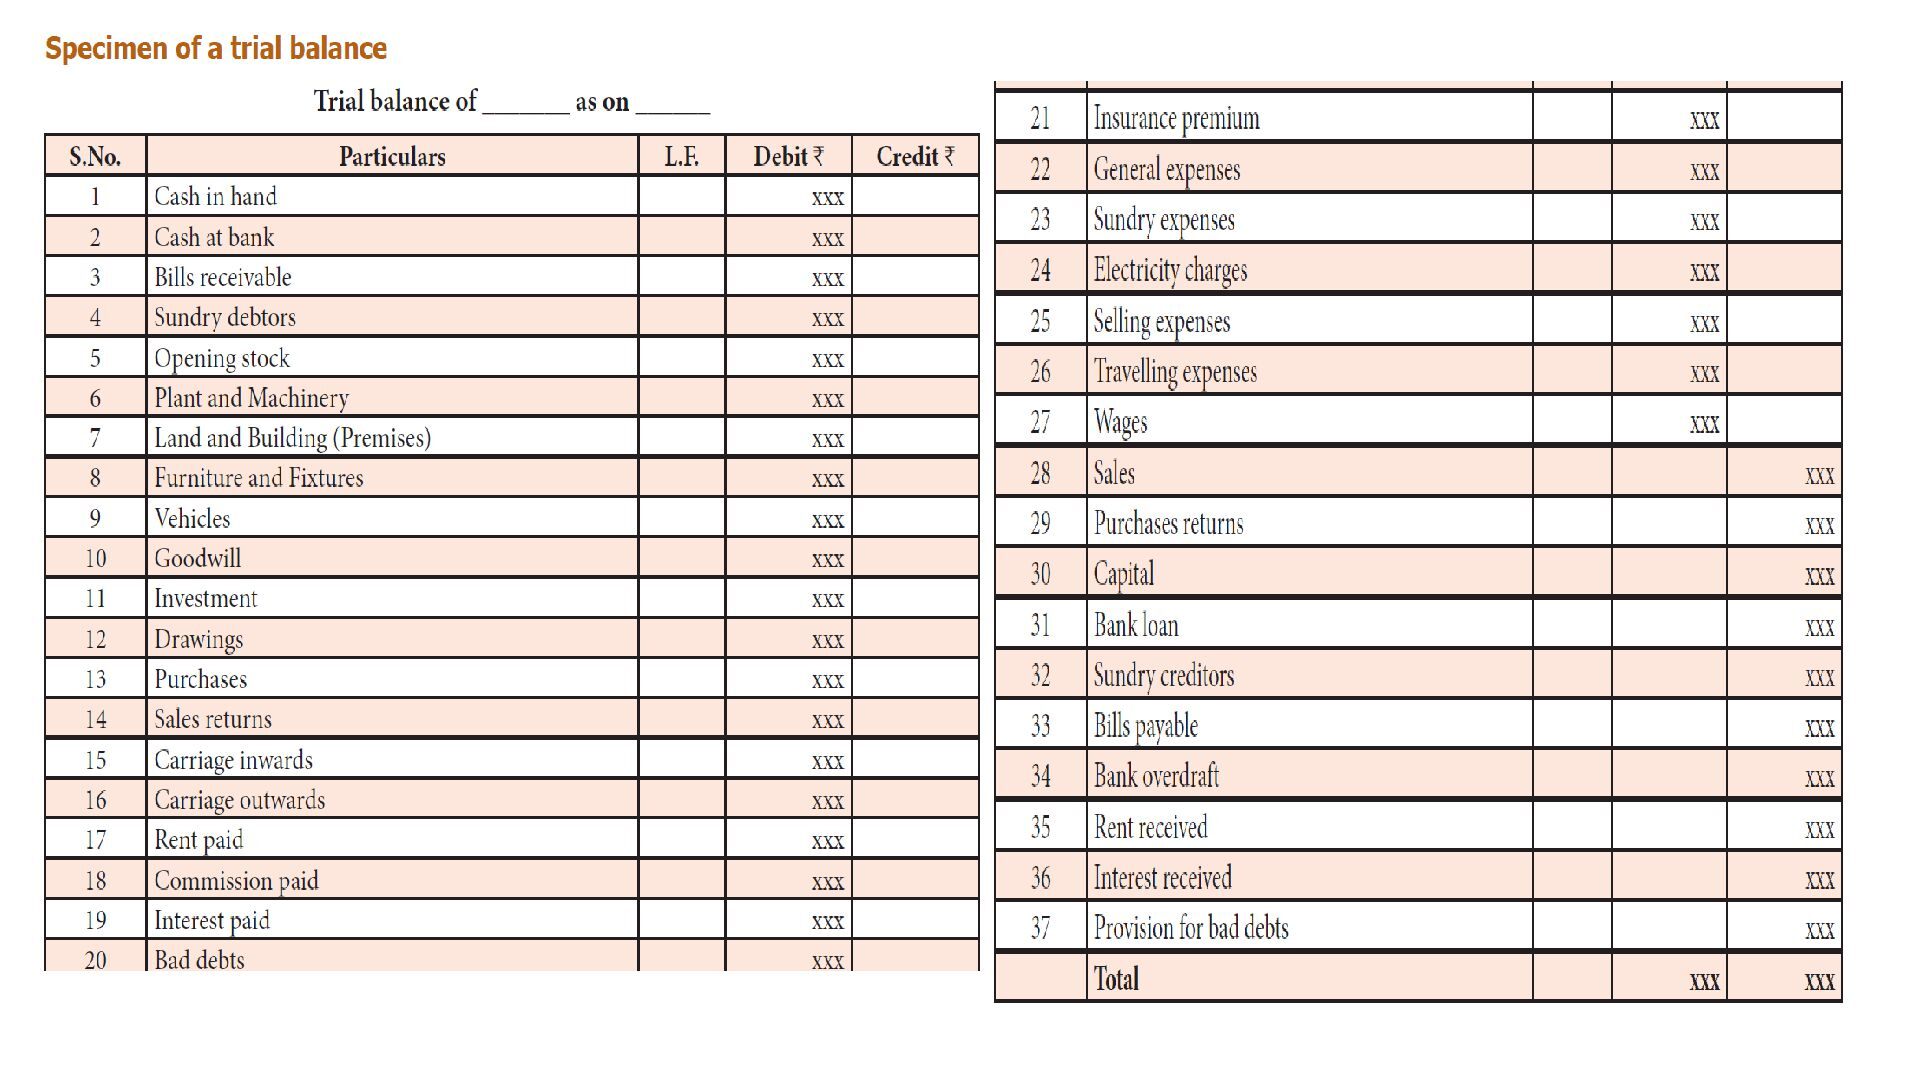
Basis of Accounting – Cash, and Accrual Basis, Accounting Equations – Meaning, Effects of Transactions on Accounting Equations, Process of Preparing Accounting Equation, Accounting Procedures- Rules of Debit and Credit, Classification of Accounts, Balancing of Account, Significance of Debit and Credit in Balance in Accounts. Sources of Document. Journalising, Ledger Posting, Trial Balance.

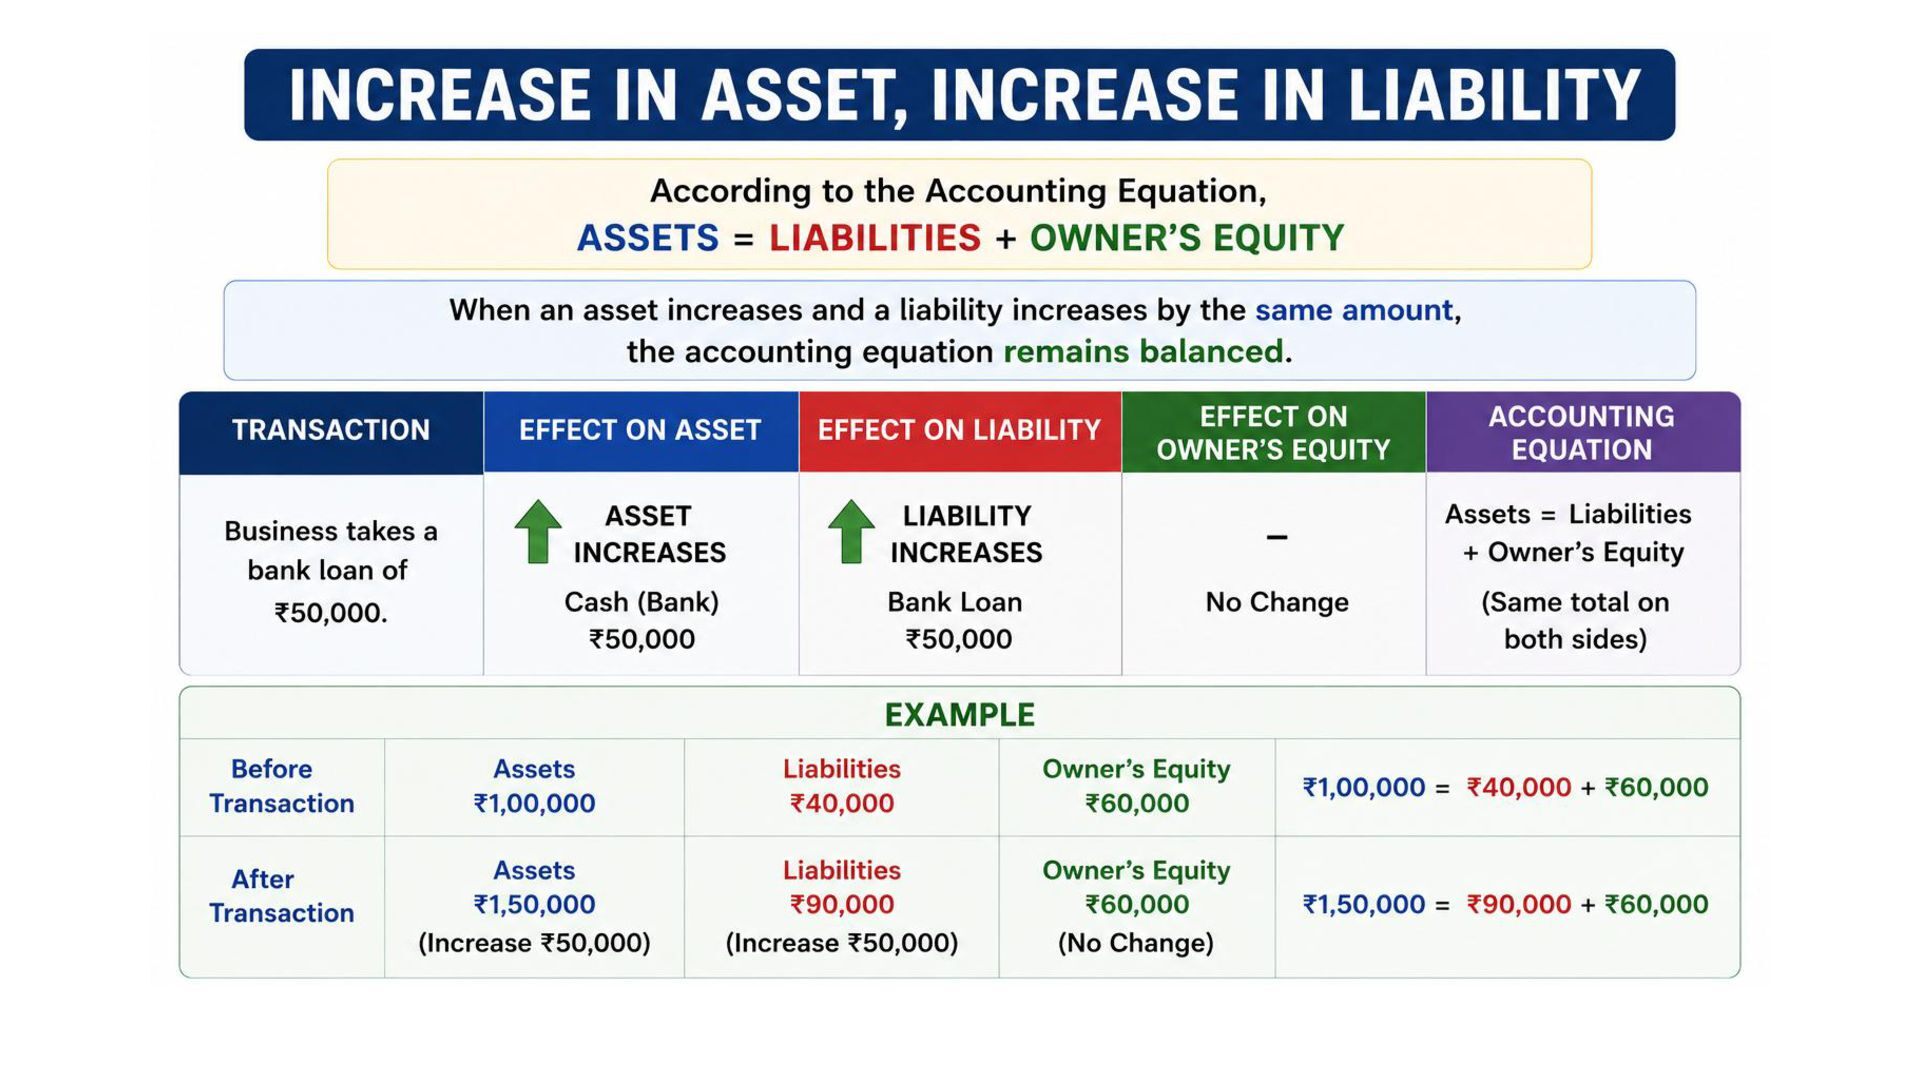
Avatar for Dr. Bharath V

Dr. Bharath V

September 11, 2026

More Decks by Dr. Bharath V

Other Decks in Education

Transcript

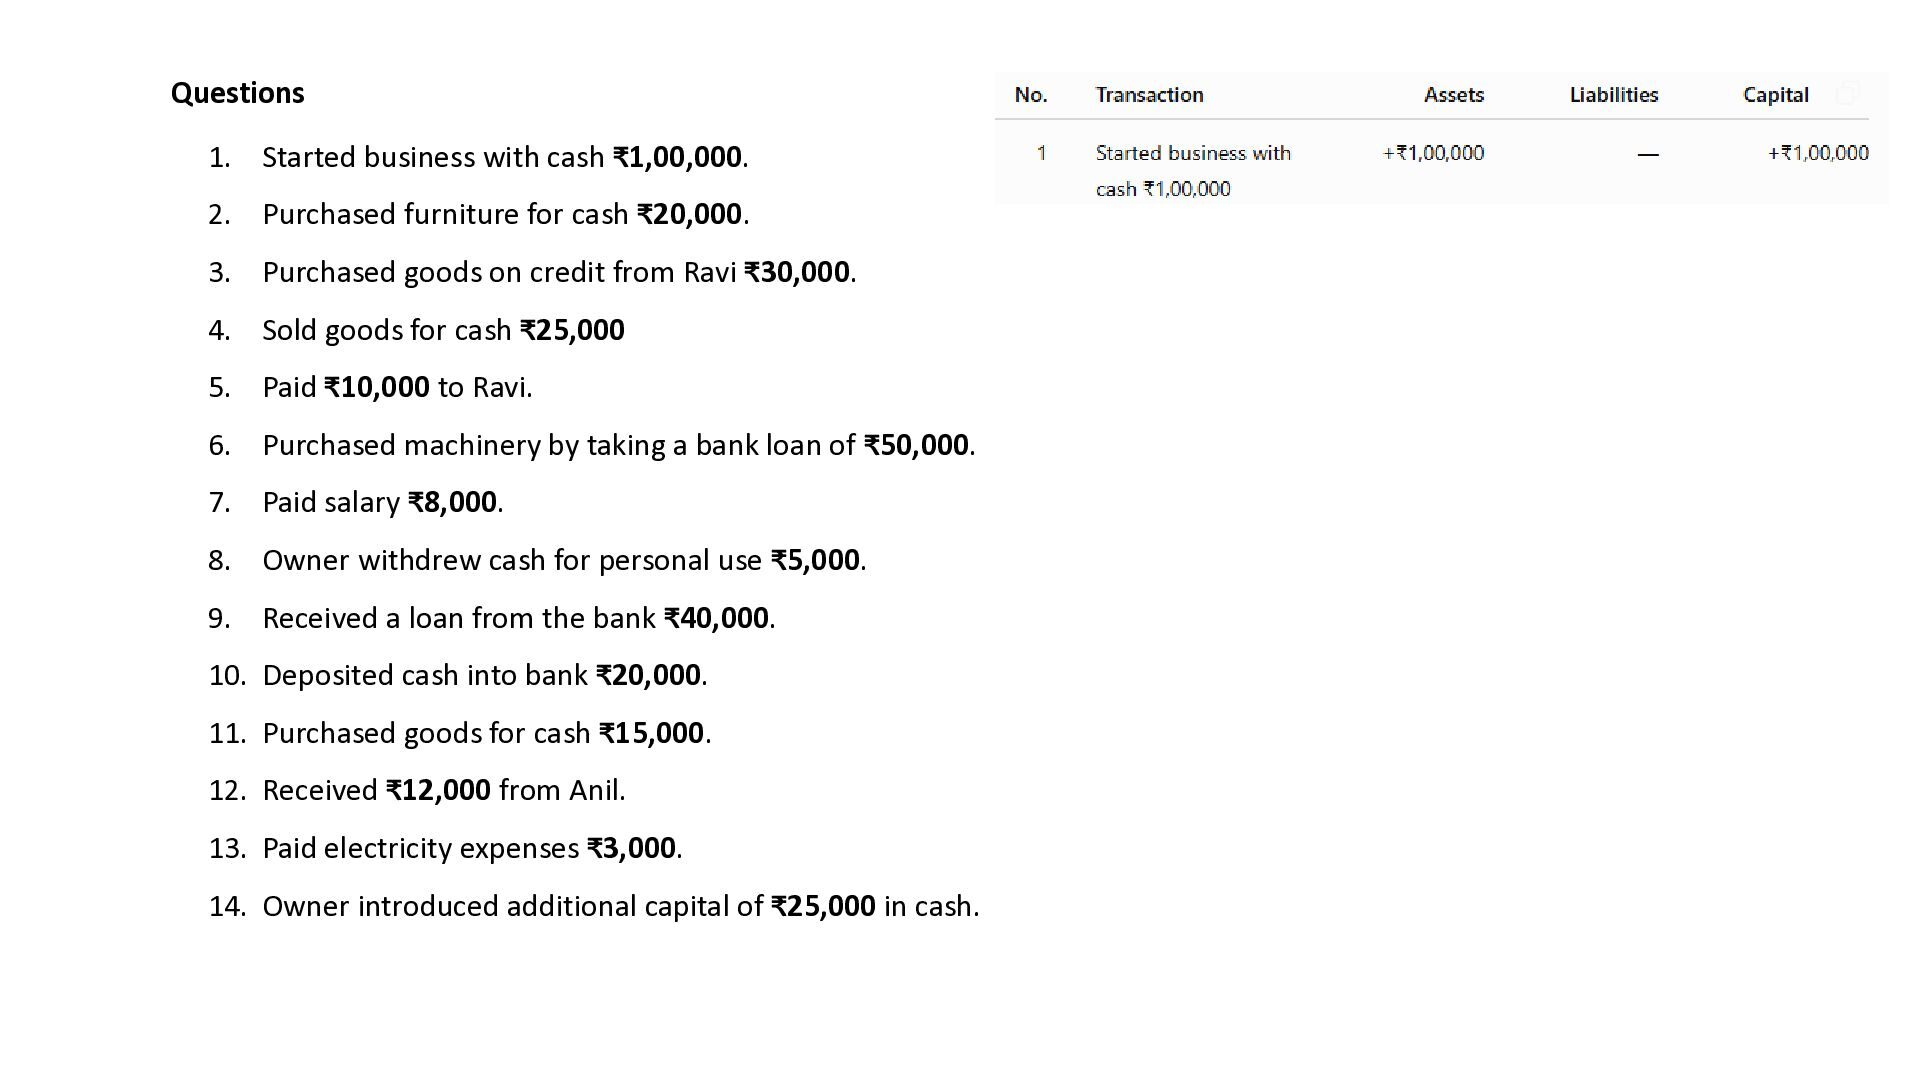
  1. Questions 1. Started business with cash ₹1,00,000. 2. Purchased furniture

    for cash ₹20,000. 3. Purchased goods on credit from Ravi ₹30,000. 4. Sold goods for cash ₹25,000 5. Paid ₹10,000 to Ravi. 6. Purchased machinery by taking a bank loan of ₹50,000. 7. Paid salary ₹8,000. 8. Owner withdrew cash for personal use ₹5,000. 9. Received a loan from the bank ₹40,000. 10. Deposited cash into bank ₹20,000. 11. Purchased goods for cash ₹15,000. 12. Received ₹12,000 from Anil. 13. Paid electricity expenses ₹3,000. 14. Owner introduced additional capital of ₹25,000 in cash.
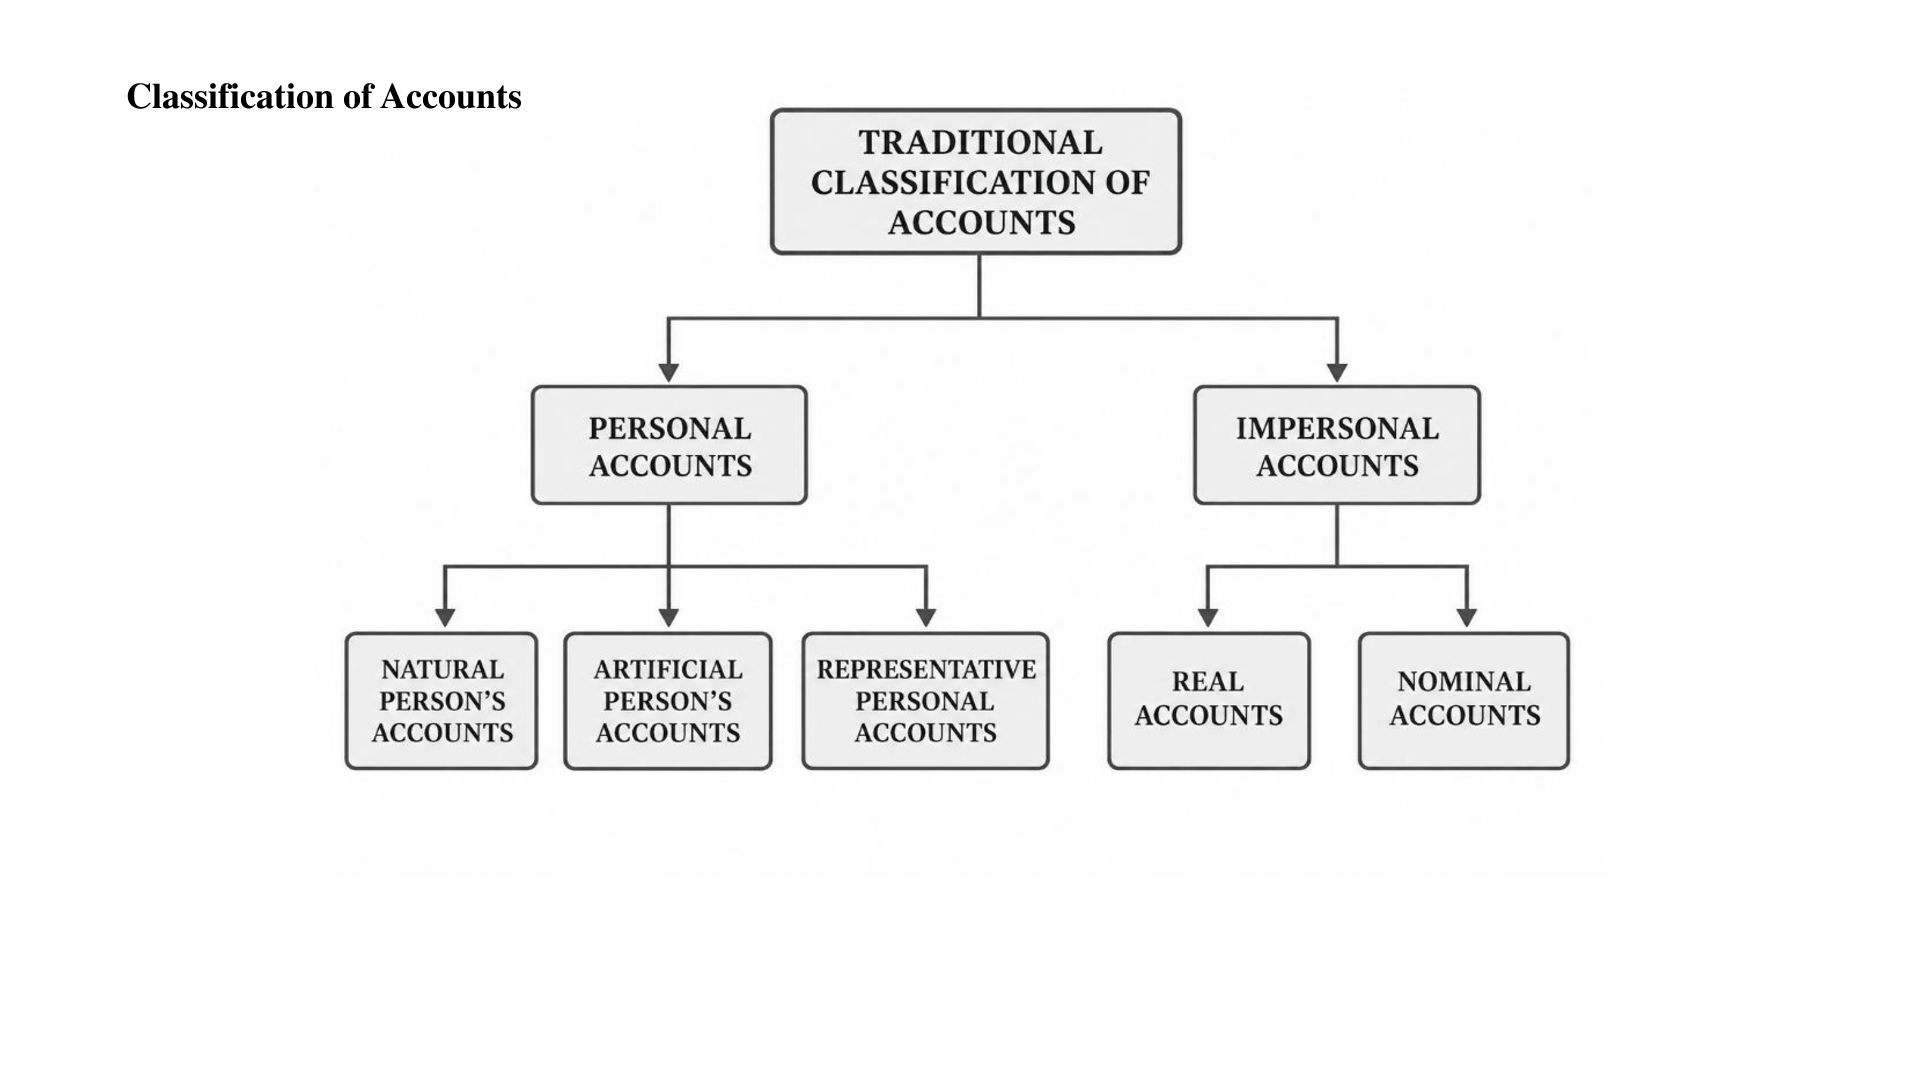
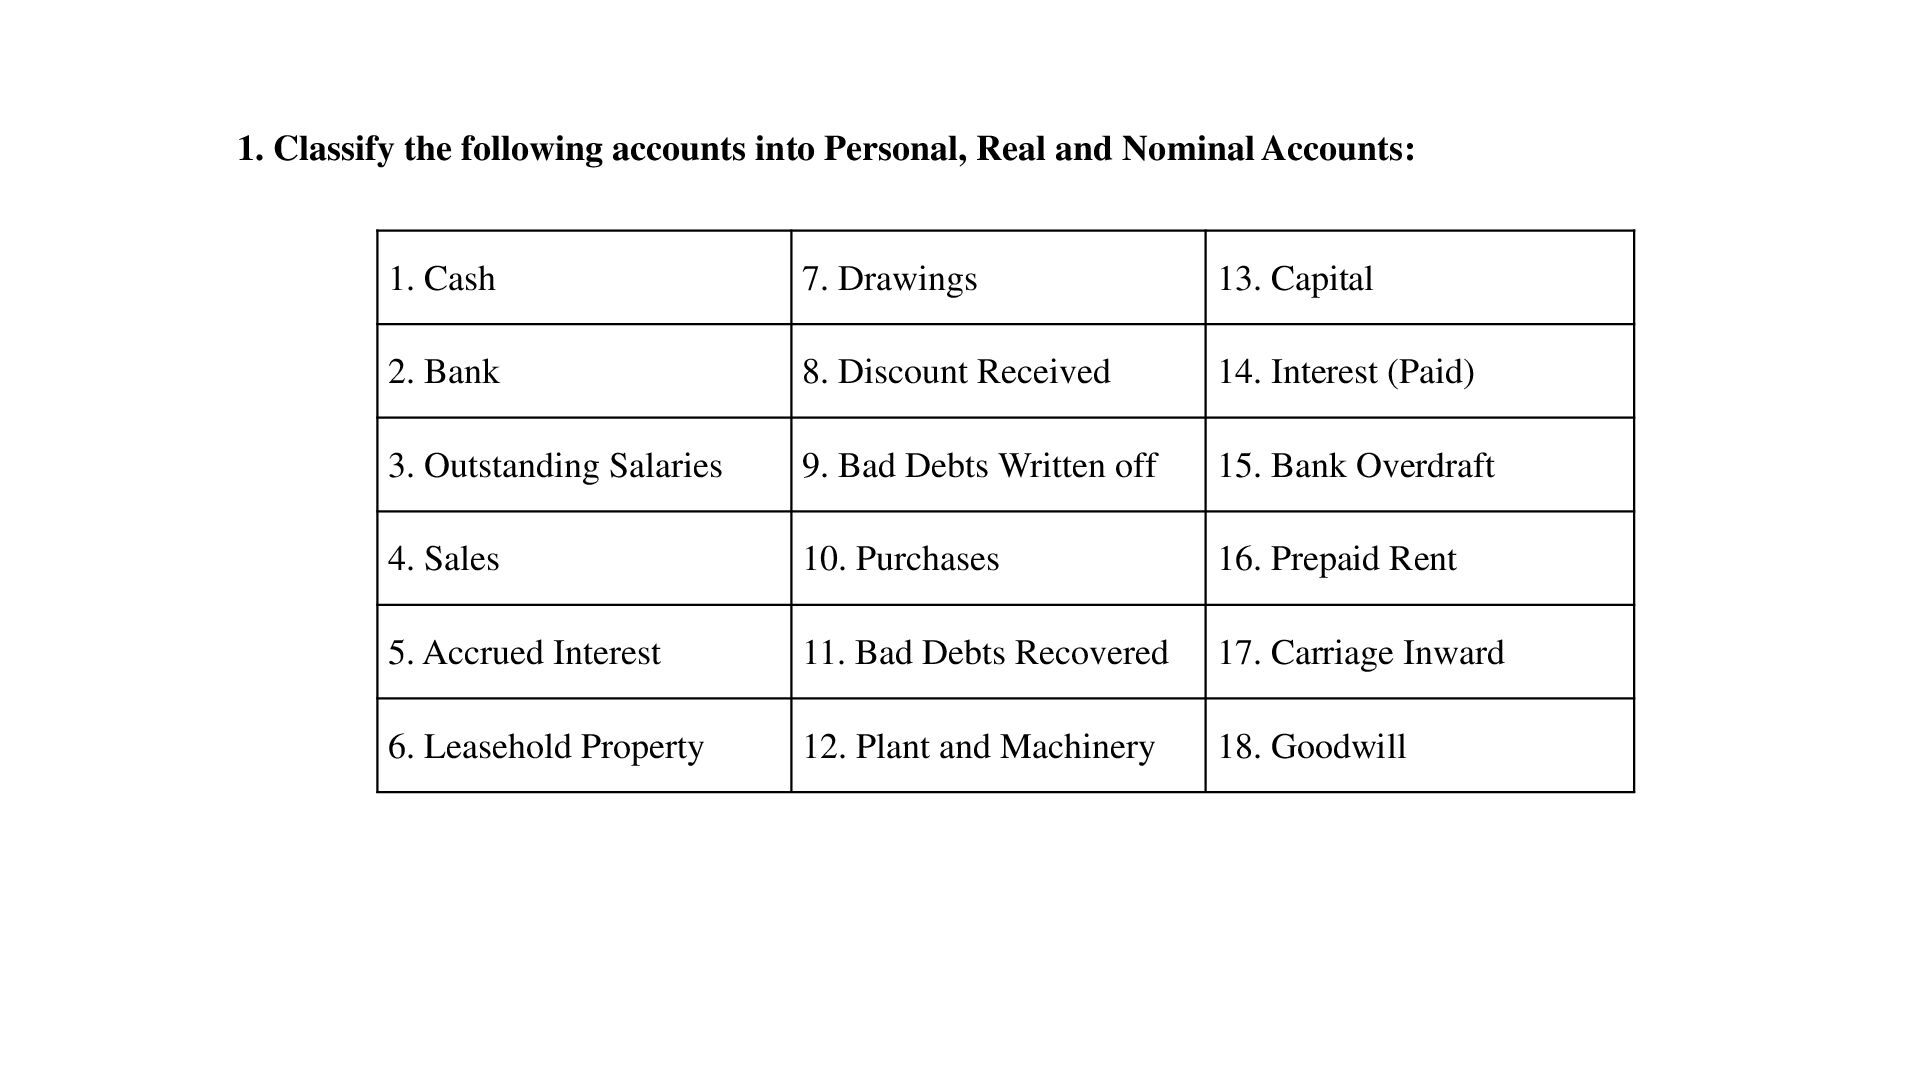
  2. 1. Classify the following accounts into Personal, Real and Nominal

    Accounts: 1. Cash 7. Drawings 13. Capital 2. Bank 8. Discount Received 14. Interest (Paid) 3. Outstanding Salaries 9. Bad Debts Written off 15. Bank Overdraft 4. Sales 10. Purchases 16. Prepaid Rent 5. Accrued Interest 11. Bad Debts Recovered 17. Carriage Inward 6. Leasehold Property 12. Plant and Machinery 18. Goodwill
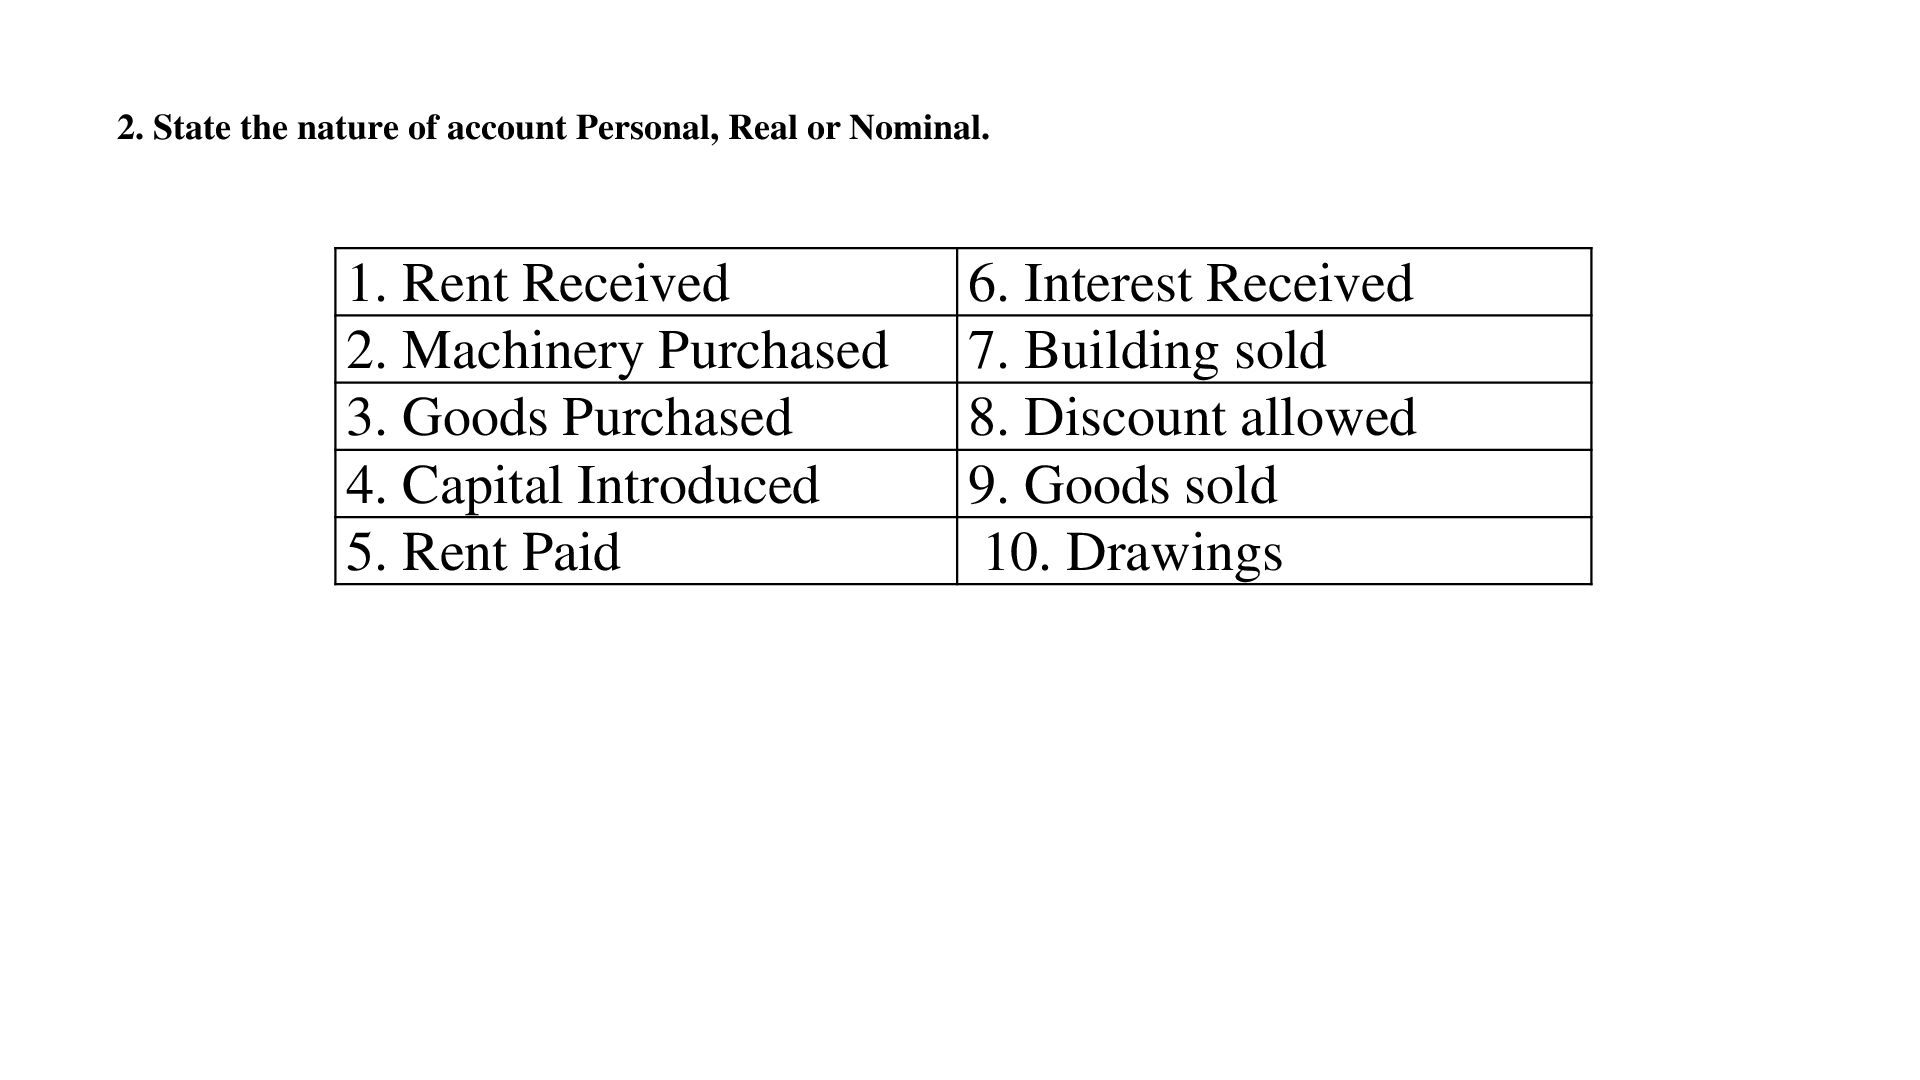
  3. 2. State the nature of account Personal, Real or Nominal.

    1. Rent Received 2. Machinery Purchased 3. Goods Purchased 4. Capital Introduced 5. Rent Paid 6. Interest Received 7. Building sold 8. Discount allowed 9. Goods sold 10. Drawings
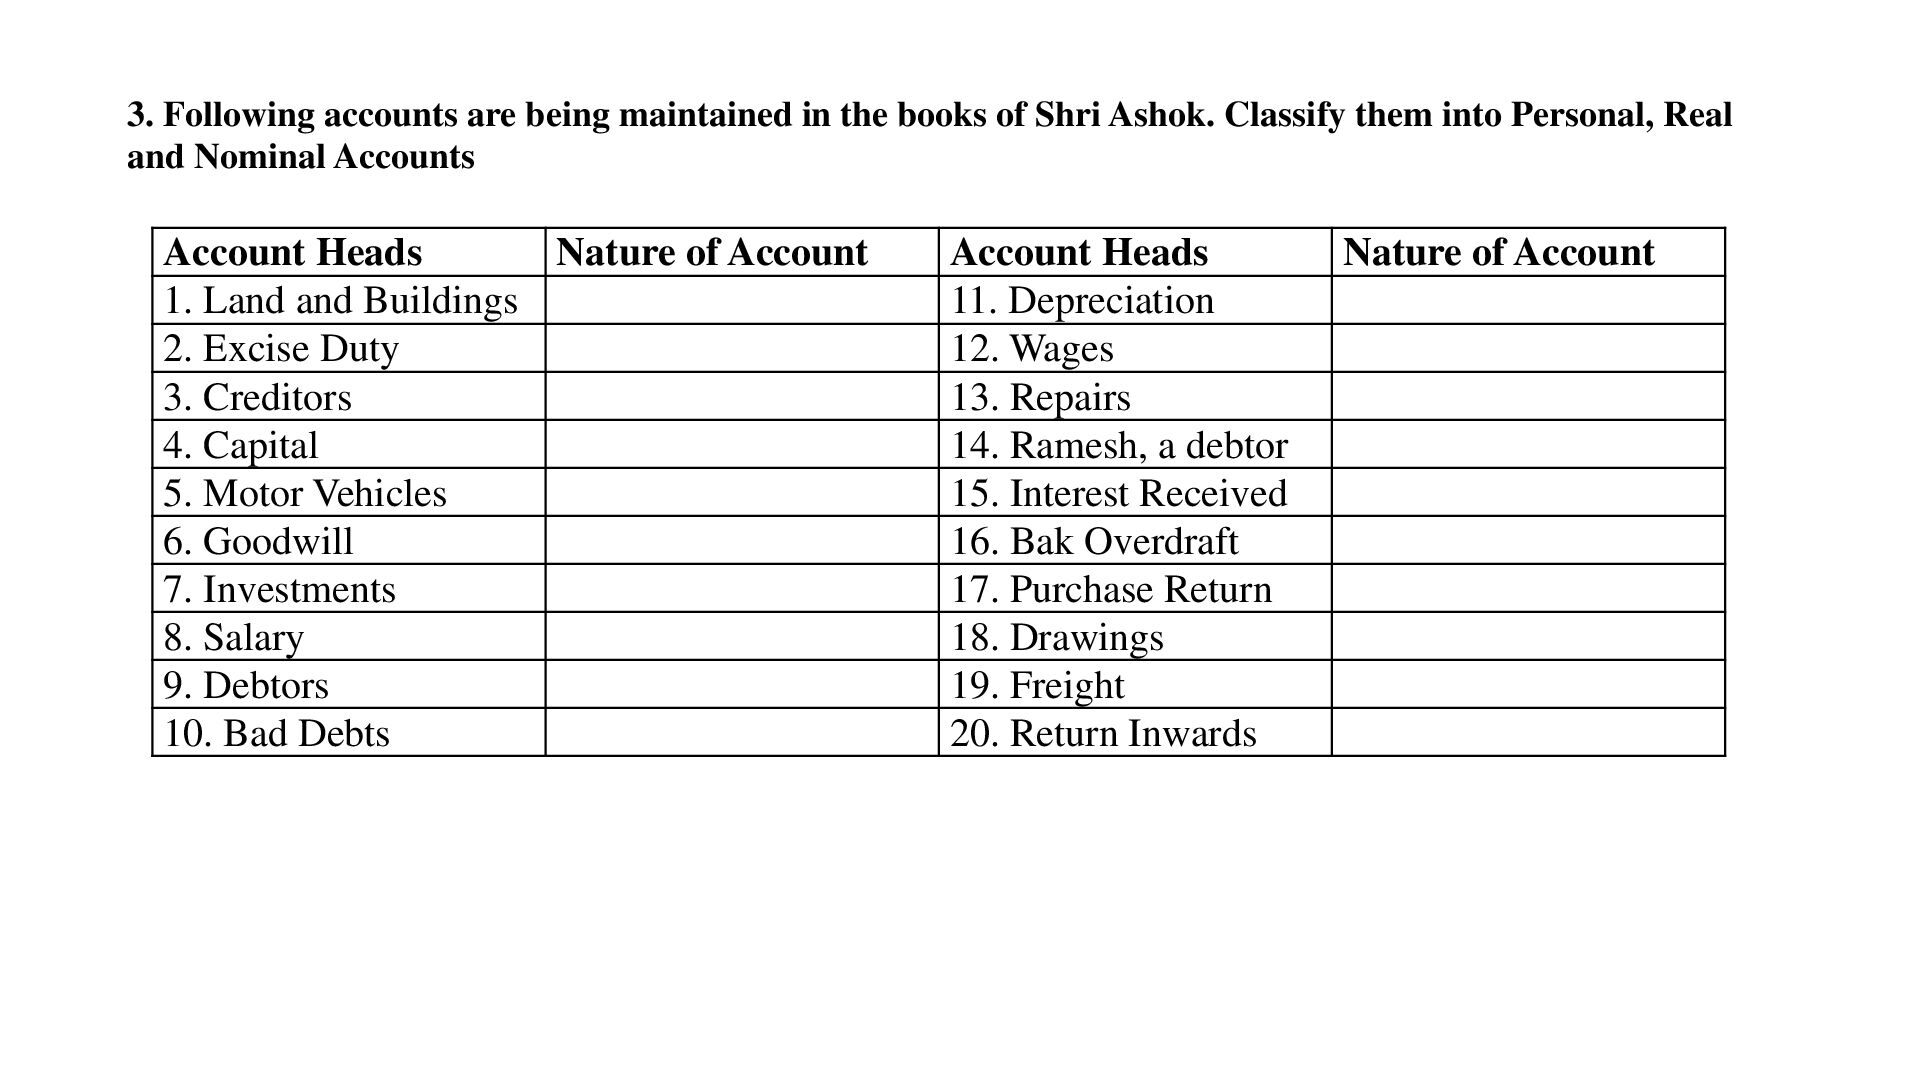
  4. 3. Following accounts are being maintained in the books of

    Shri Ashok. Classify them into Personal, Real and Nominal Accounts Account Heads Nature of Account 1. Land and Buildings 2. Excise Duty 3. Creditors 4. Capital 5. Motor Vehicles 6. Goodwill 7. Investments 8. Salary 9. Debtors 10. Bad Debts Account Heads 11. Depreciation 12. Wages 13. Repairs 14. Ramesh, a debtor 15. Interest Received 16. Bak Overdraft 17. Purchase Return 18. Drawings 19. Freight 20. Return Inwards Nature of Account
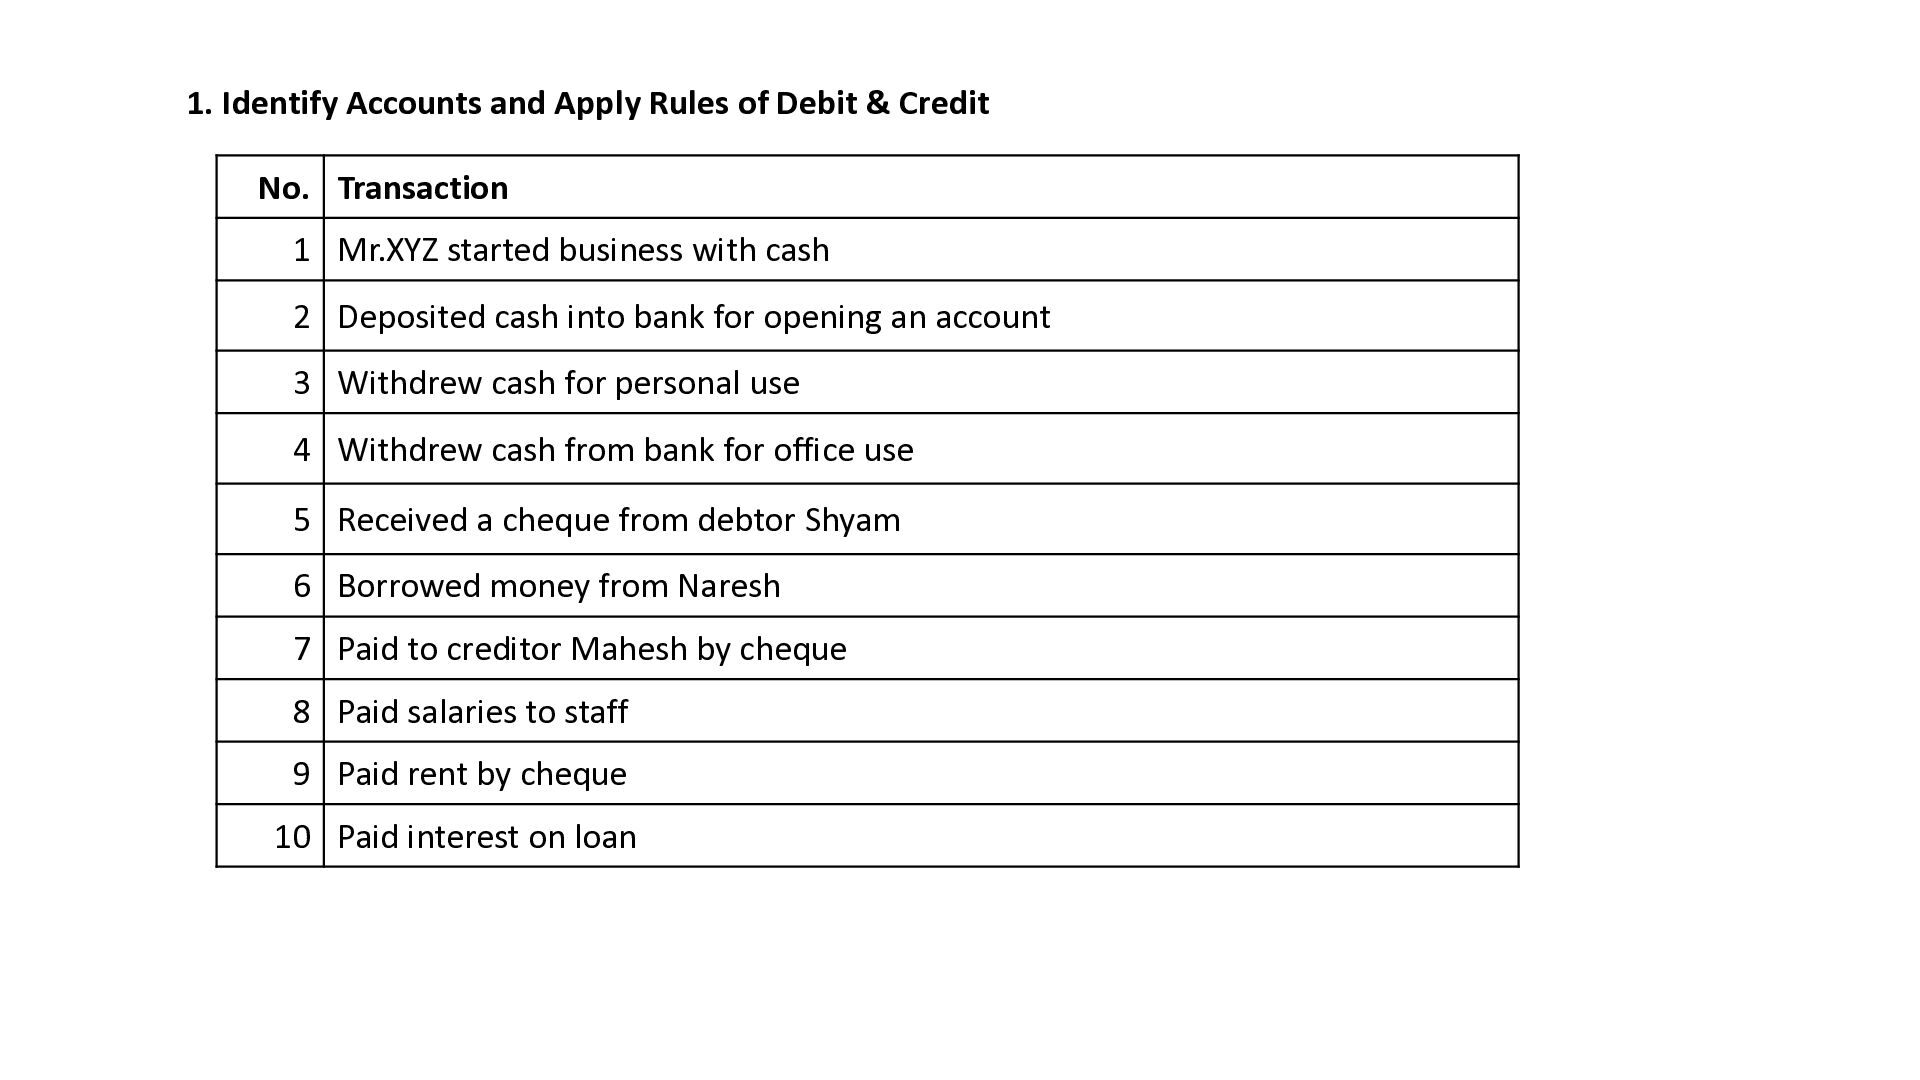
  5. 1. Identify Accounts and Apply Rules of Debit & Credit

    No. Transaction 1 Mr.XYZ started business with cash 2 Deposited cash into bank for opening an account 3 Withdrew cash for personal use 4 Withdrew cash from bank for office use 5 Received a cheque from debtor Shyam 6 Borrowed money from Naresh 7 Paid to creditor Mahesh by cheque 8 Paid salaries to staff 9 Paid rent by cheque 10 Paid interest on loan
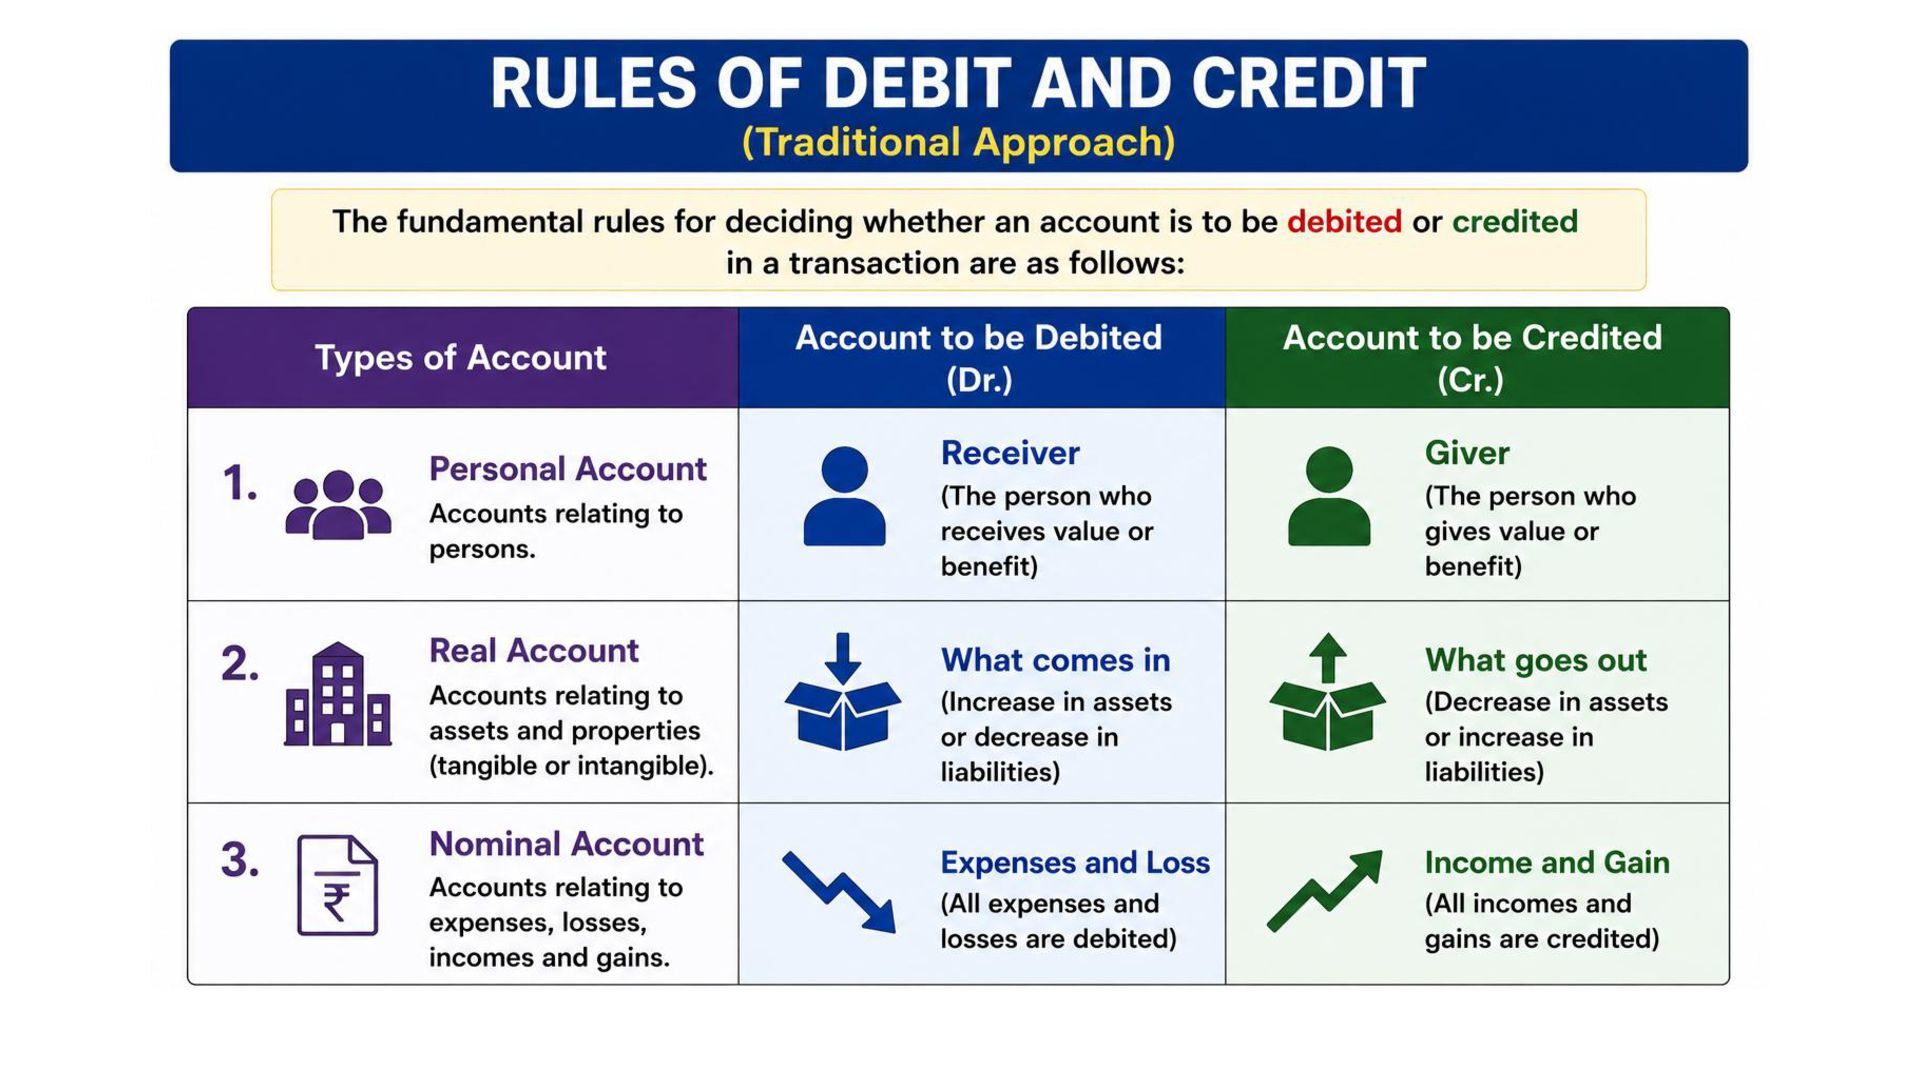
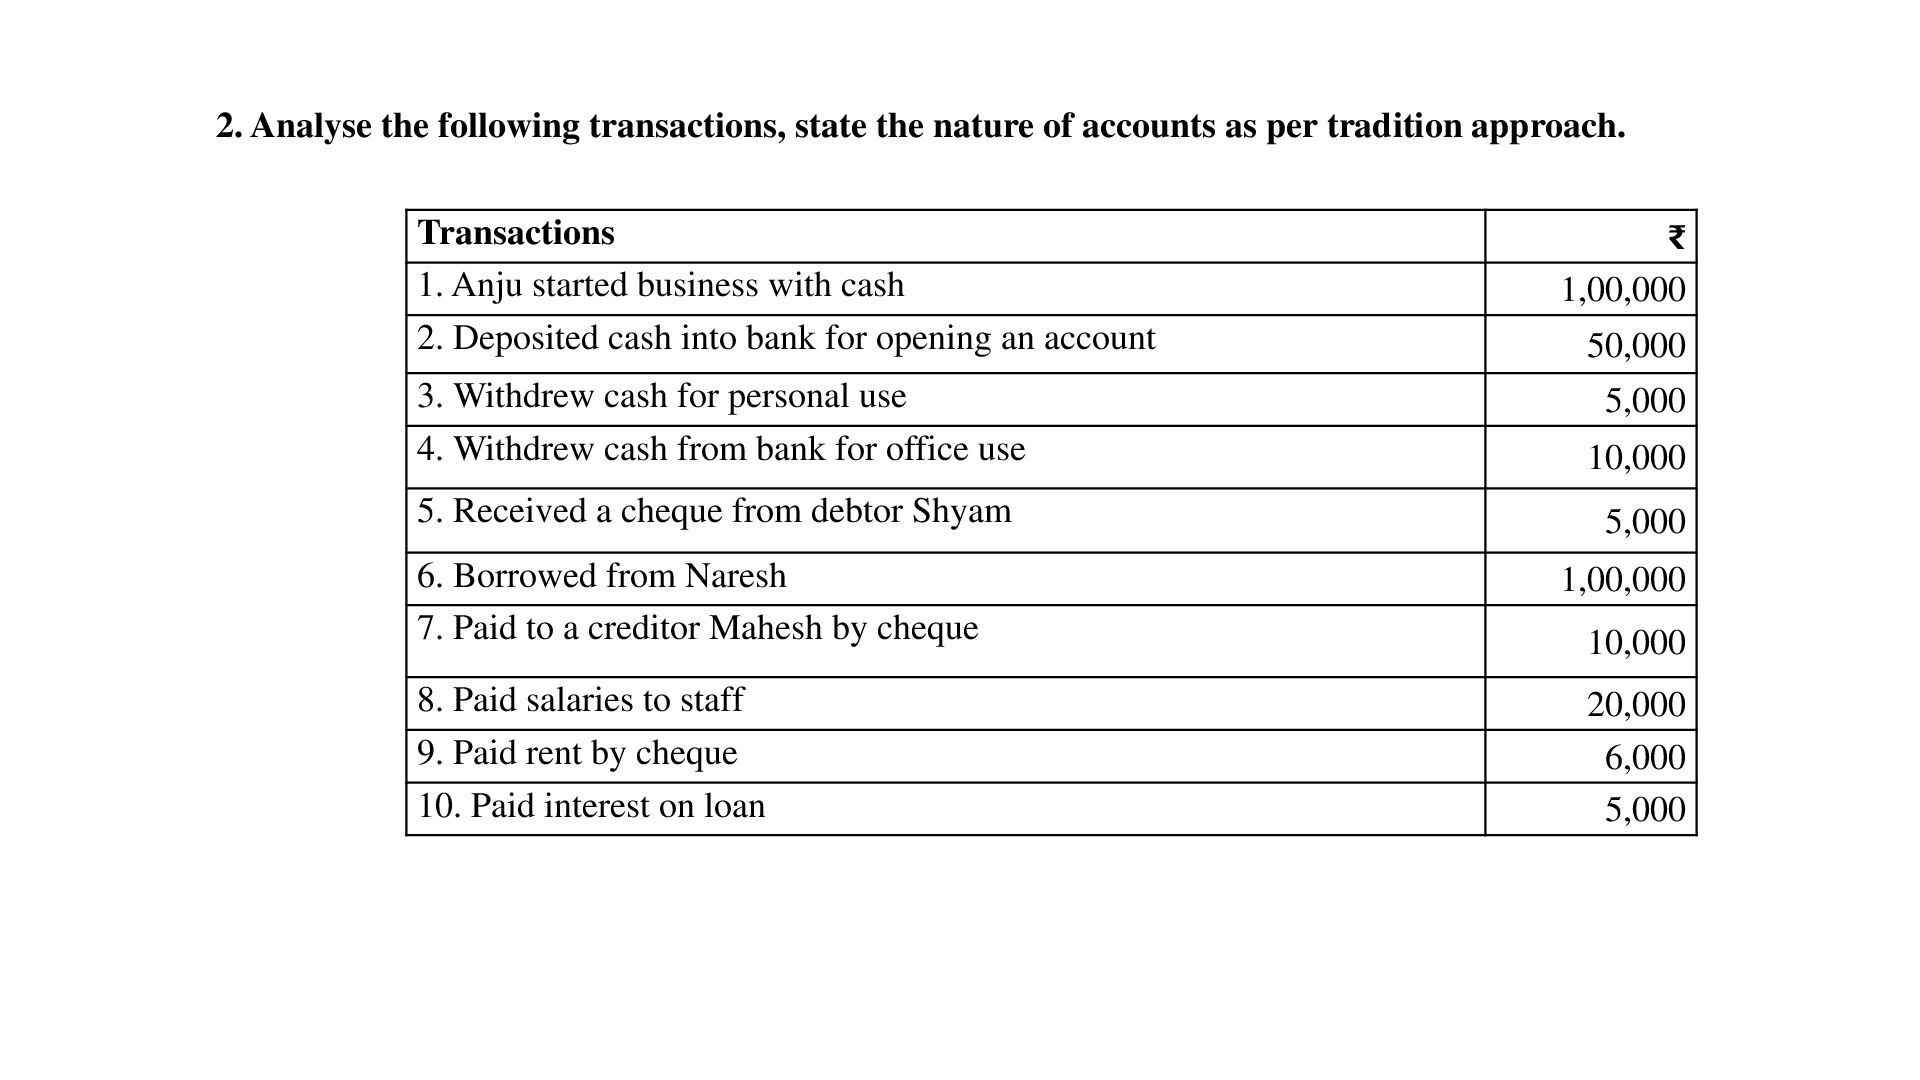
  6. 2. Analyse the following transactions, state the nature of accounts

    as per tradition approach. Transactions 1. Anju started business with cash 2. Deposited cash into bank for opening an account ₹ 1,00,000 50,000 3. Withdrew cash for personal use 4. Withdrew cash from bank for office use 10,000 5. Received a cheque from debtor Shyam 5,000 6. Borrowed from Naresh 7. Paid to a creditor Mahesh by cheque 1,00,000 8. Paid salaries to staff 9. Paid rent by cheque 10. Paid interest on loan 5,000 10,000 20,000 6,000 5,000
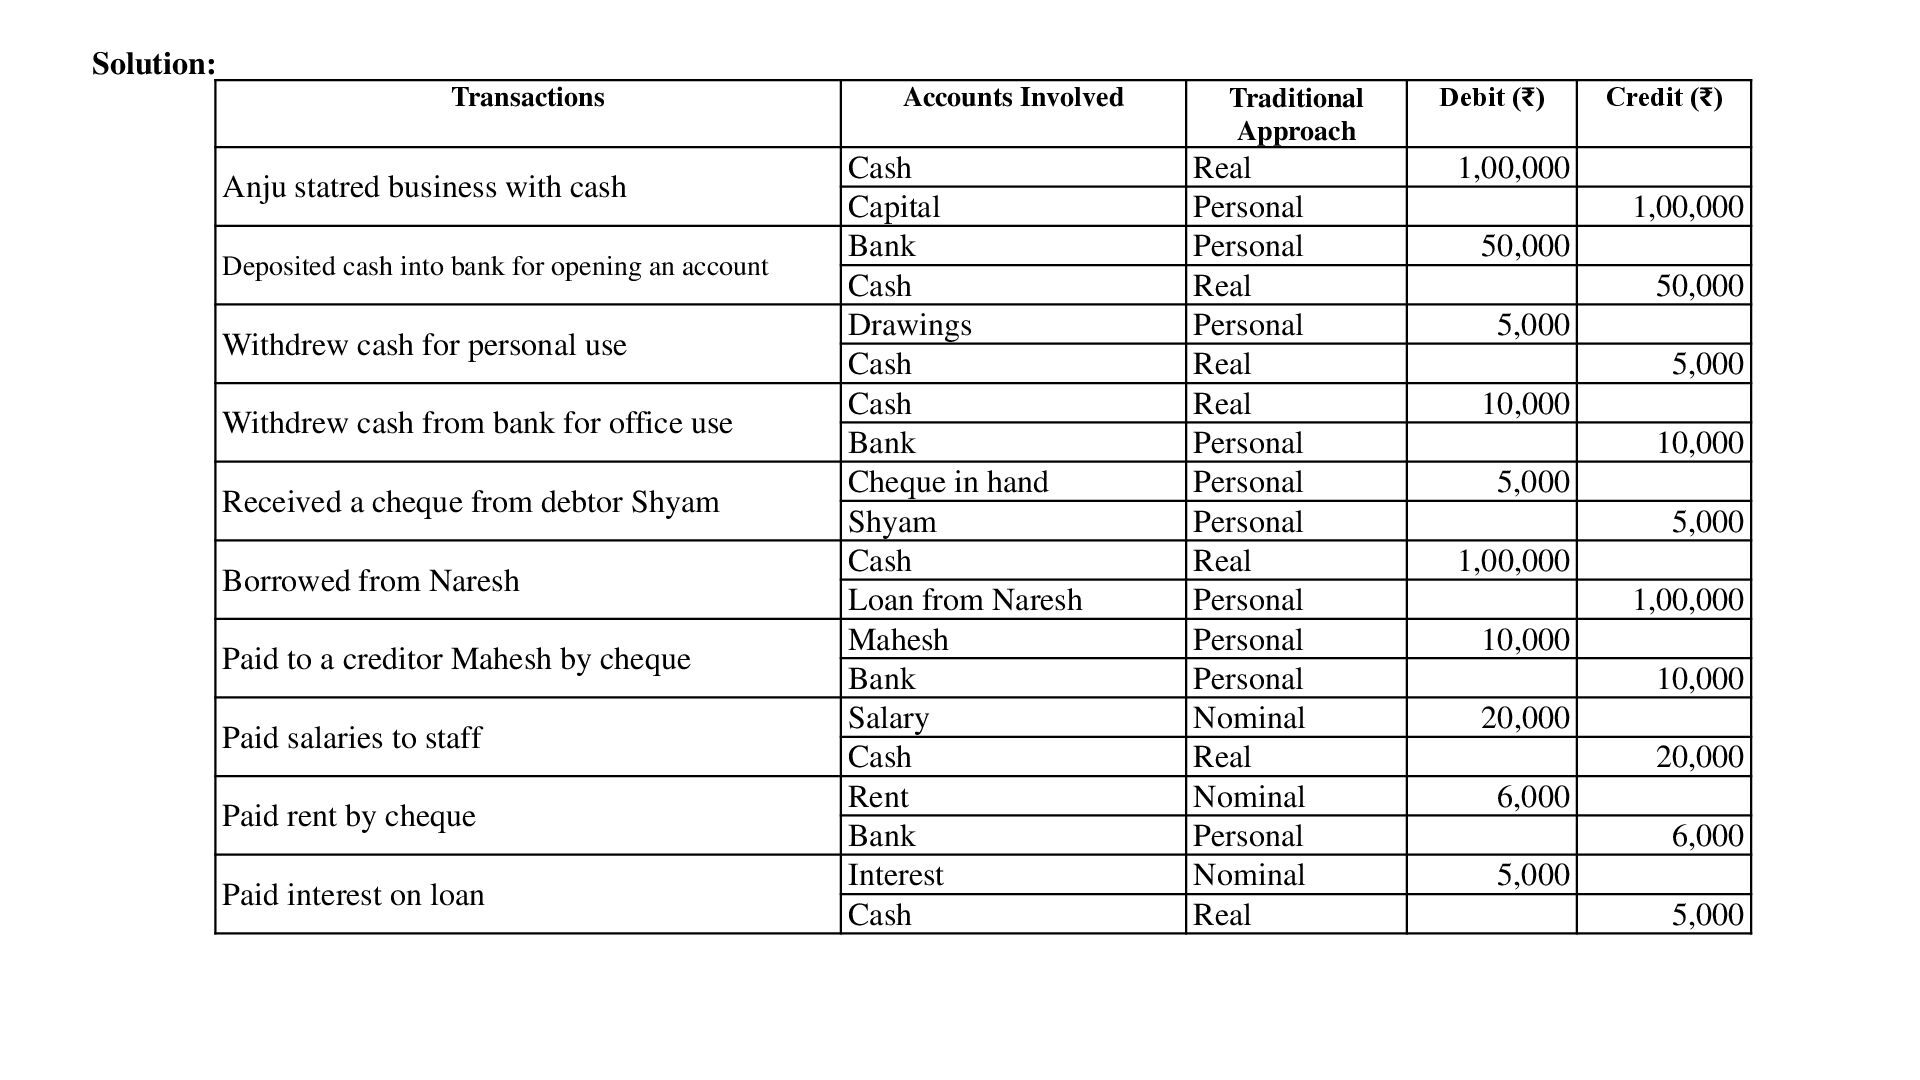
  7. Solution: Transactions Anju statred business with cash Deposited cash into

    bank for opening an account Withdrew cash for personal use Withdrew cash from bank for office use Received a cheque from debtor Shyam Borrowed from Naresh Paid to a creditor Mahesh by cheque Paid salaries to staff Paid rent by cheque Paid interest on loan Accounts Involved Cash Capital Bank Cash Drawings Cash Cash Bank Cheque in hand Shyam Cash Loan from Naresh Mahesh Bank Salary Cash Rent Bank Interest Cash Traditional Approach Real Personal Personal Real Personal Real Real Personal Personal Personal Real Personal Personal Personal Nominal Real Nominal Personal Nominal Real Debit (₹) Credit (₹) 1,00,000 1,00,000 50,000 50,000 5,000 5,000 10,000 10,000 5,000 5,000 1,00,000 1,00,000 10,000 10,000 20,000 20,000 6,000 6,000 5,000 5,000
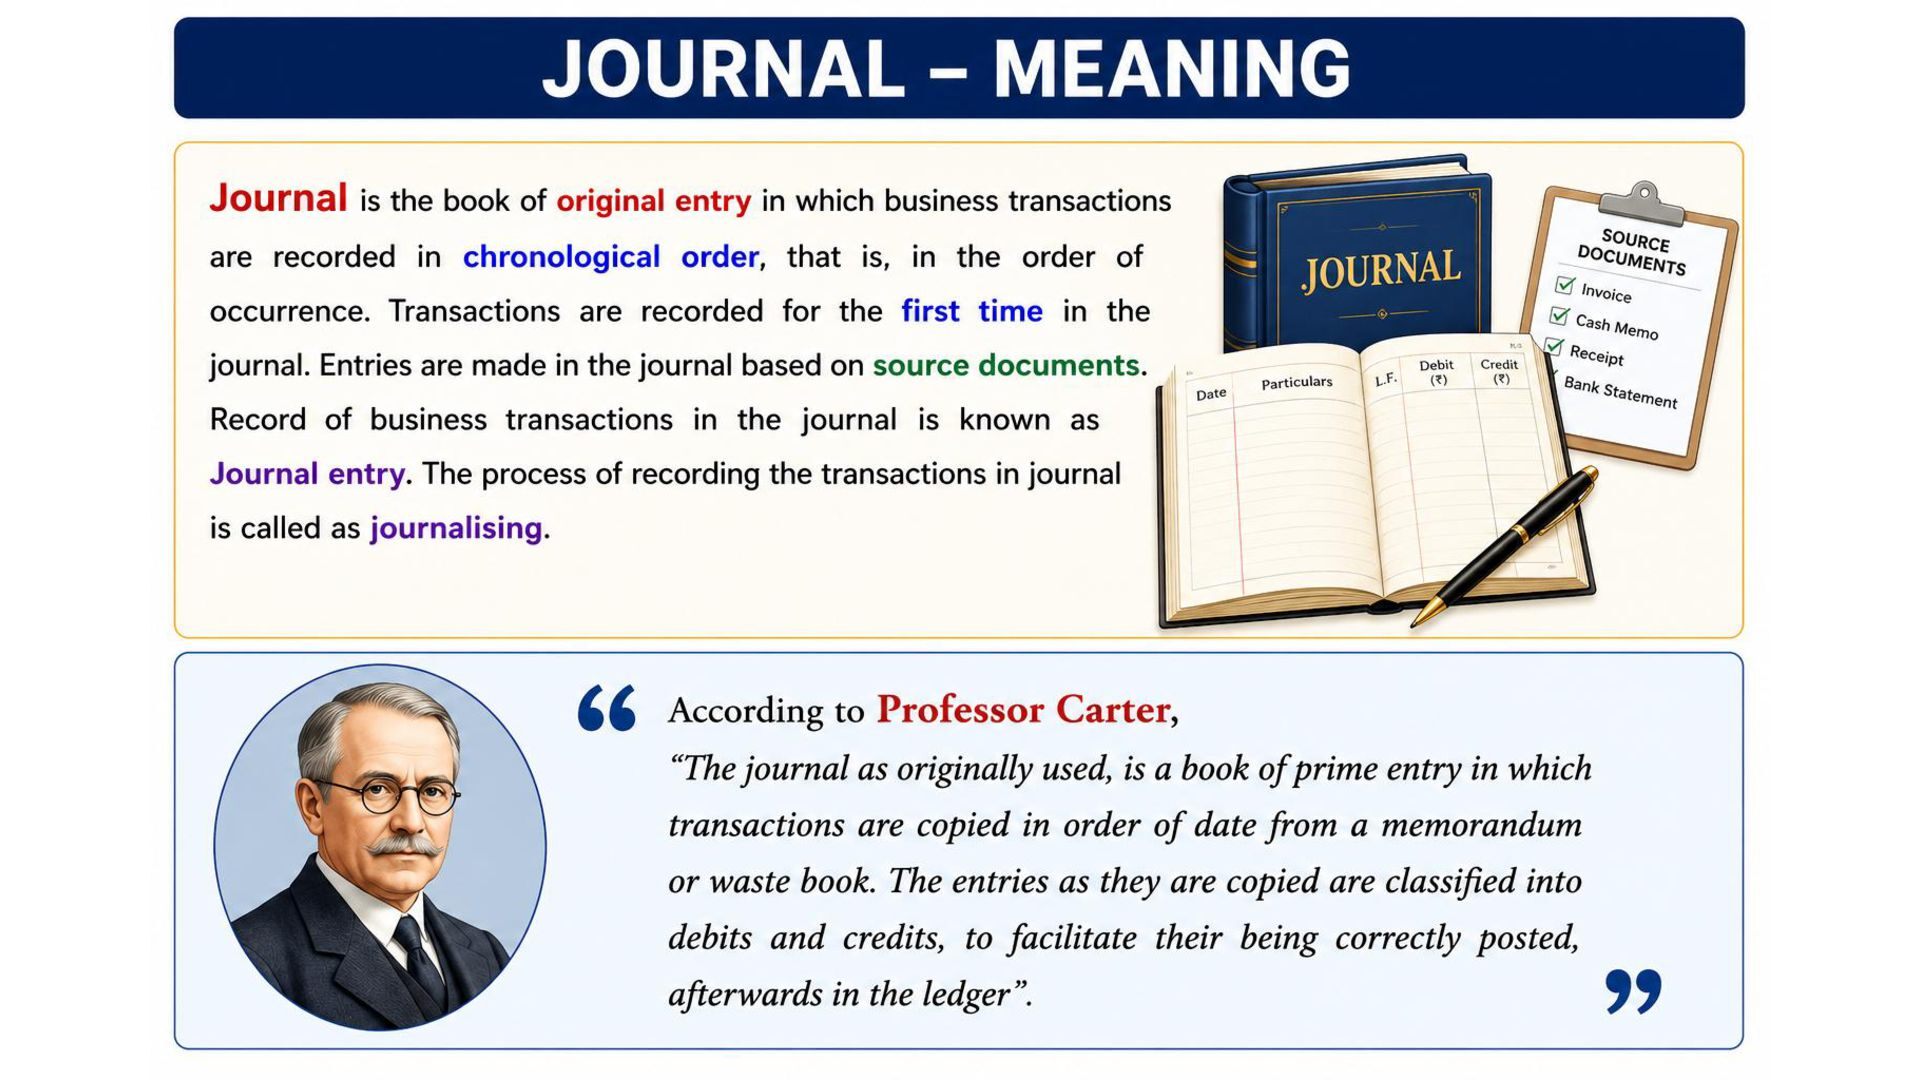
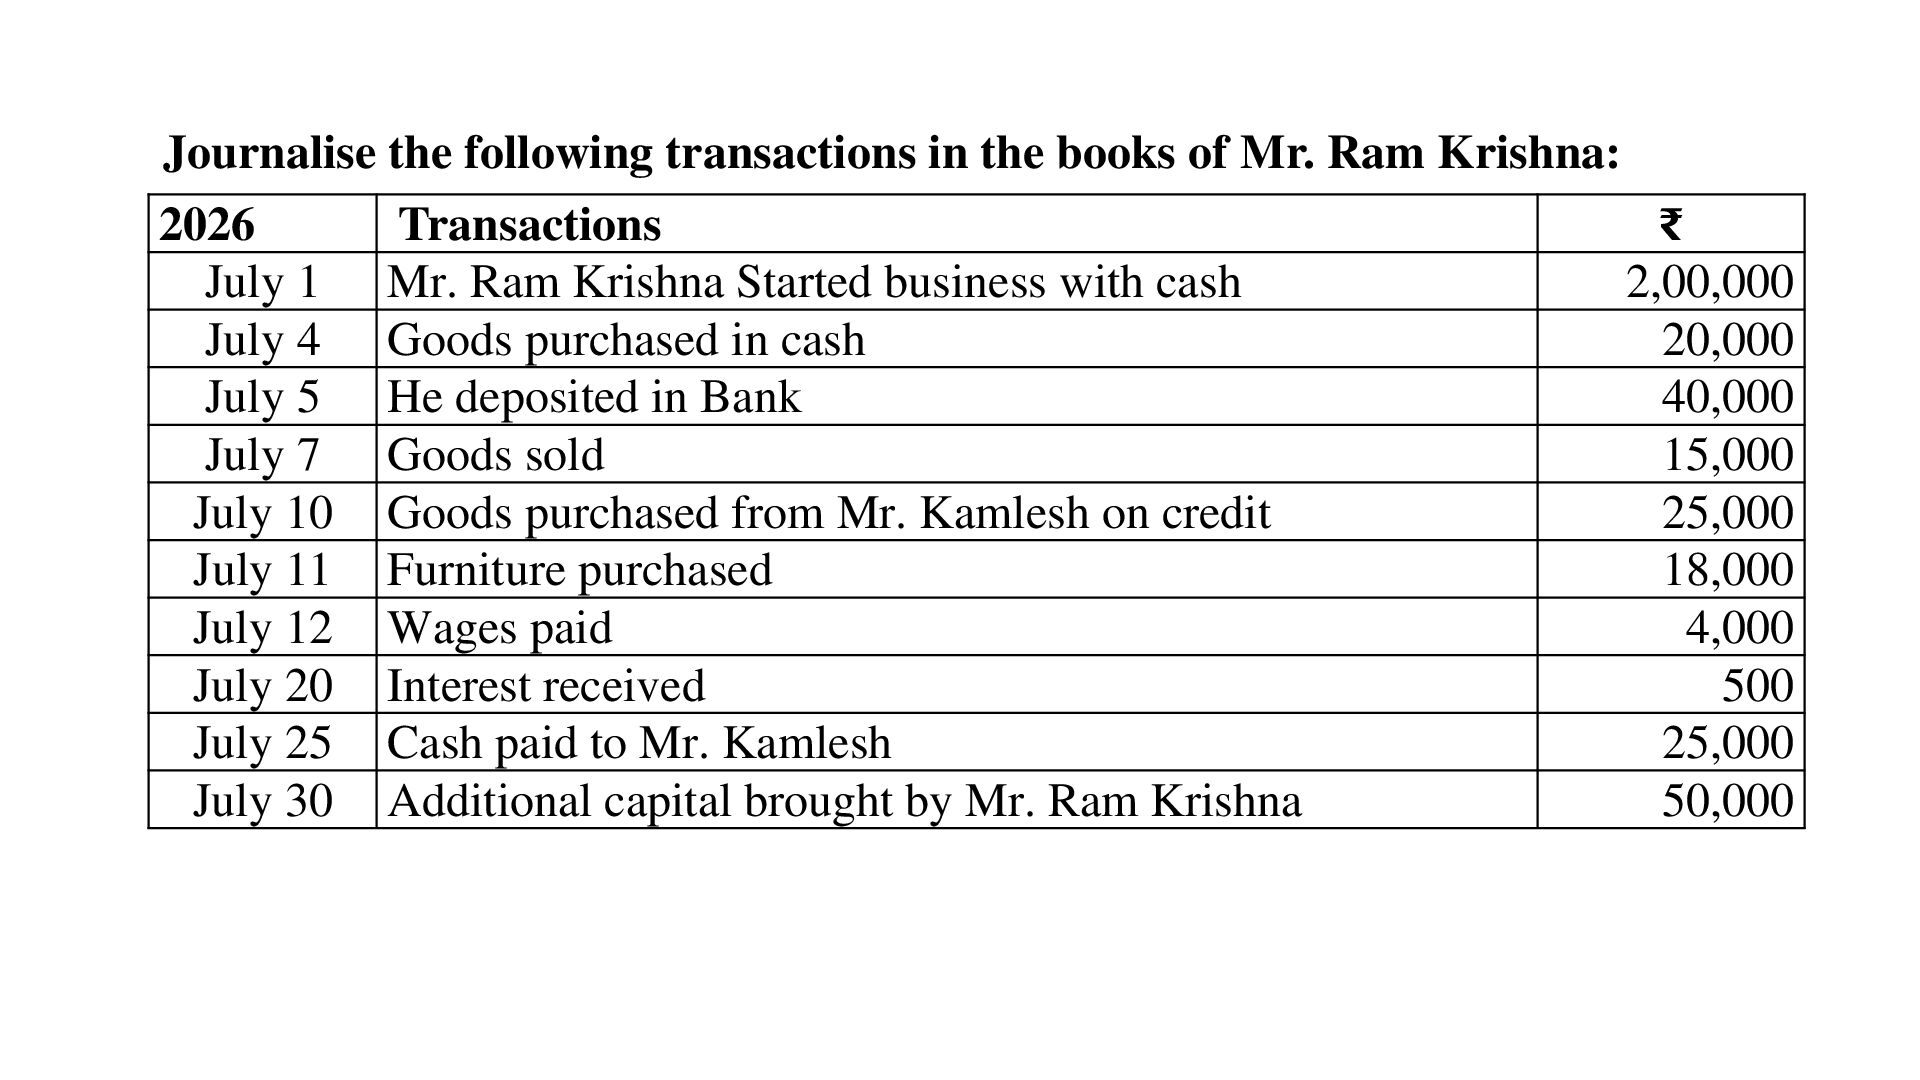
  8. Journalise the following transactions in the books of Mr. Ram

    Krishna: 2026 Transactions ₹ July 1 Mr. Ram Krishna Started business with cash 2,00,000 July 4 Goods purchased in cash 20,000 July 5 He deposited in Bank 40,000 July 7 Goods sold 15,000 July 10 Goods purchased from Mr. Kamlesh on credit 25,000 July 11 Furniture purchased 18,000 July 12 Wages paid 4,000 July 20 Interest received 500 July 25 Cash paid to Mr. Kamlesh 25,000 July 30 Additional capital brought by Mr. Ram Krishna 50,000
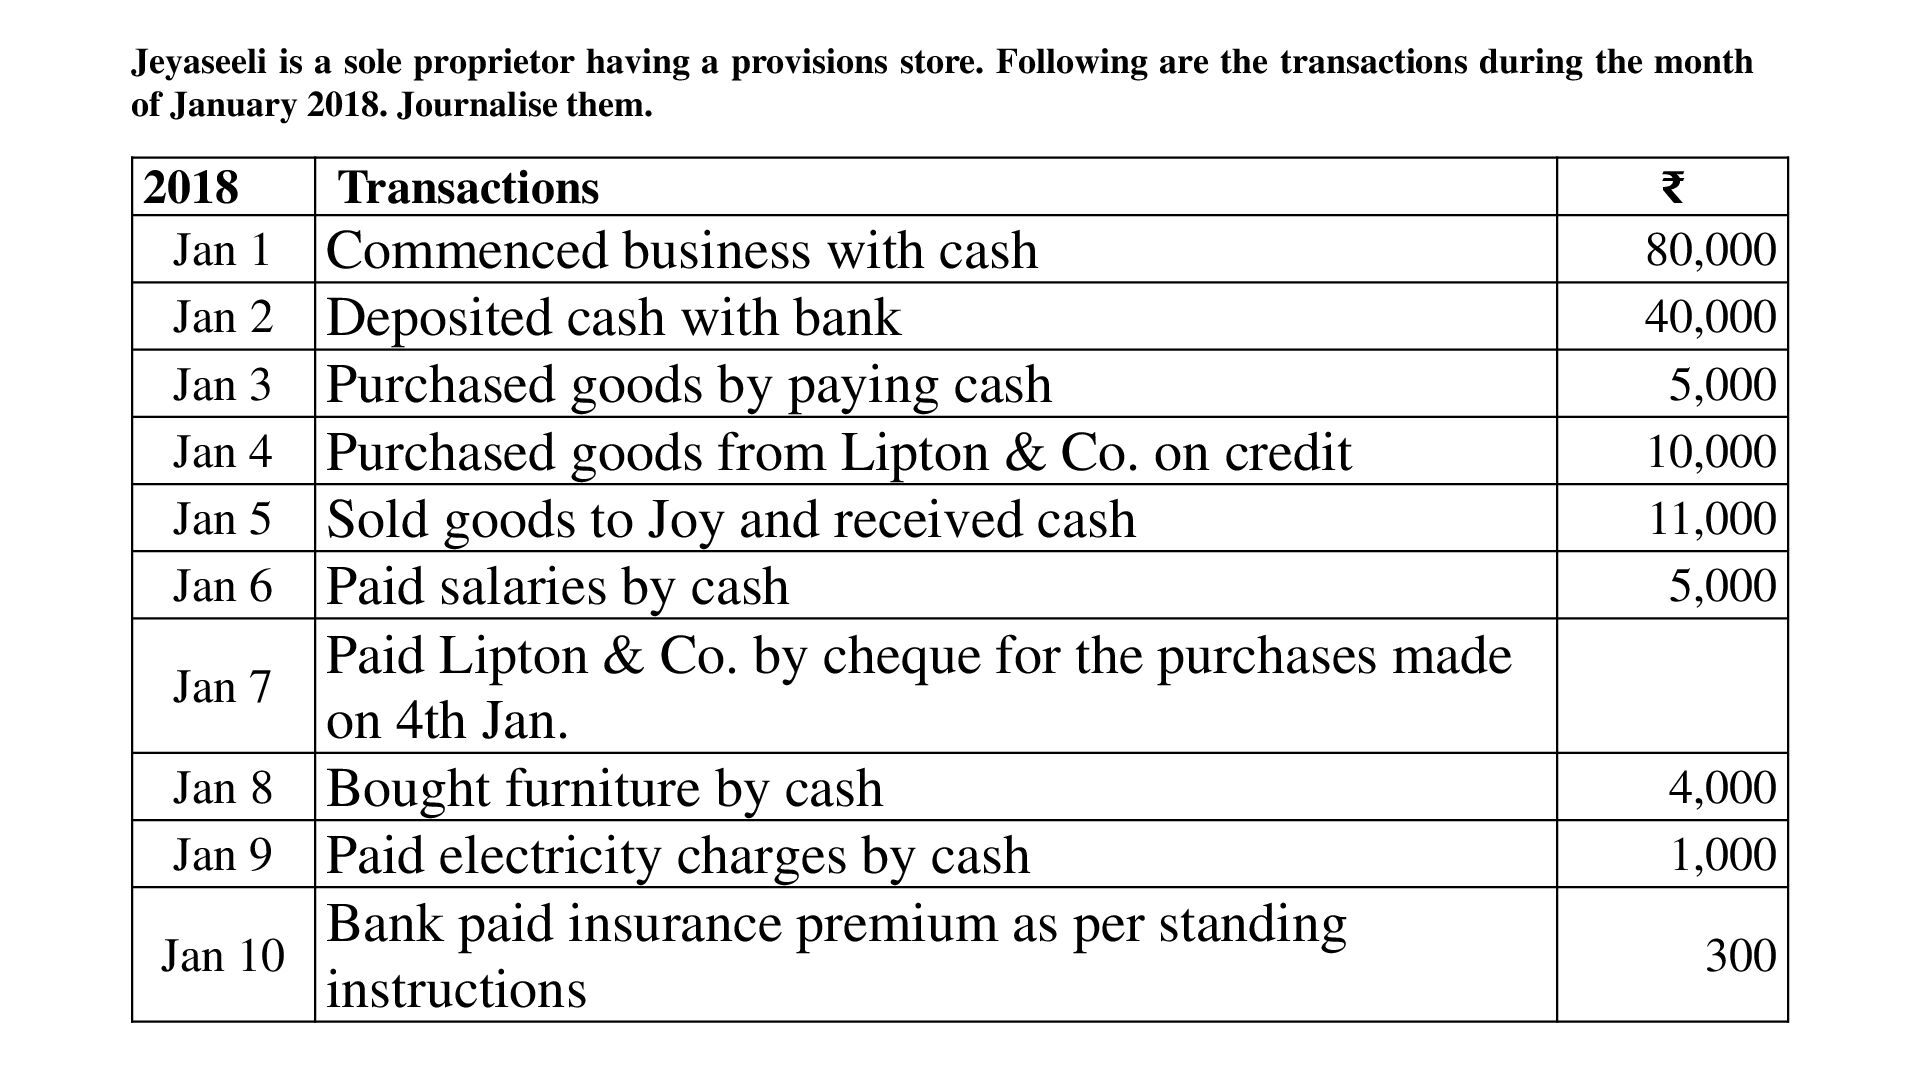
  9. Jeyaseeli is a sole proprietor having a provisions store. Following

    are the transactions during the month of January 2018. Journalise them. 2018 Jan 1 Jan 2 Jan 3 Jan 4 Jan 5 Jan 6 Jan 7 Jan 8 Jan 9 Jan 10 Transactions Commenced business with cash Deposited cash with bank Purchased goods by paying cash Purchased goods from Lipton & Co. on credit Sold goods to Joy and received cash Paid salaries by cash Paid Lipton & Co. by cheque for the purchases made on 4th Jan. Bought furniture by cash Paid electricity charges by cash Bank paid insurance premium as per standing instructions ₹ 80,000 40,000 5,000 10,000 11,000 5,000 4,000 1,000 300
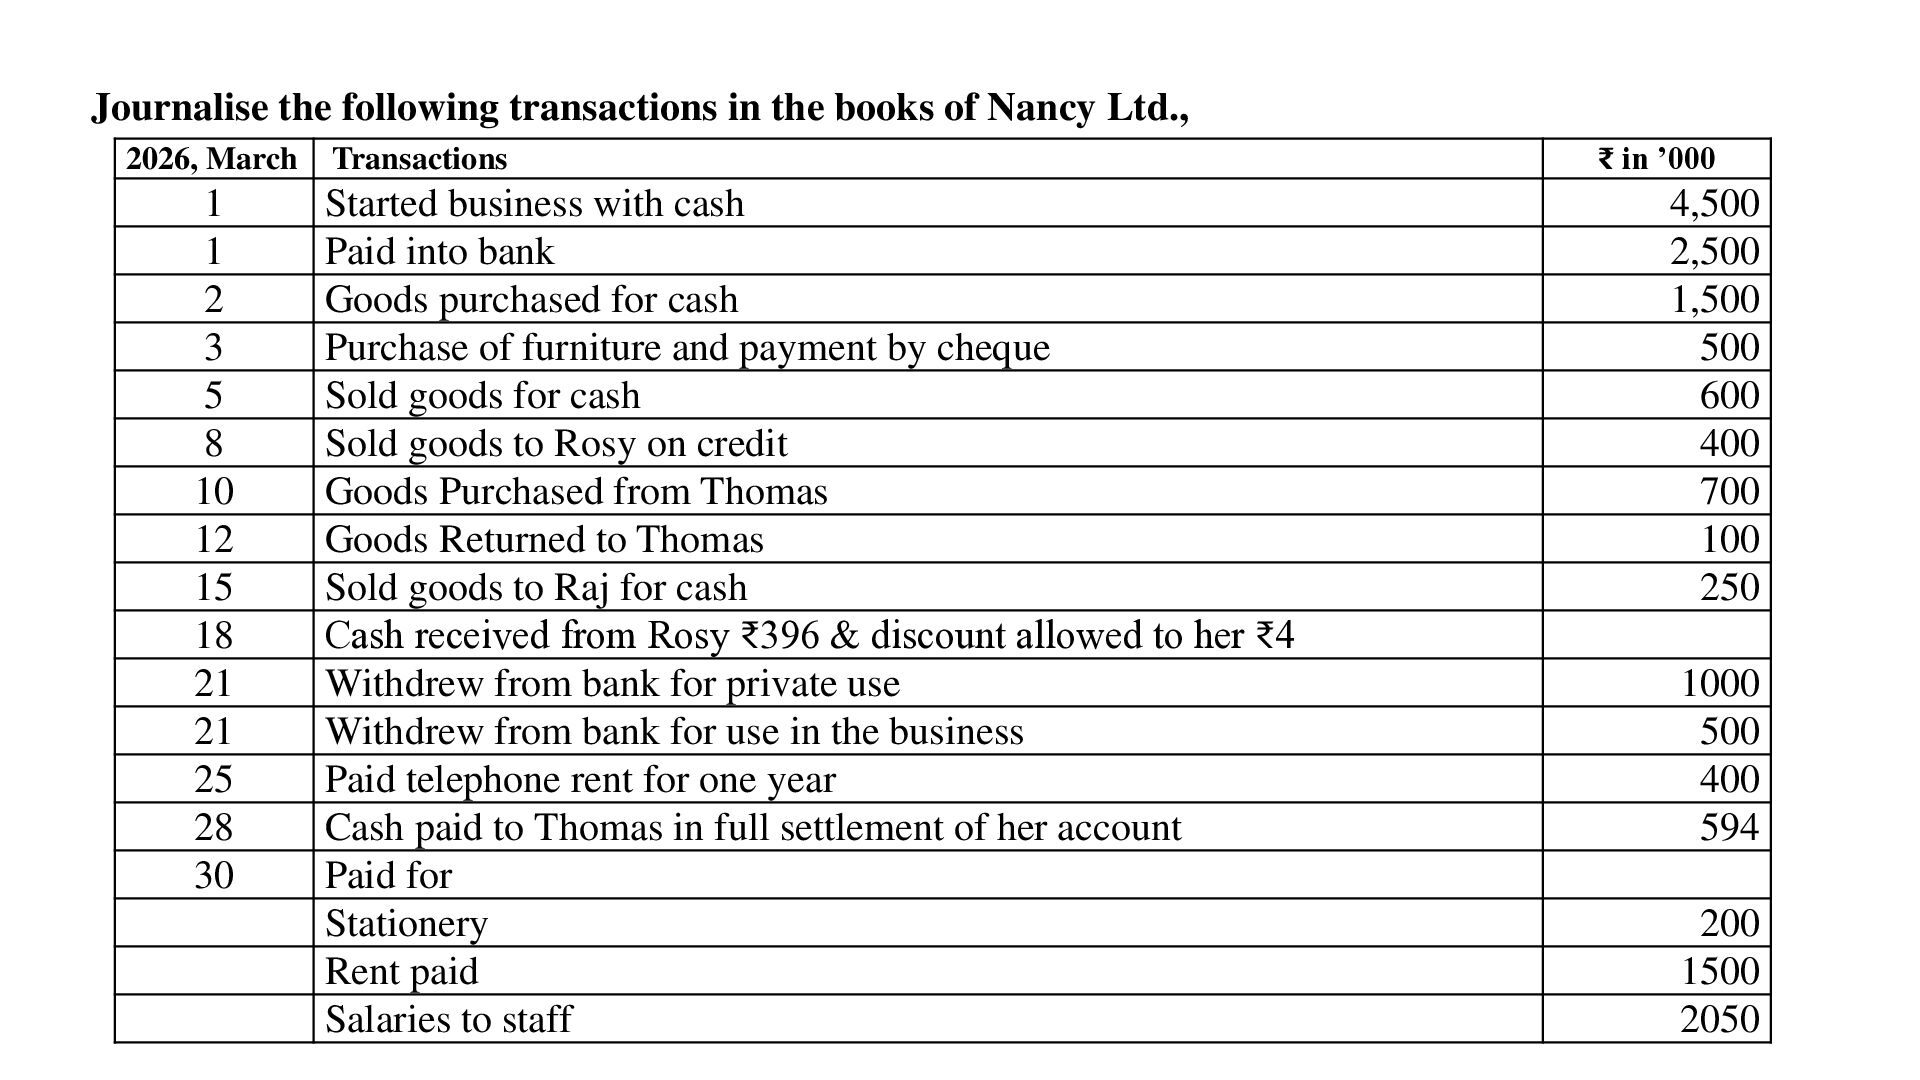
  10. Journalise the following transactions in the books of Nancy Ltd.,

    2026, March 1 1 2 3 5 8 10 12 15 18 21 21 25 28 30 Transactions Started business with cash Paid into bank Goods purchased for cash Purchase of furniture and payment by cheque Sold goods for cash Sold goods to Rosy on credit Goods Purchased from Thomas Goods Returned to Thomas Sold goods to Raj for cash Cash received from Rosy ₹396 & discount allowed to her ₹4 Withdrew from bank for private use Withdrew from bank for use in the business Paid telephone rent for one year Cash paid to Thomas in full settlement of her account Paid for Stationery Rent paid Salaries to staff ₹ in ’000 4,500 2,500 1,500 500 600 400 700 100 250 1000 500 400 594 200 1500 2050
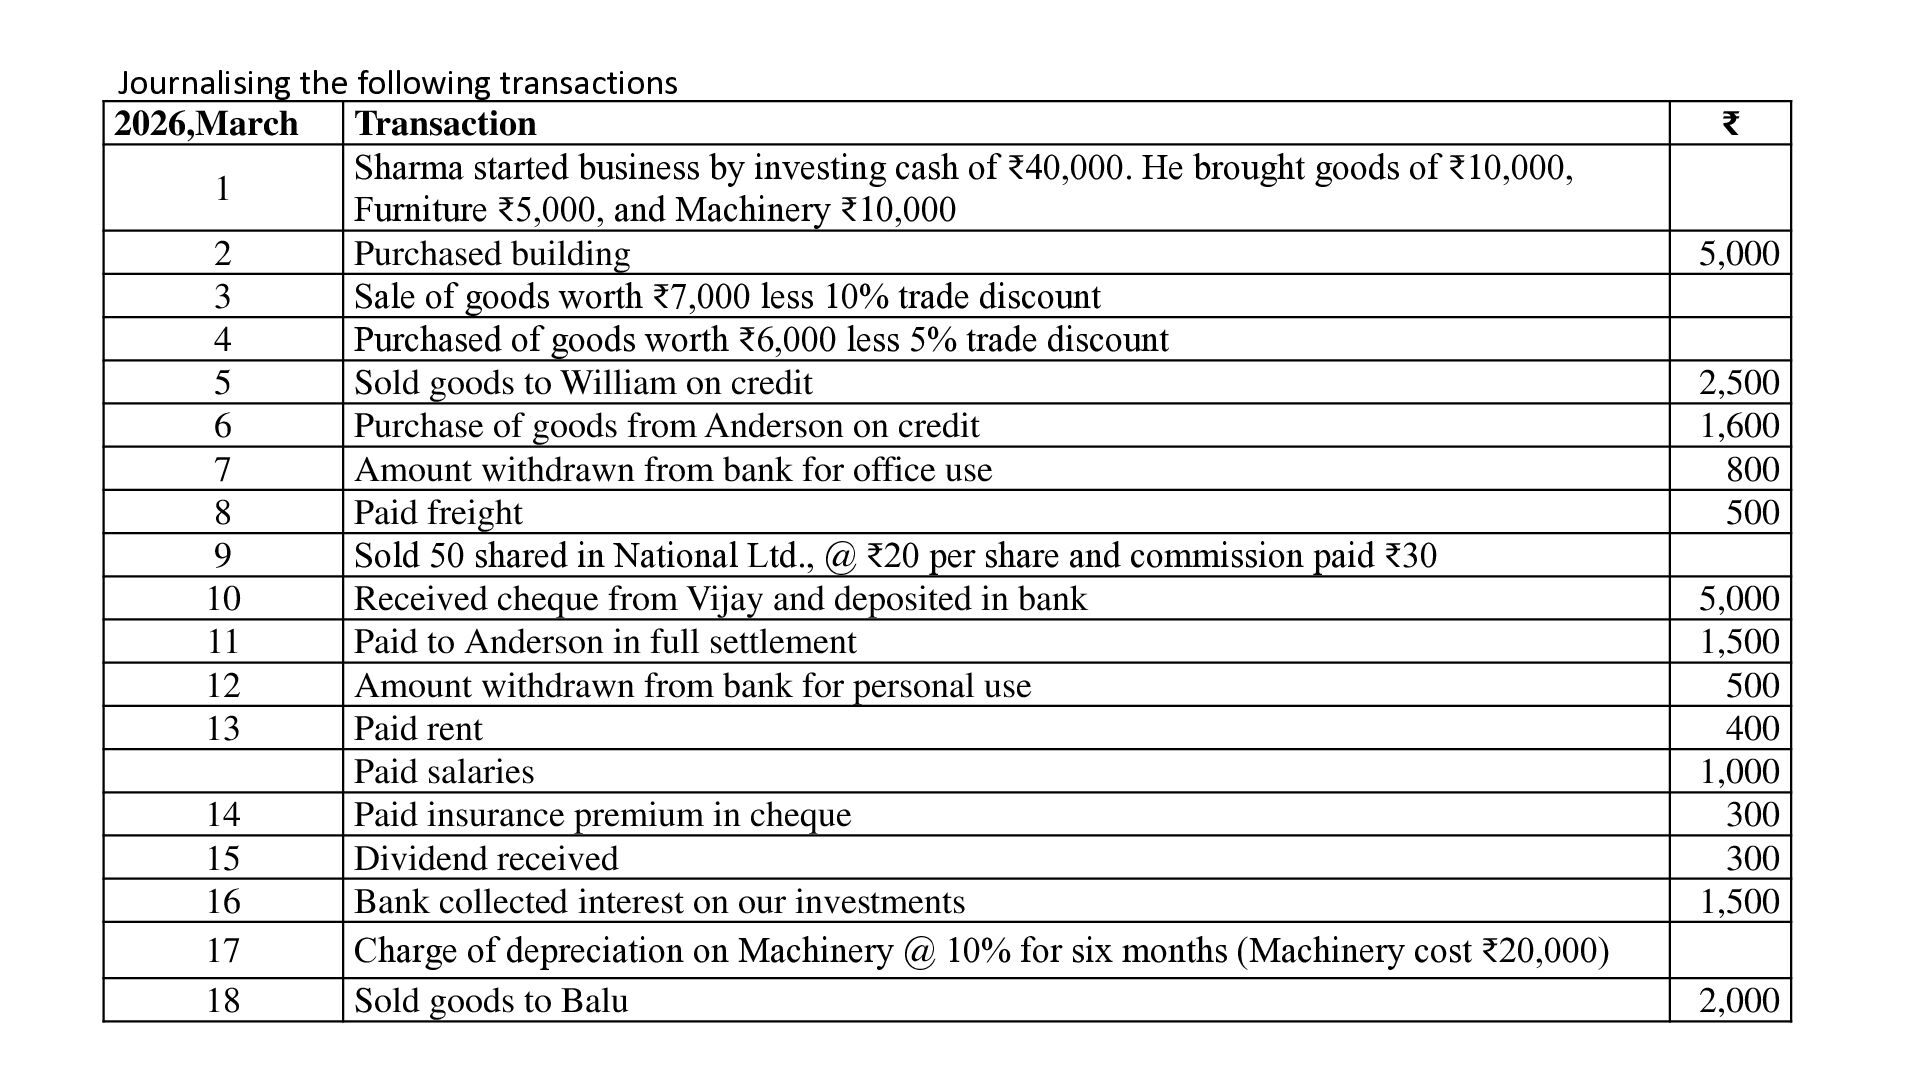
  11. Journalising the following transactions 2026,March Transaction Sharma started business by

    investing cash of ₹40,000. He brought goods of ₹10,000, 1 Furniture ₹5,000, and Machinery ₹10,000 2 Purchased building 3 Sale of goods worth ₹7,000 less 10% trade discount 4 Purchased of goods worth ₹6,000 less 5% trade discount 5 Sold goods to William on credit 6 Purchase of goods from Anderson on credit 7 Amount withdrawn from bank for office use 8 Paid freight 9 Sold 50 shared in National Ltd., @ ₹20 per share and commission paid ₹30 10 Received cheque from Vijay and deposited in bank 11 Paid to Anderson in full settlement 12 Amount withdrawn from bank for personal use 13 Paid rent Paid salaries 14 Paid insurance premium in cheque 15 Dividend received 16 Bank collected interest on our investments 17 Charge of depreciation on Machinery @ 10% for six months (Machinery cost ₹20,000) 18 Sold goods to Balu ₹ 5,000 2,500 1,600 800 500 5,000 1,500 500 400 1,000 300 300 1,500 2,000
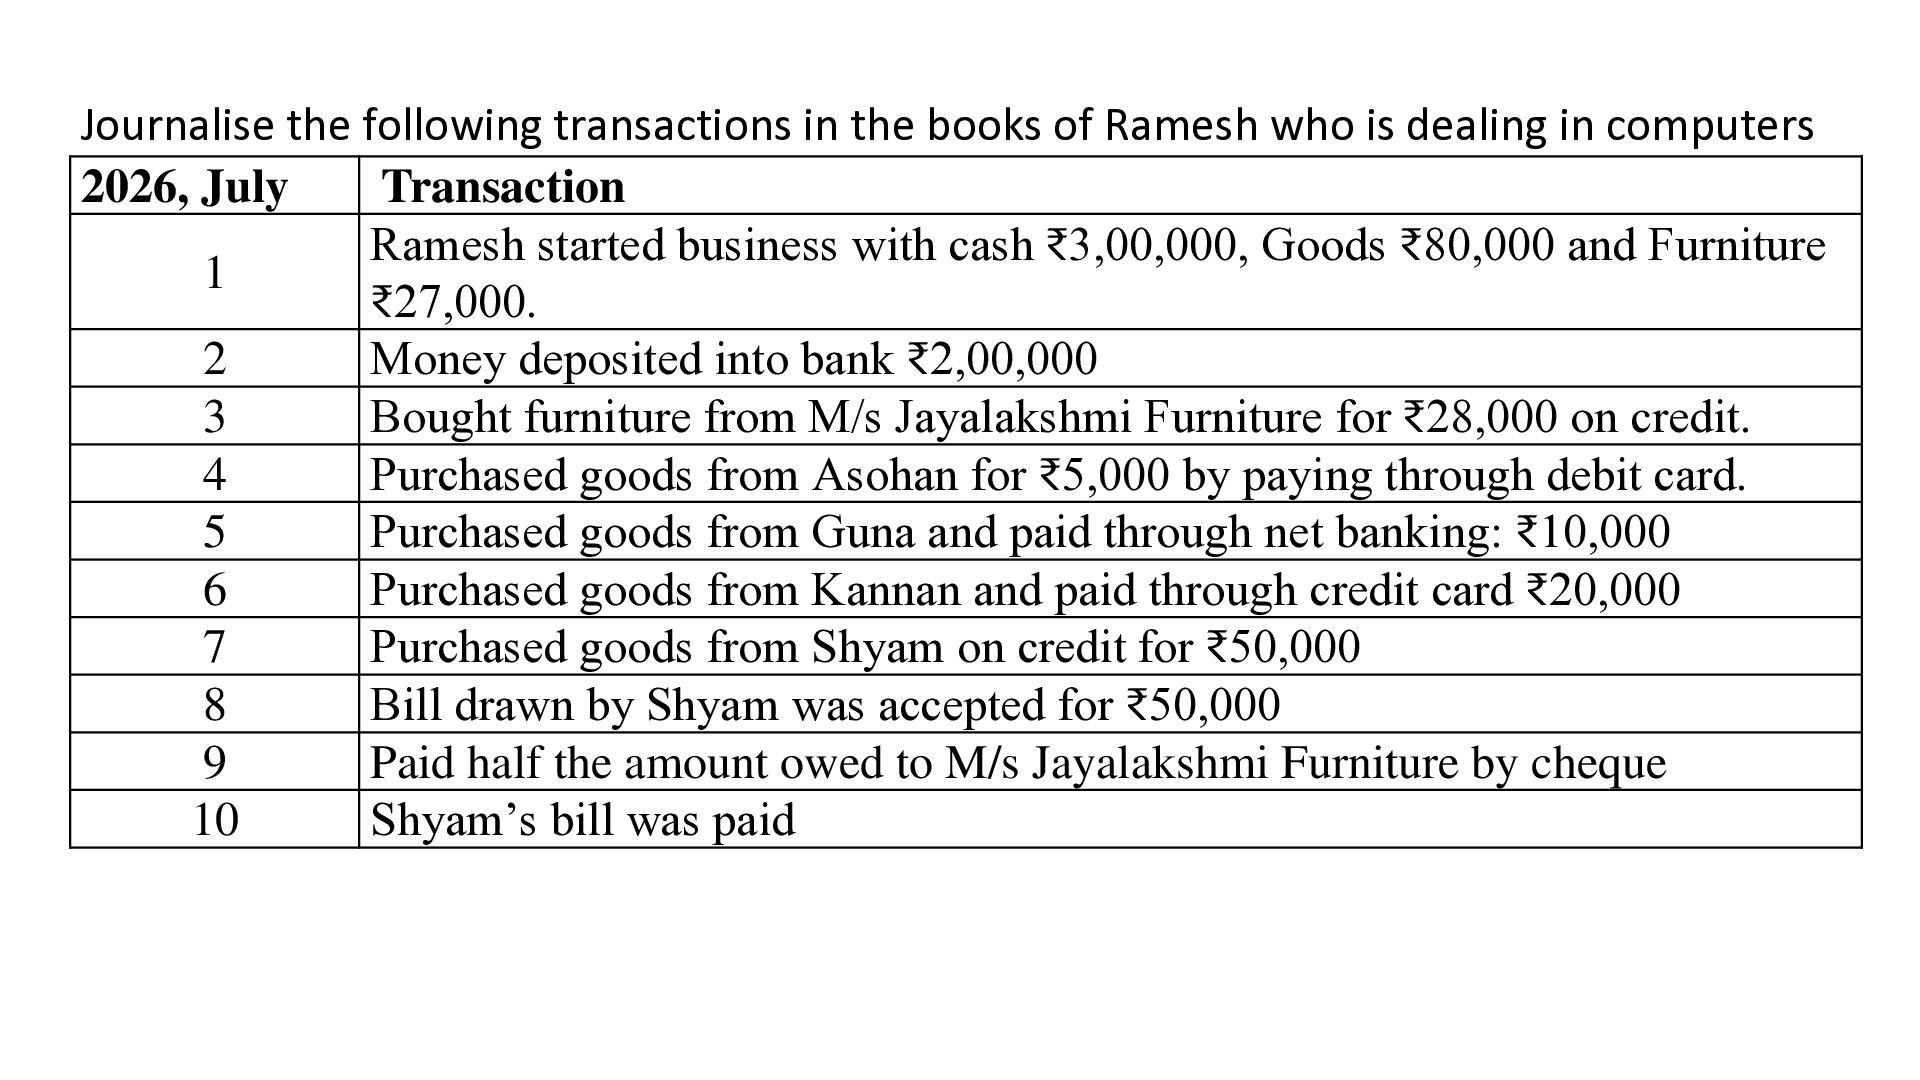
  12. Journalise the following transactions in the books of Ramesh who

    is dealing in computers 2026, July Transaction Ramesh started business with cash ₹3,00,000, Goods ₹80,000 and Furniture 1 ₹27,000. 2 Money deposited into bank ₹2,00,000 3 Bought furniture from M/s Jayalakshmi Furniture for ₹28,000 on credit. 4 Purchased goods from Asohan for ₹5,000 by paying through debit card. 5 Purchased goods from Guna and paid through net banking: ₹10,000 6 Purchased goods from Kannan and paid through credit card ₹20,000 7 Purchased goods from Shyam on credit for ₹50,000 8 Bill drawn by Shyam was accepted for ₹50,000 9 Paid half the amount owed to M/s Jayalakshmi Furniture by cheque 10 Shyam’s bill was paid
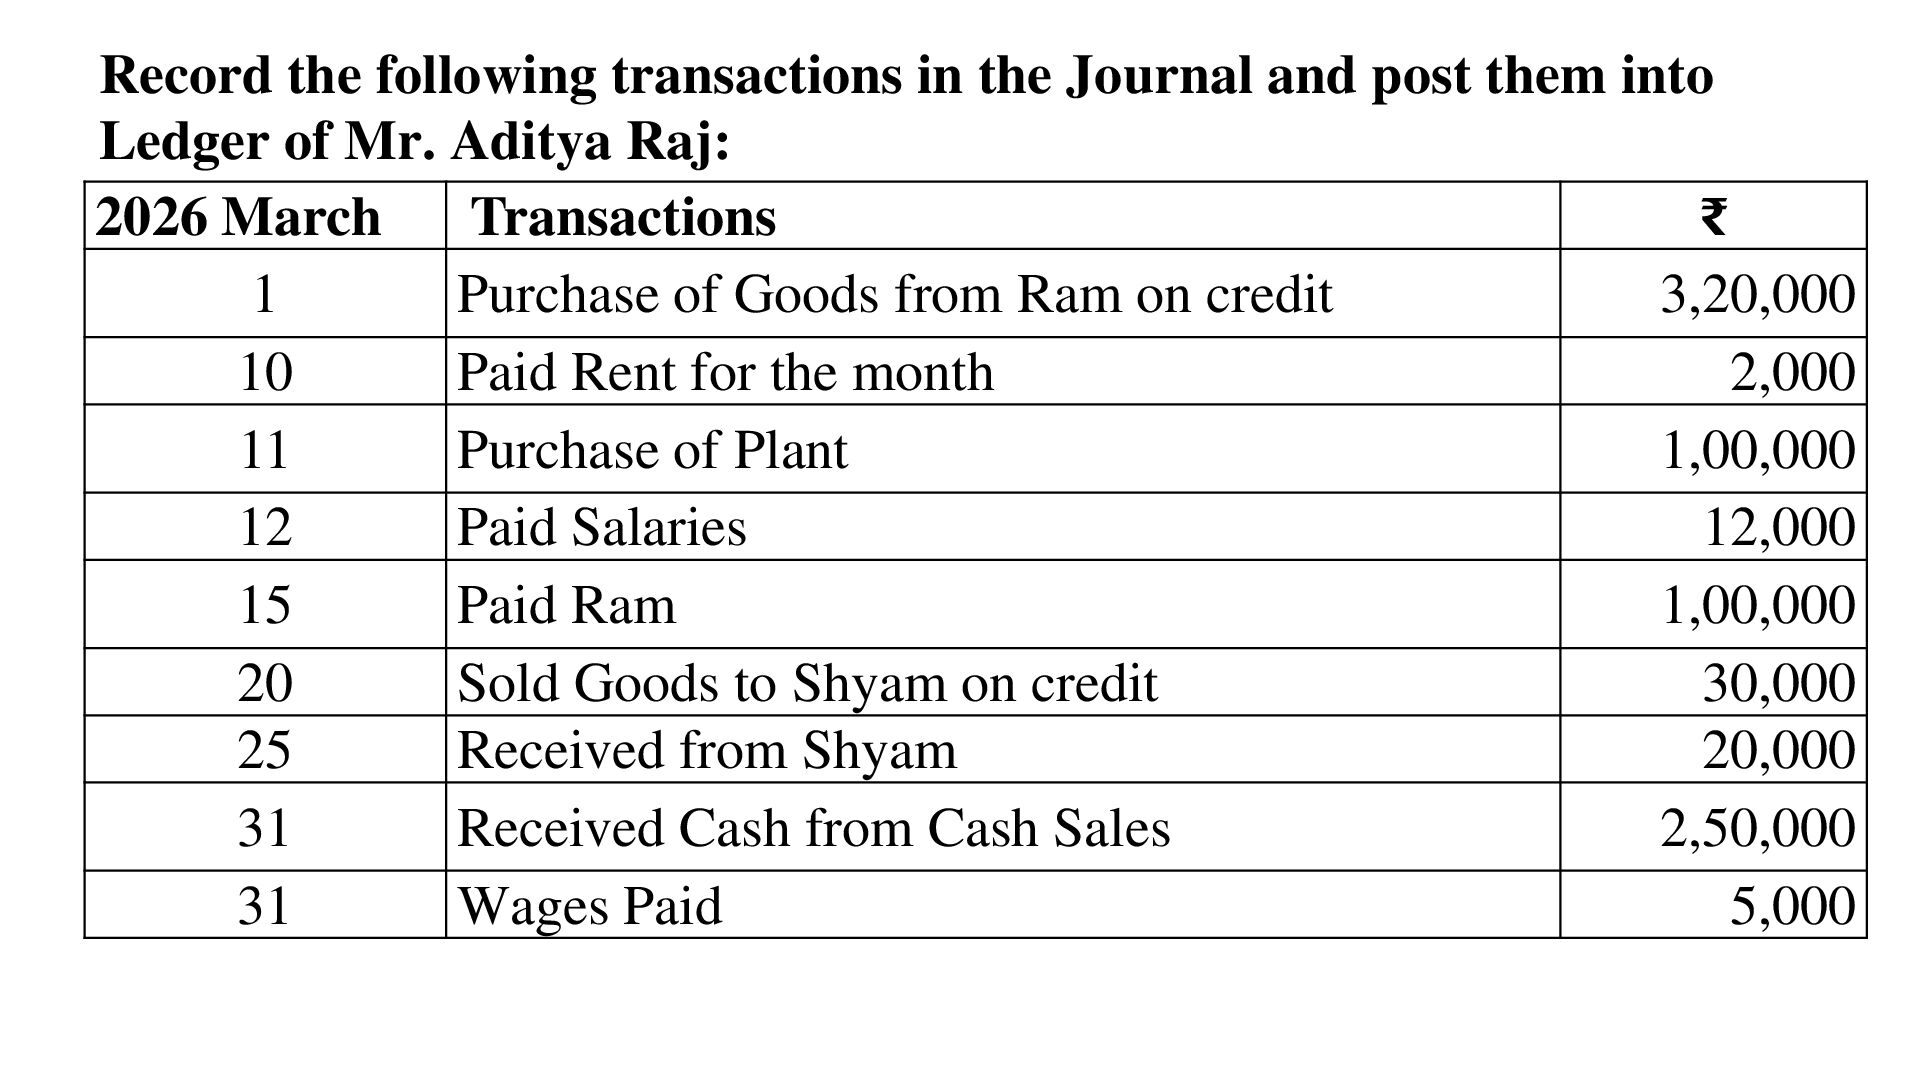
  13. Record the following transactions in the Journal and post them

    into Ledger of Mr. Aditya Raj: 2026 March Transactions ₹ 1 Purchase of Goods from Ram on credit 3,20,000 10 Paid Rent for the month 2,000 11 Purchase of Plant 1,00,000 12 Paid Salaries 12,000 15 Paid Ram 1,00,000 20 Sold Goods to Shyam on credit 30,000 25 Received from Shyam 20,000 31 Received Cash from Cash Sales 2,50,000 31 Wages Paid 5,000
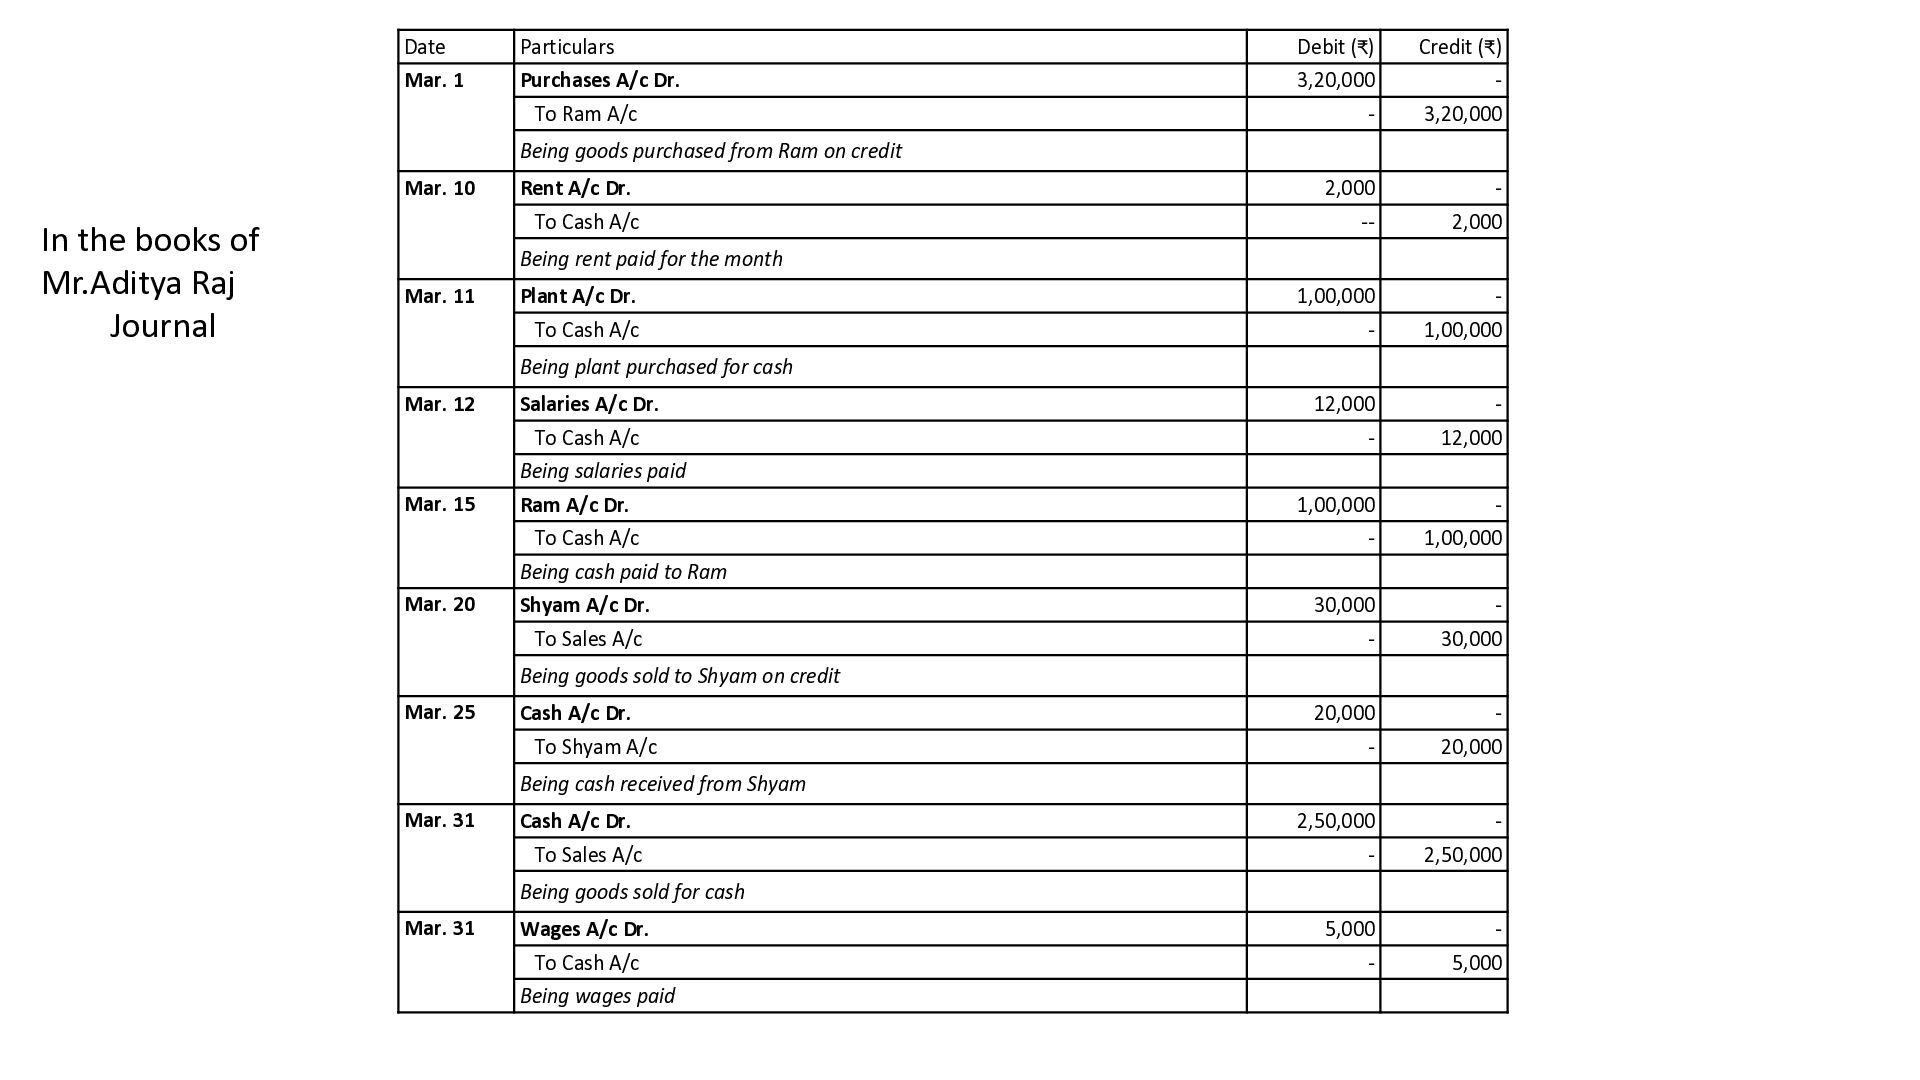
  14. Date Mar. 1 Particulars Debit (₹) Credit (₹) Purchases A/c

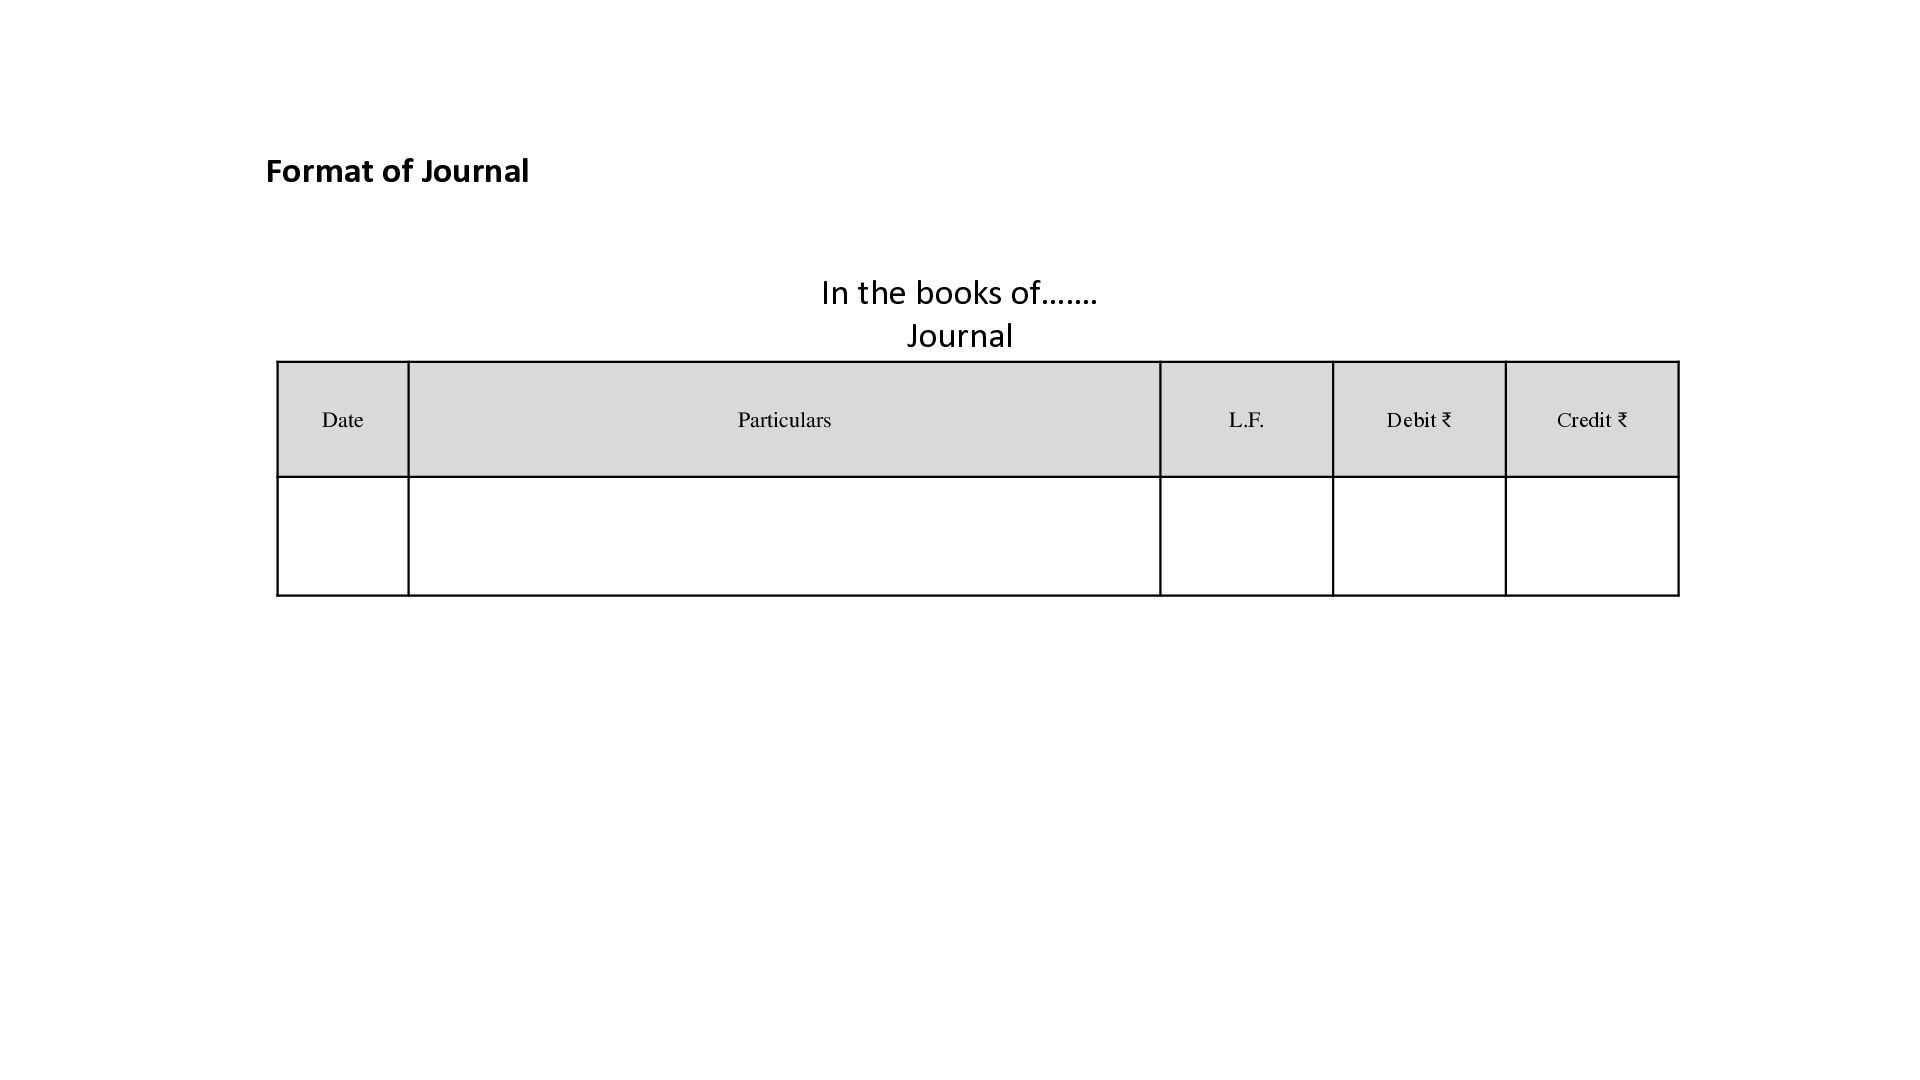
    Dr. 3,20,000 - - 3,20,000 Rent A/c Dr. 2,000 - To Cash A/c -- 2,000 Plant A/c Dr. 1,00,000 - To Cash A/c - 1,00,000 12,000 - - 12,000 Ram A/c Dr. 1,00,000 - To Cash A/c - 1,00,000 Shyam A/c Dr. 30,000 - To Sales A/c - 30,000 20,000 - - 20,000 Cash A/c Dr. 2,50,000 - To Sales A/c - 2,50,000 Wages A/c Dr. 5,000 - To Cash A/c - 5,000 To Ram A/c Being goods purchased from Ram on credit Mar. 10 In the books of Mr.Aditya Raj Journal Being rent paid for the month Mar. 11 Being plant purchased for cash Mar. 12 Salaries A/c Dr. To Cash A/c Being salaries paid Mar. 15 Being cash paid to Ram Mar. 20 Being goods sold to Shyam on credit Mar. 25 Cash A/c Dr. To Shyam A/c Being cash received from Shyam Mar. 31 Being goods sold for cash Mar. 31 Being wages paid
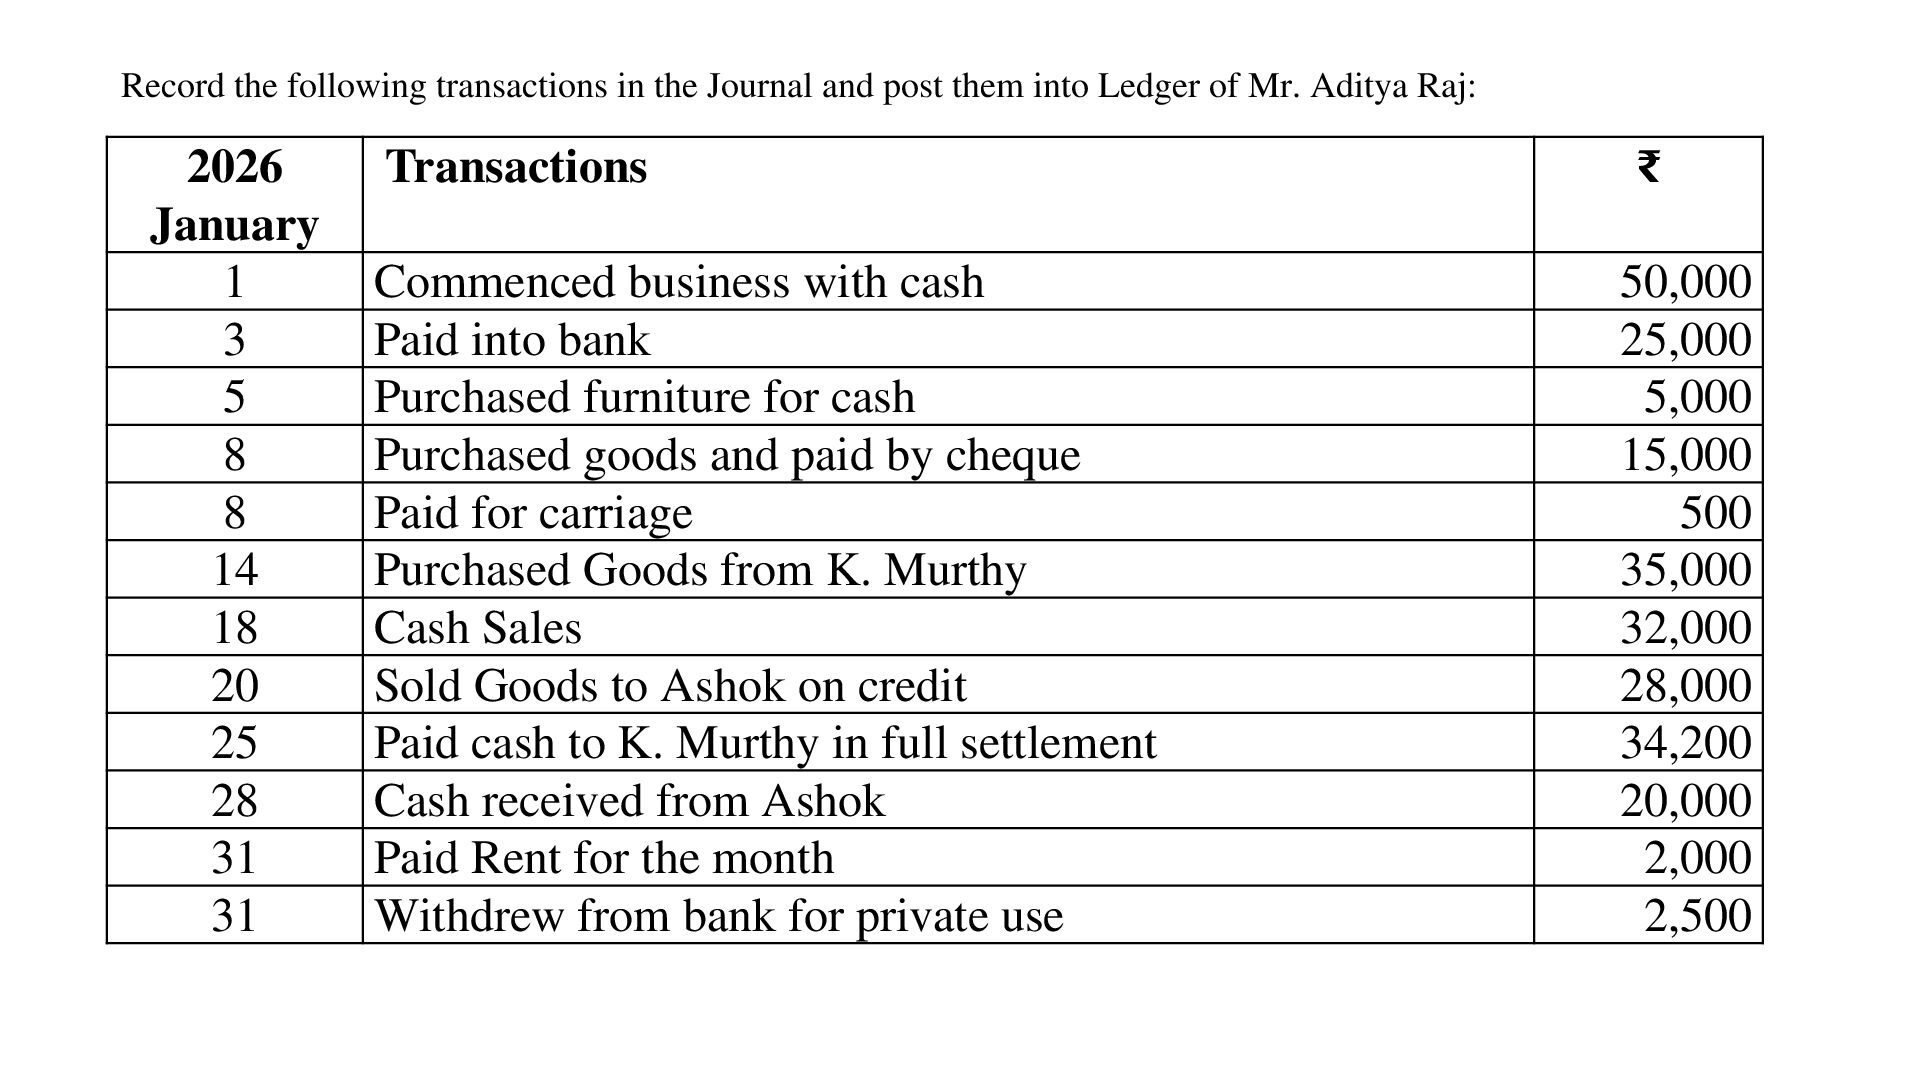
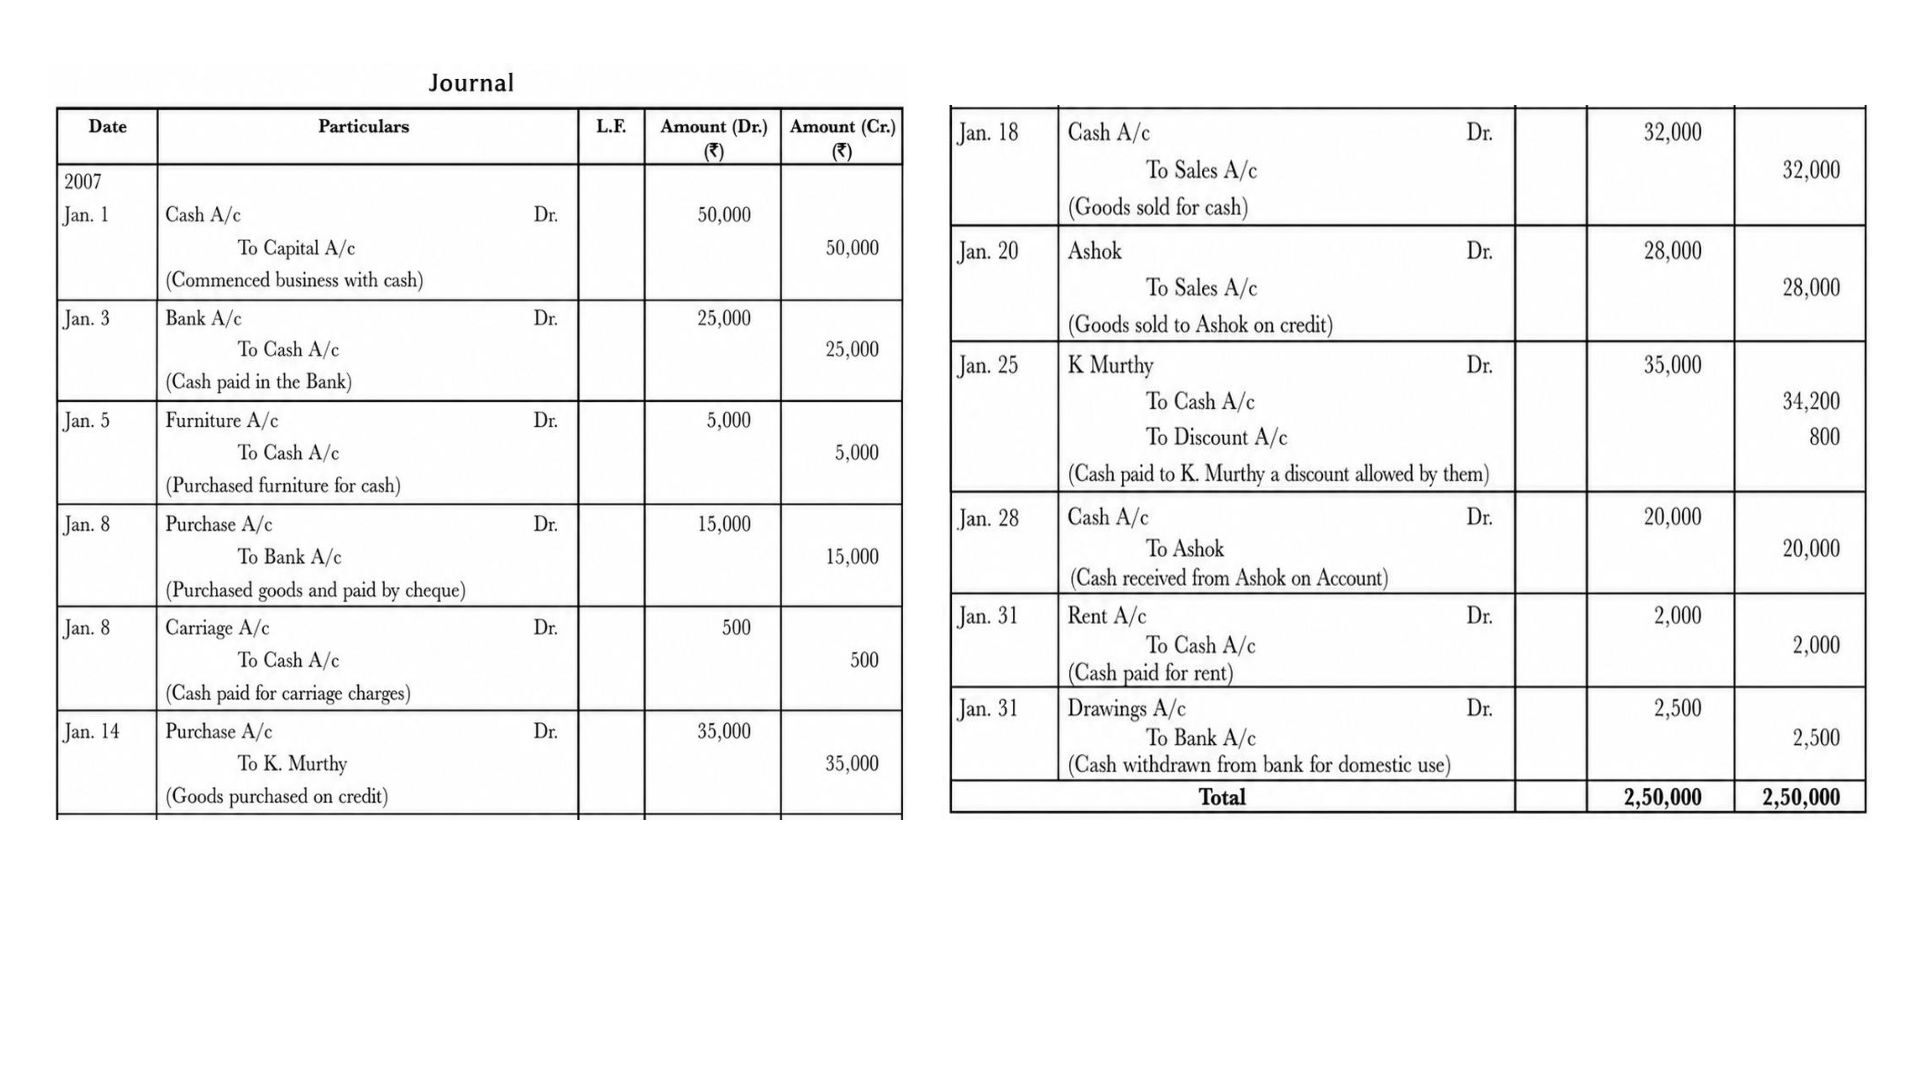
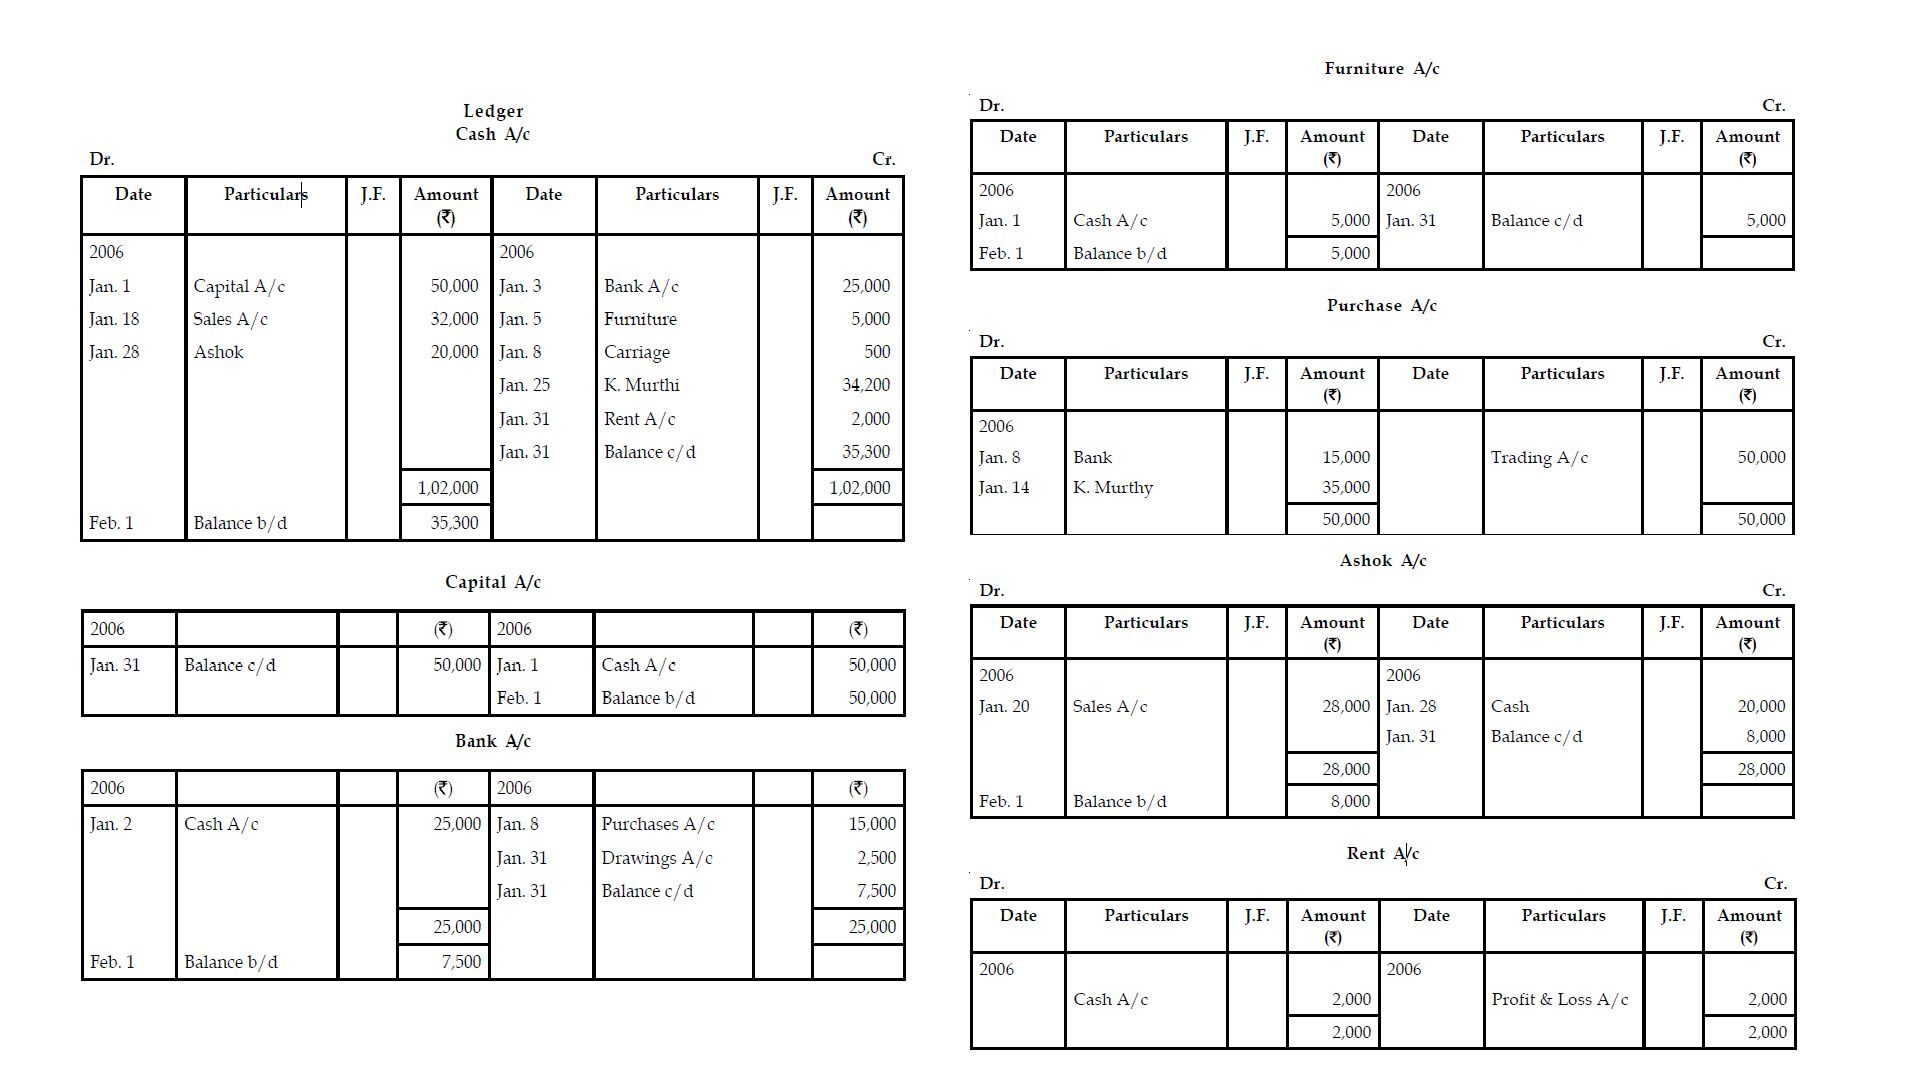
  15. Record the following transactions in the Journal and post them

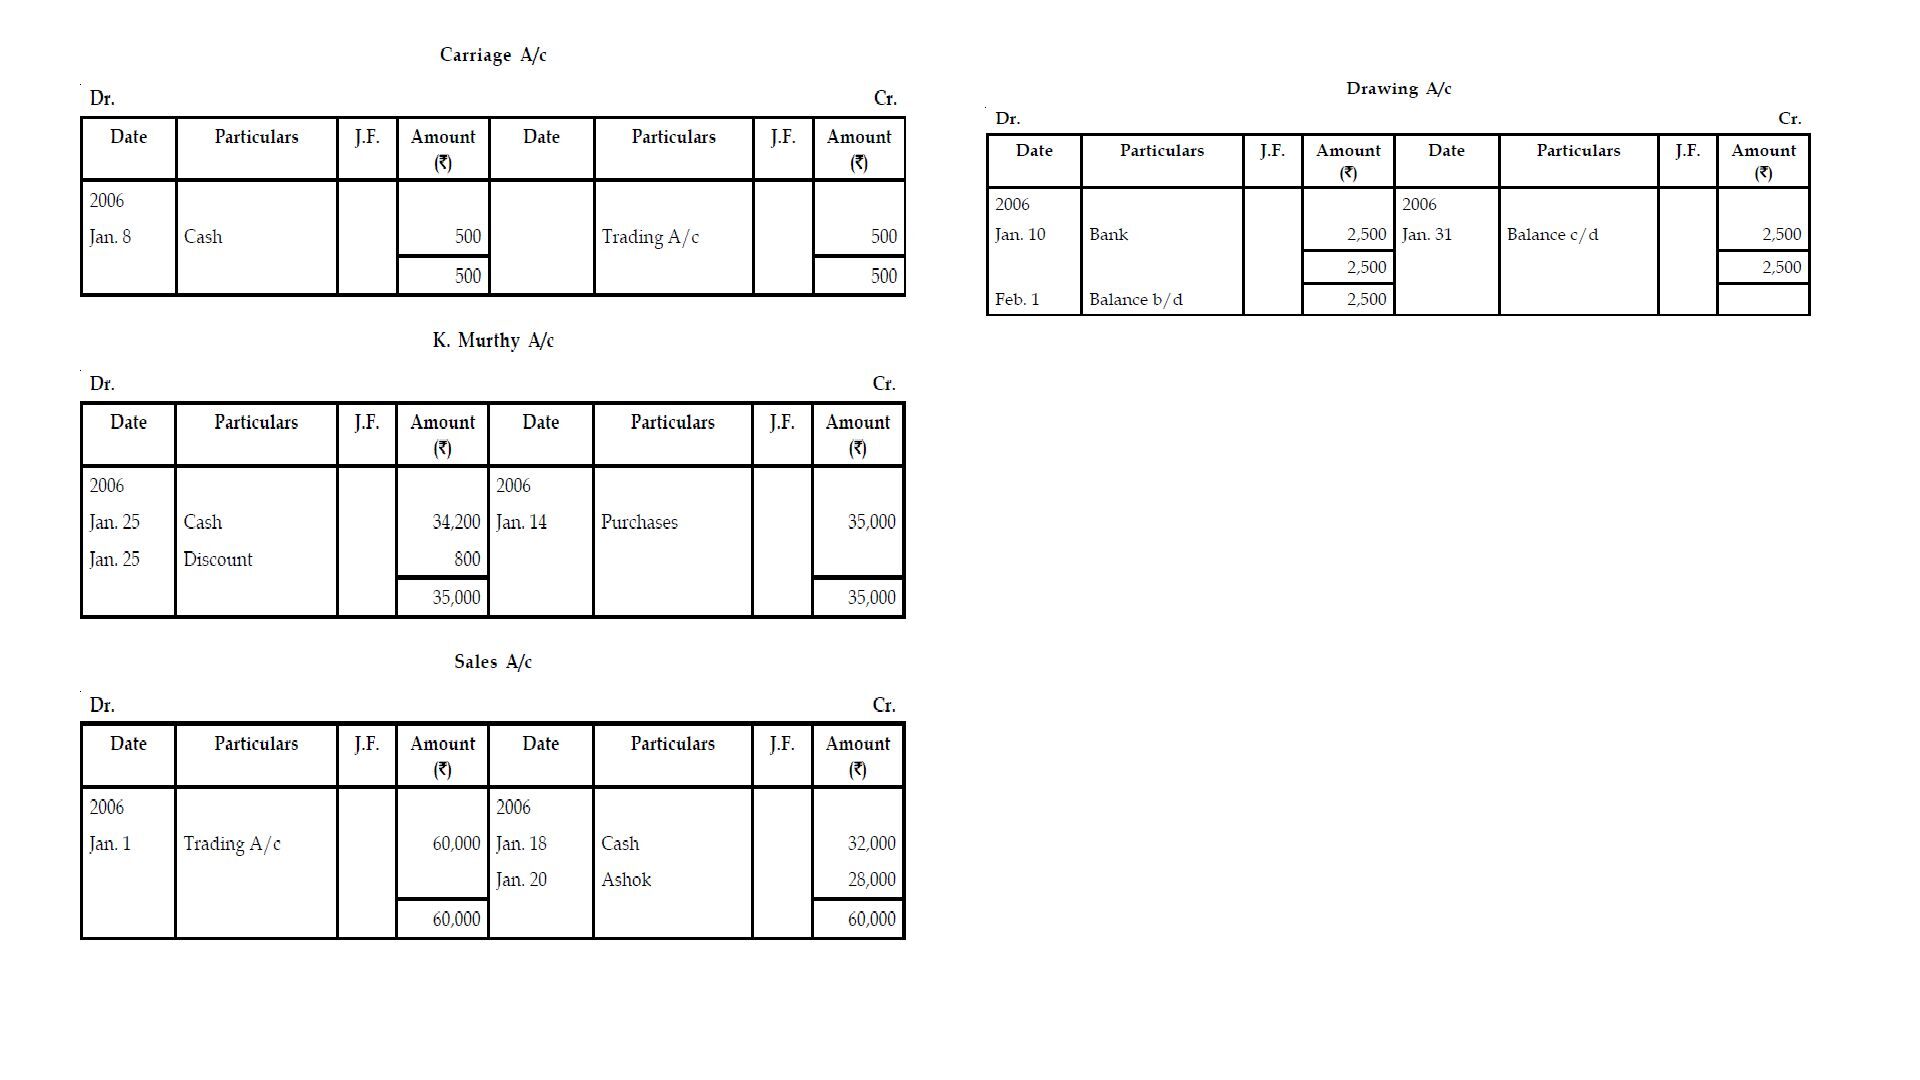
    into Ledger of Mr. Aditya Raj: 2026 January 1 3 5 8 8 14 18 20 25 28 31 31 Transactions ₹ Commenced business with cash Paid into bank Purchased furniture for cash Purchased goods and paid by cheque Paid for carriage Purchased Goods from K. Murthy Cash Sales Sold Goods to Ashok on credit Paid cash to K. Murthy in full settlement Cash received from Ashok Paid Rent for the month Withdrew from bank for private use 50,000 25,000 5,000 15,000 500 35,000 32,000 28,000 34,200 20,000 2,000 2,500
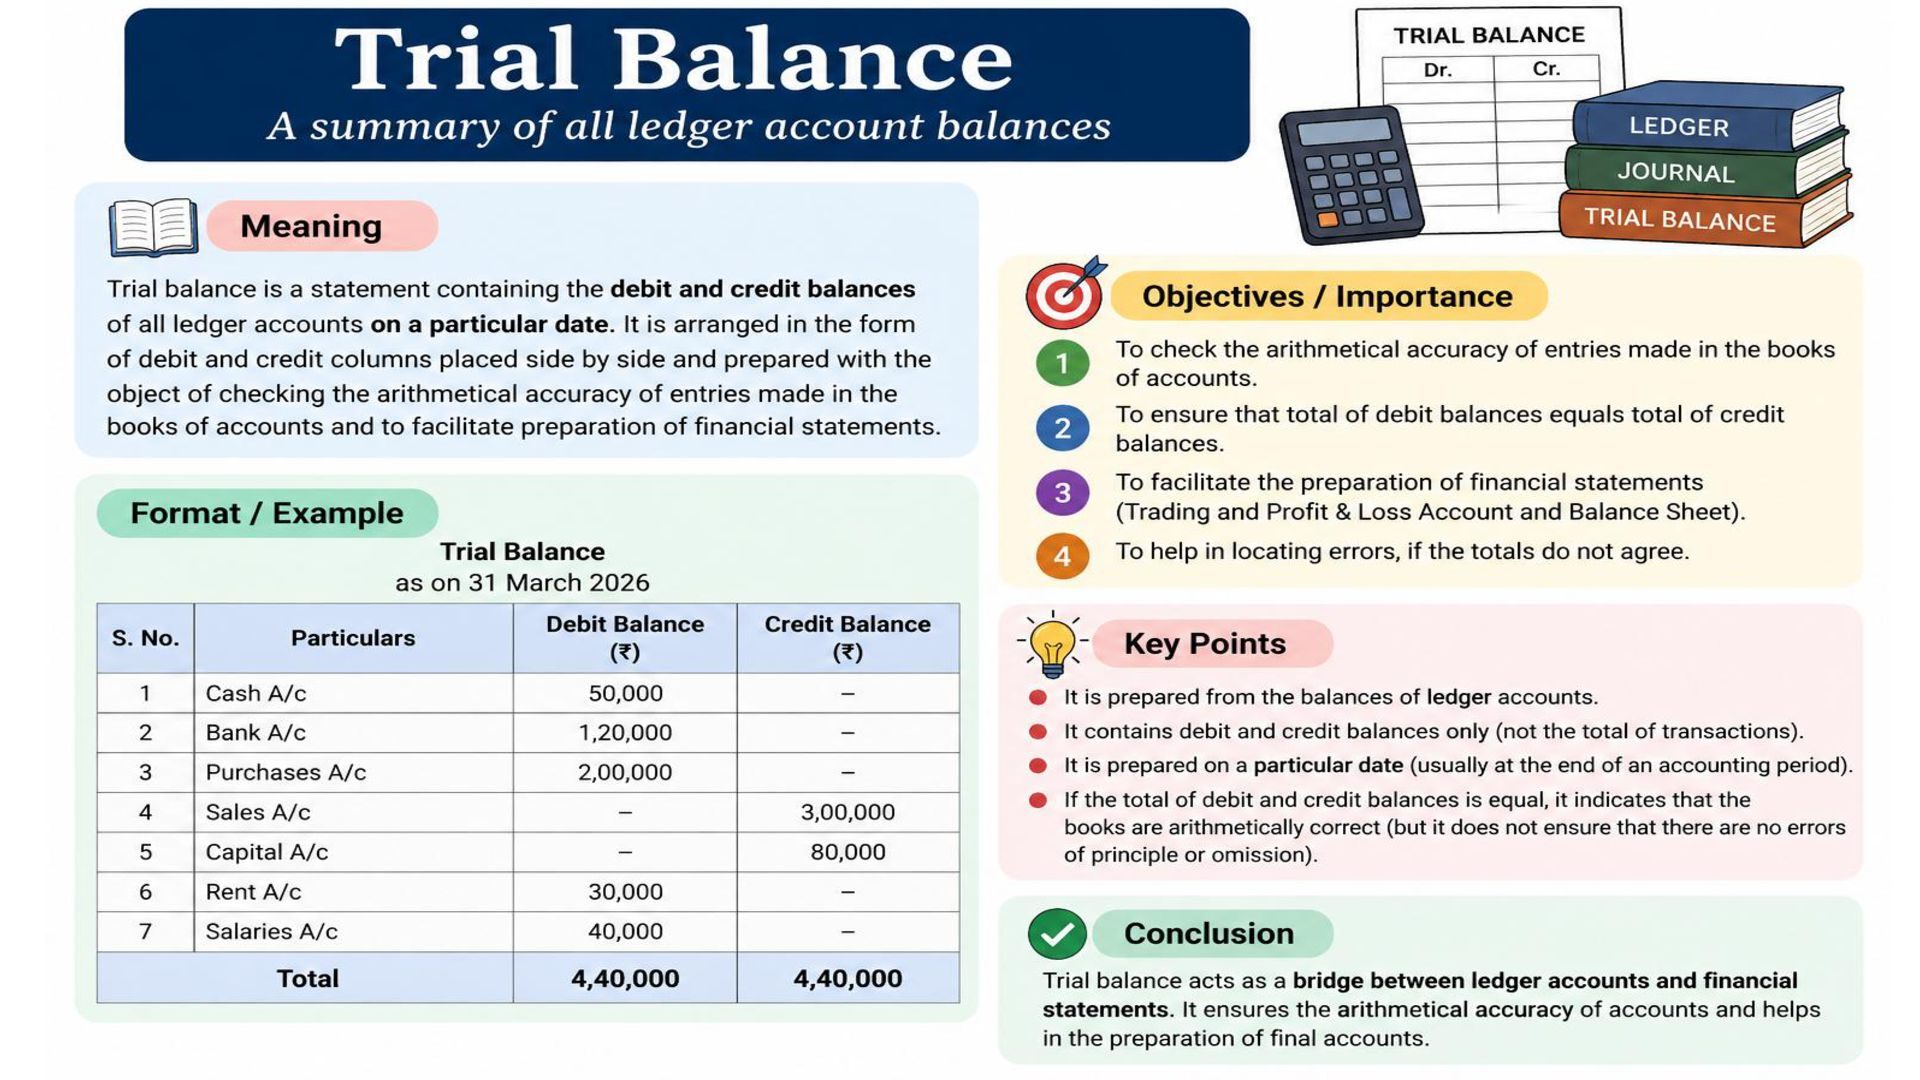
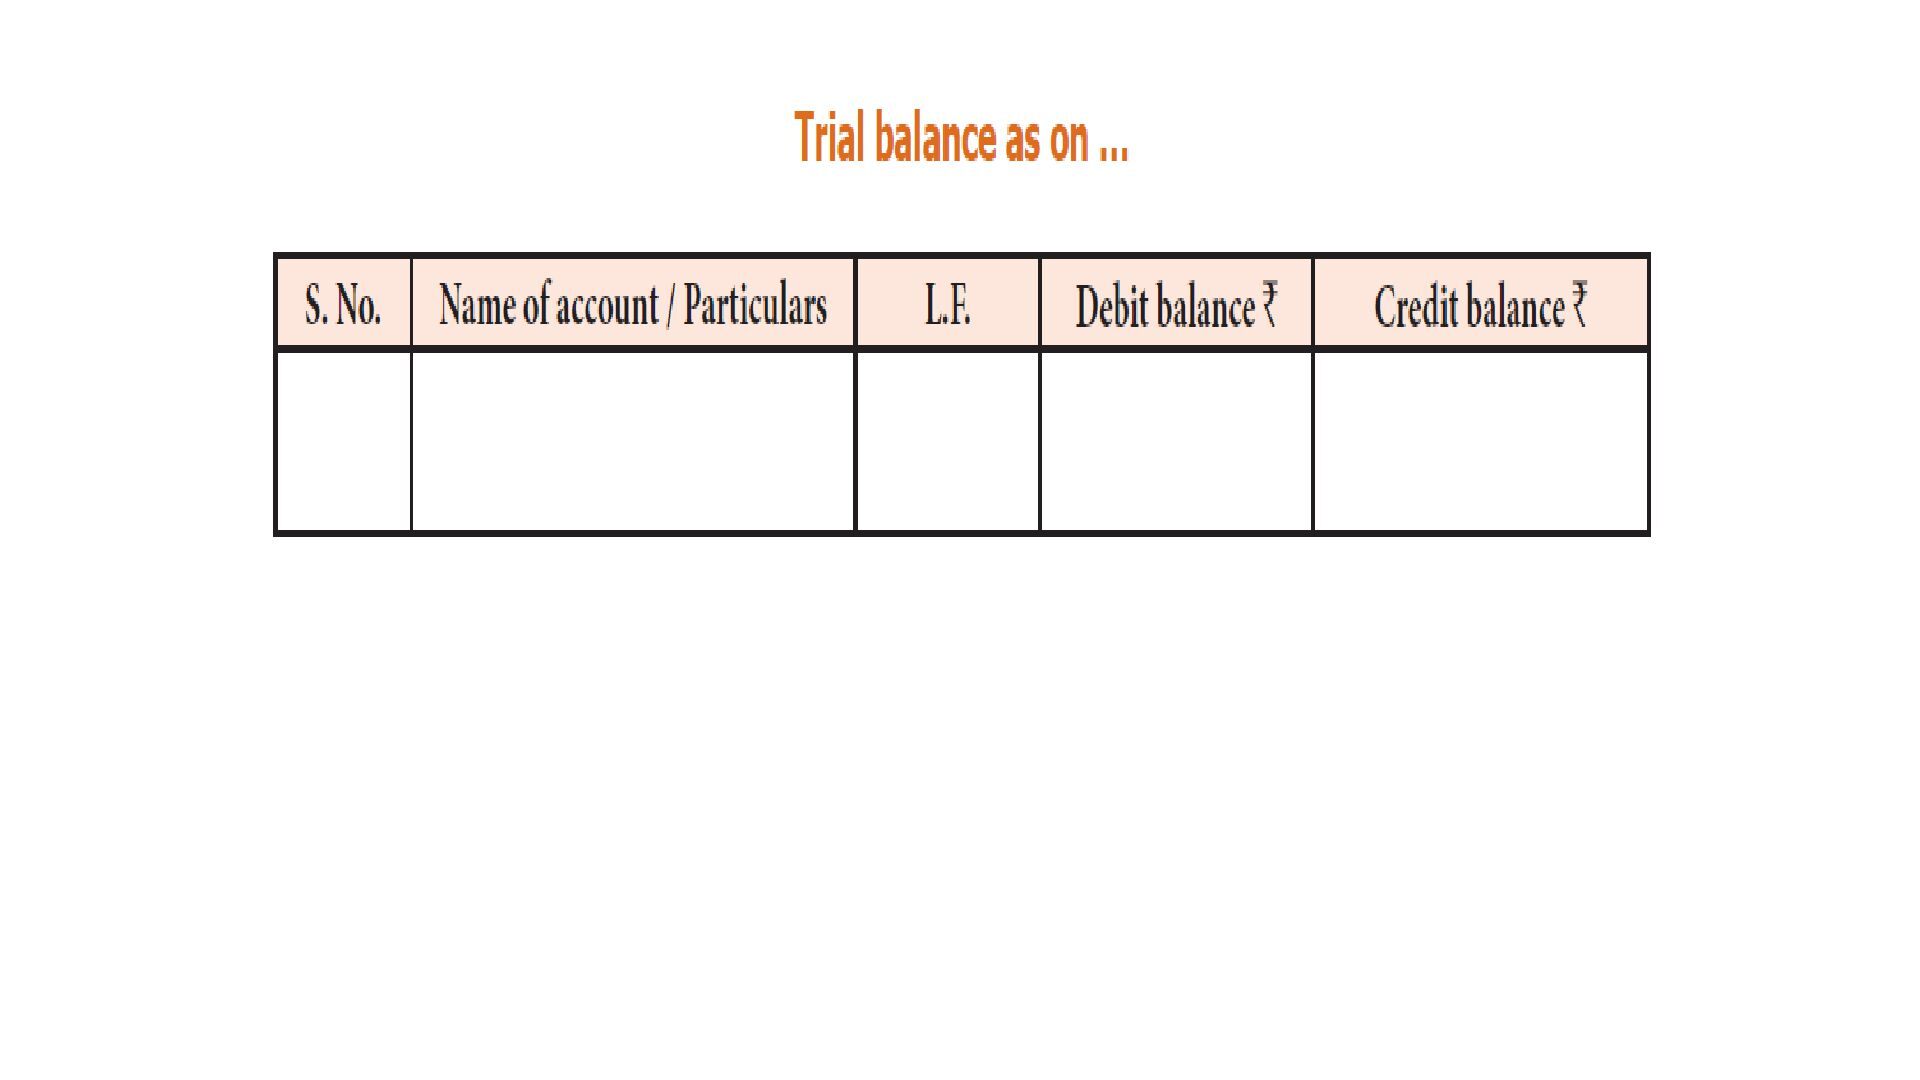
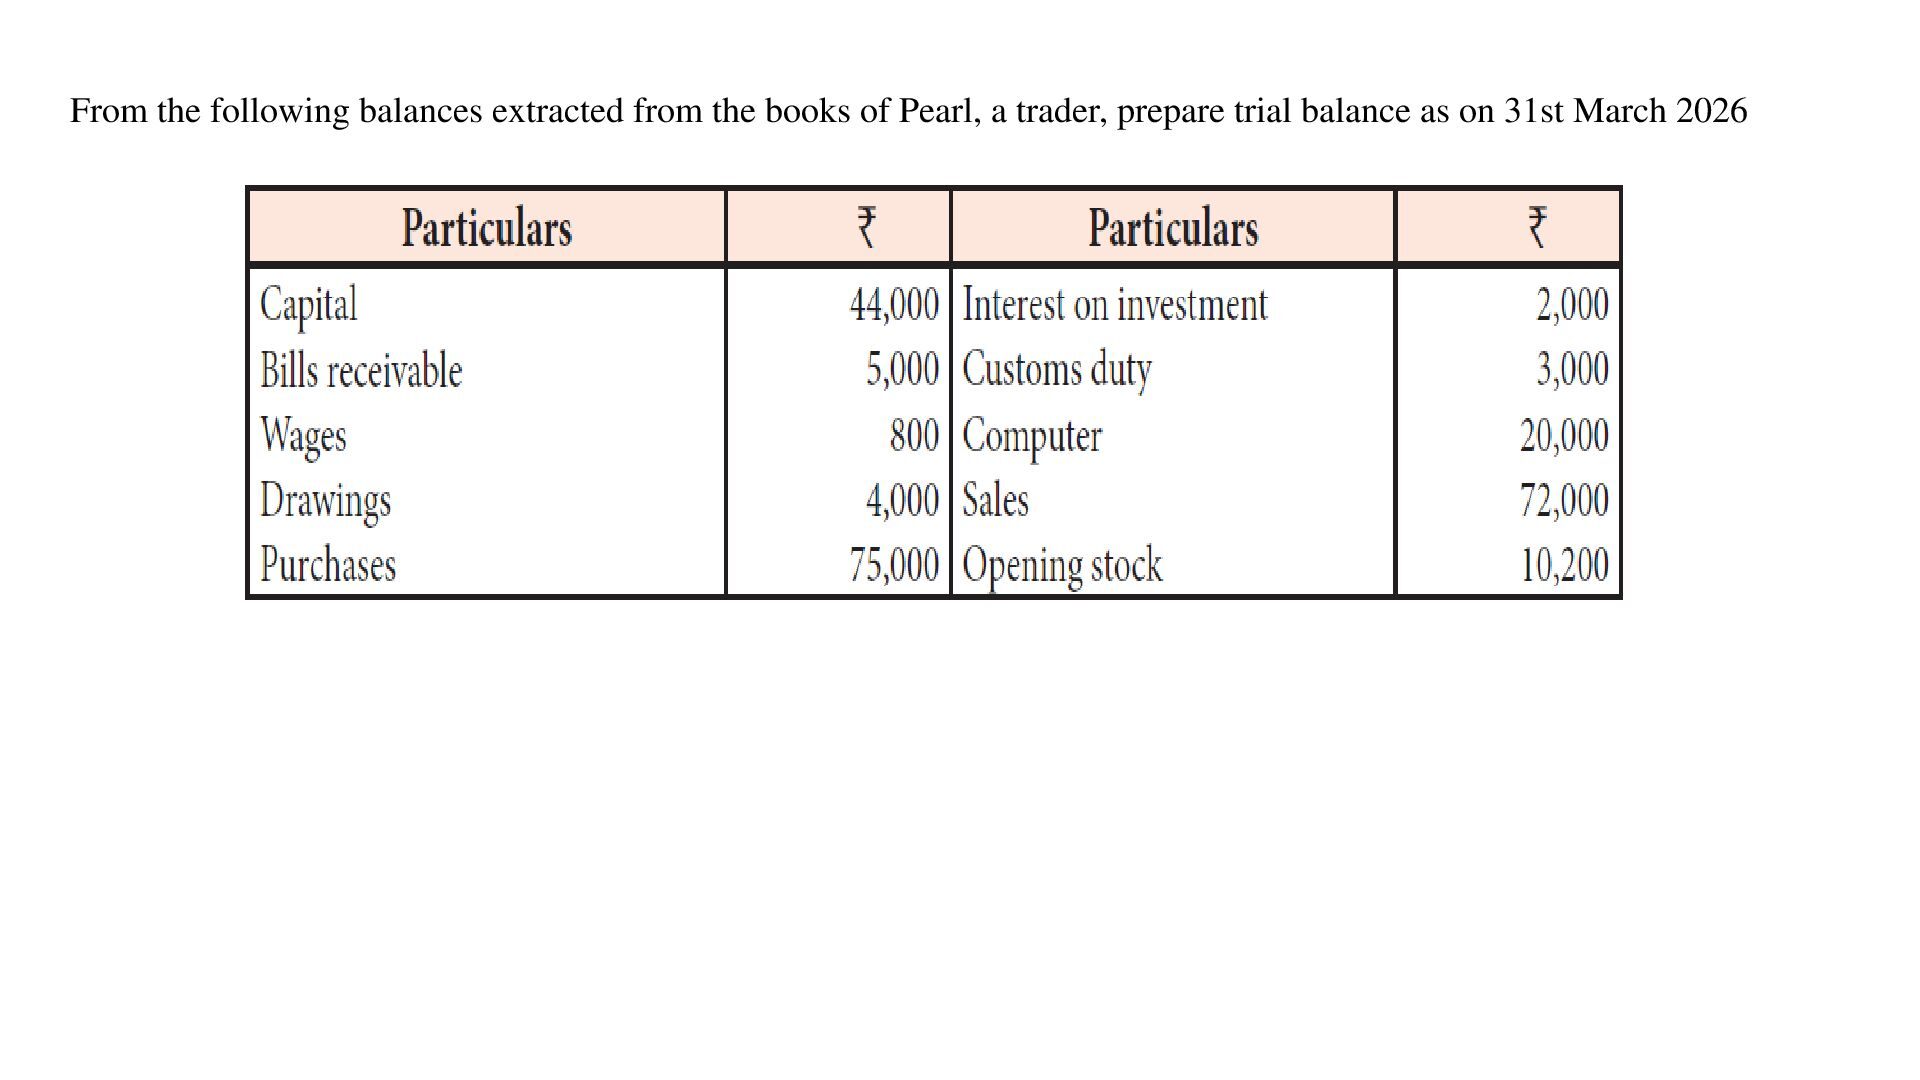
  16. From the following balances extracted from the books of Pearl,

    a trader, prepare trial balance as on 31st March 2026
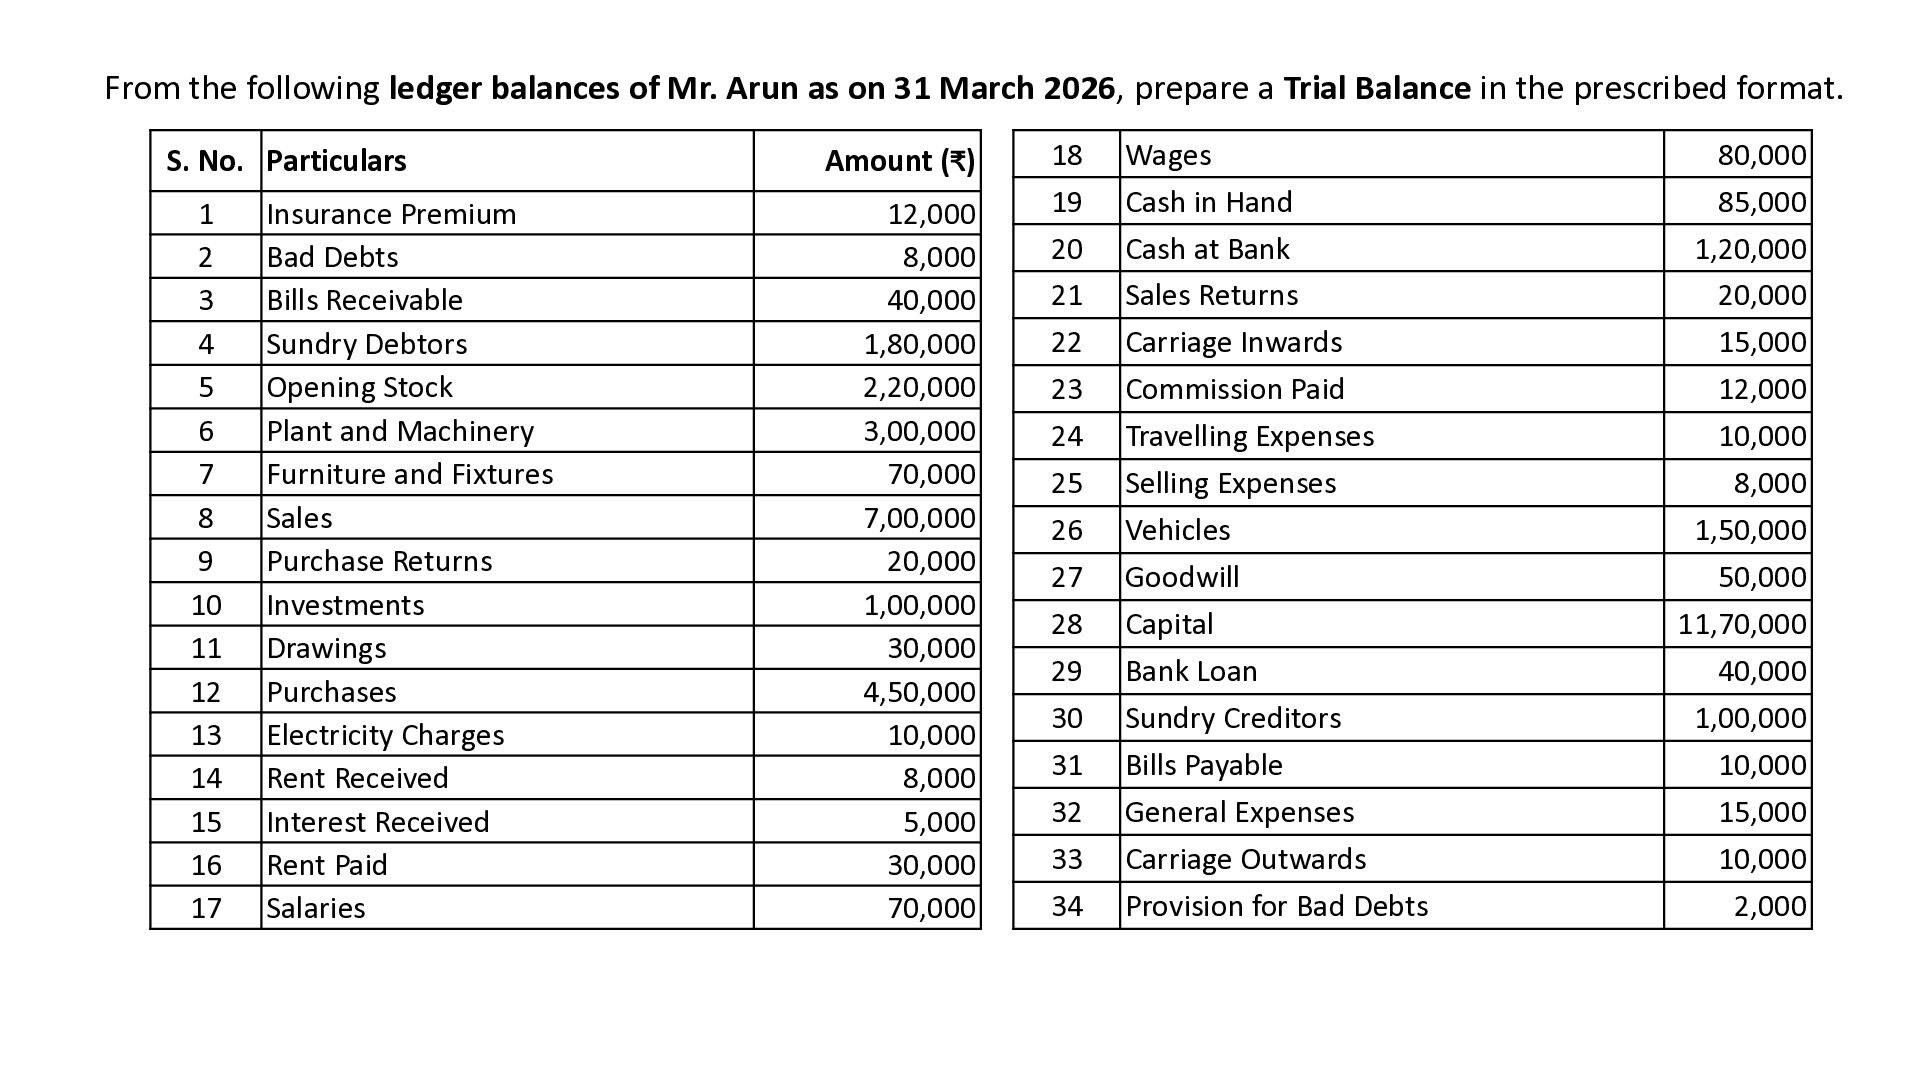
  17. From the following ledger balances of Mr. Arun as on

    31 March 2026, prepare a Trial Balance in the prescribed format. S. No. Particulars 1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 Insurance Premium Bad Debts Bills Receivable Sundry Debtors Opening Stock Plant and Machinery Furniture and Fixtures Sales Purchase Returns Investments Drawings Purchases Electricity Charges Rent Received Interest Received Rent Paid Salaries Amount (₹) 12,000 8,000 40,000 1,80,000 2,20,000 3,00,000 70,000 7,00,000 20,000 1,00,000 30,000 4,50,000 10,000 8,000 5,000 30,000 70,000 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 Wages Cash in Hand Cash at Bank Sales Returns Carriage Inwards Commission Paid Travelling Expenses Selling Expenses Vehicles Goodwill Capital Bank Loan Sundry Creditors Bills Payable General Expenses Carriage Outwards Provision for Bad Debts 80,000 85,000 1,20,000 20,000 15,000 12,000 10,000 8,000 1,50,000 50,000 11,70,000 40,000 1,00,000 10,000 15,000 10,000 2,000
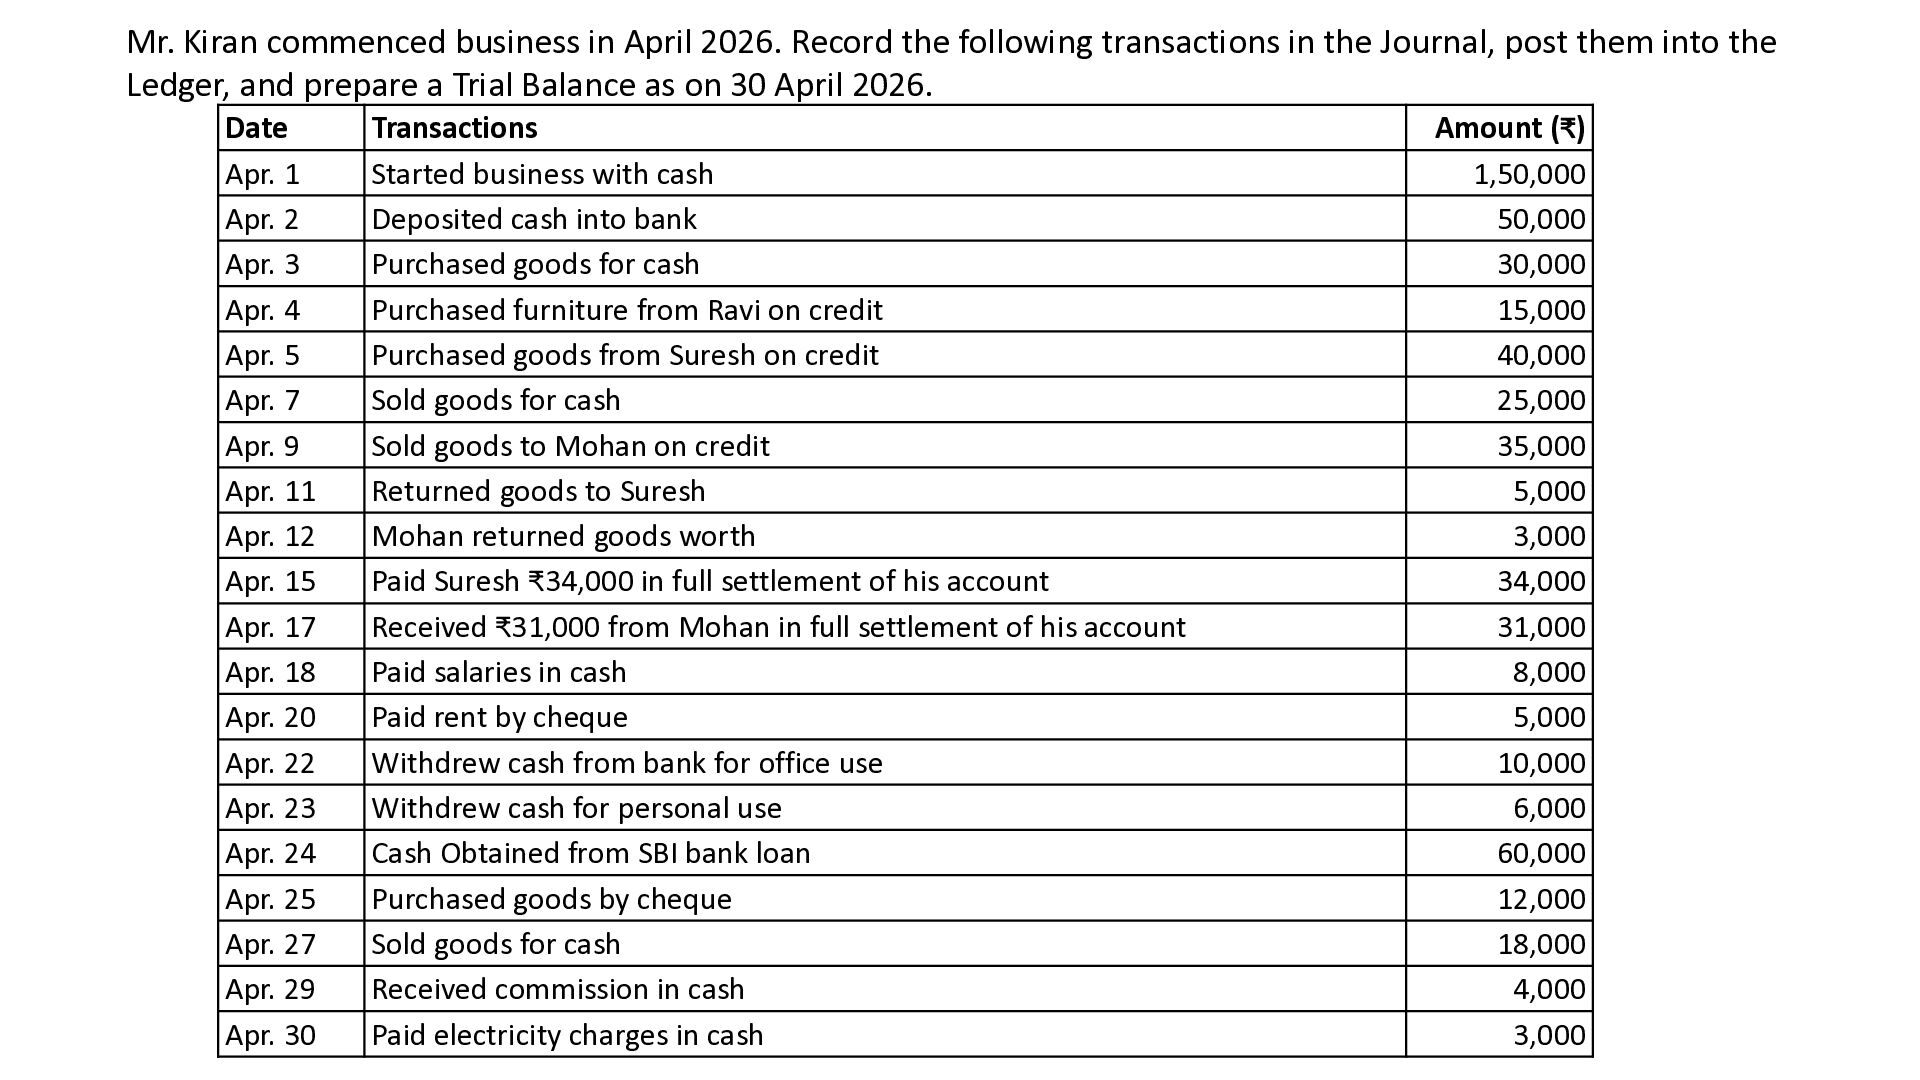
  18. Mr. Kiran commenced business in April 2026. Record the following

    transactions in the Journal, post them into the Ledger, and prepare a Trial Balance as on 30 April 2026. Date Apr. 1 Apr. 2 Apr. 3 Apr. 4 Apr. 5 Apr. 7 Apr. 9 Apr. 11 Apr. 12 Apr. 15 Apr. 17 Apr. 18 Apr. 20 Apr. 22 Apr. 23 Apr. 24 Apr. 25 Apr. 27 Apr. 29 Apr. 30 Transactions Started business with cash Deposited cash into bank Purchased goods for cash Purchased furniture from Ravi on credit Purchased goods from Suresh on credit Sold goods for cash Sold goods to Mohan on credit Returned goods to Suresh Mohan returned goods worth Paid Suresh ₹34,000 in full settlement of his account Received ₹31,000 from Mohan in full settlement of his account Paid salaries in cash Paid rent by cheque Withdrew cash from bank for office use Withdrew cash for personal use Cash Obtained from SBI bank loan Purchased goods by cheque Sold goods for cash Received commission in cash Paid electricity charges in cash Amount (₹) 1,50,000 50,000 30,000 15,000 40,000 25,000 35,000 5,000 3,000 34,000 31,000 8,000 5,000 10,000 6,000 60,000 12,000 18,000 4,000 3,000
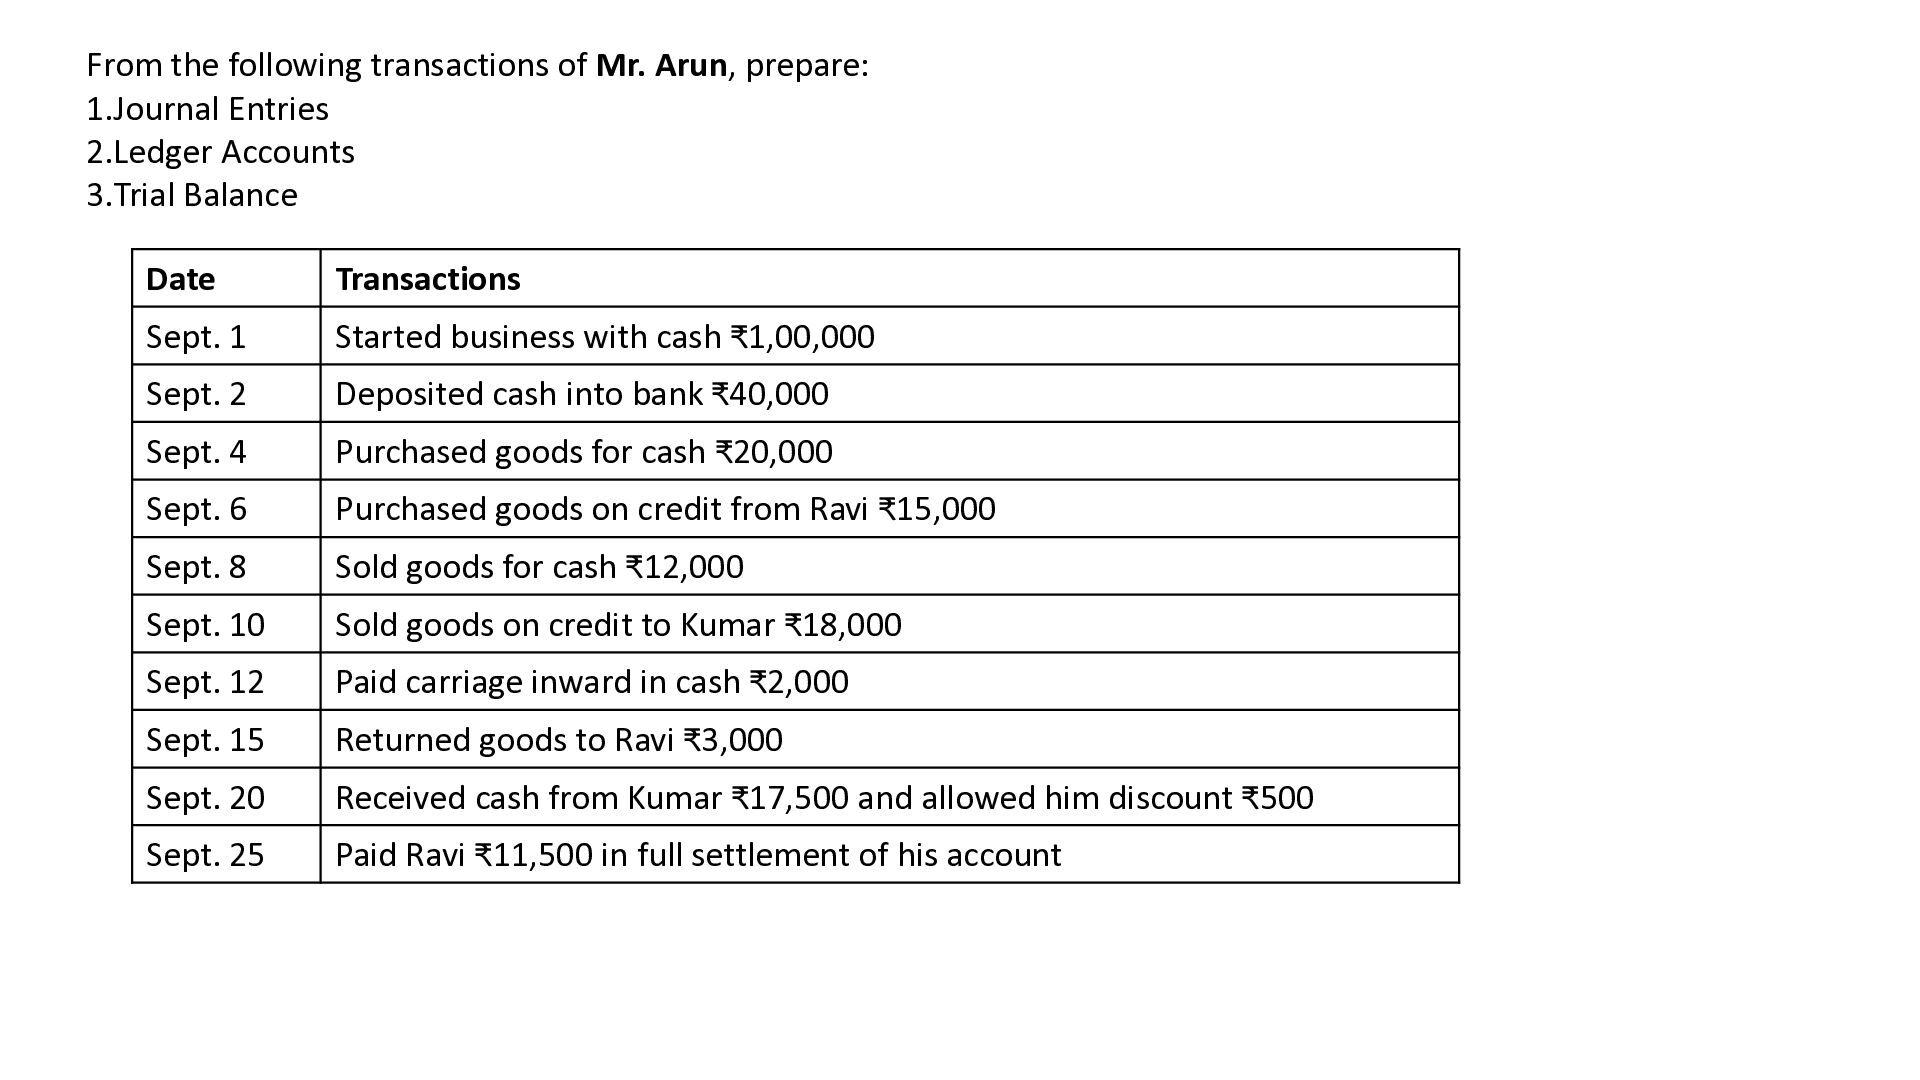
  19. From the following transactions of Mr. Arun, prepare: 1.Journal Entries

    2.Ledger Accounts 3.Trial Balance Date Transactions Sept. 1 Started business with cash ₹1,00,000 Sept. 2 Deposited cash into bank ₹40,000 Sept. 4 Purchased goods for cash ₹20,000 Sept. 6 Purchased goods on credit from Ravi ₹15,000 Sept. 8 Sold goods for cash ₹12,000 Sept. 10 Sold goods on credit to Kumar ₹18,000 Sept. 12 Paid carriage inward in cash ₹2,000 Sept. 15 Returned goods to Ravi ₹3,000 Sept. 20 Received cash from Kumar ₹17,500 and allowed him discount ₹500 Sept. 25 Paid Ravi ₹11,500 in full settlement of his account